What a Captured Flag Taught Me About Portfolios

Article #480

On the wall outside one of our meeting rooms in Hawke’s Bay hangs a faded Italian flag, framed and protected. A New Zealand soldier took it from the car of an Italian officer who surrendered to him in North Africa, and carried it home at the end of the war. It came to us through Trade Me. The seller, the soldier’s daughter, was looking for someone who would treat it with respect; her family, she explained, had no particular interest in it. I do. Behind the frame sits our correspondence and a record of her father’s service through the desert campaign. Each time I walk past it, I reflect on him, on what he carried home, and on the men who did not.
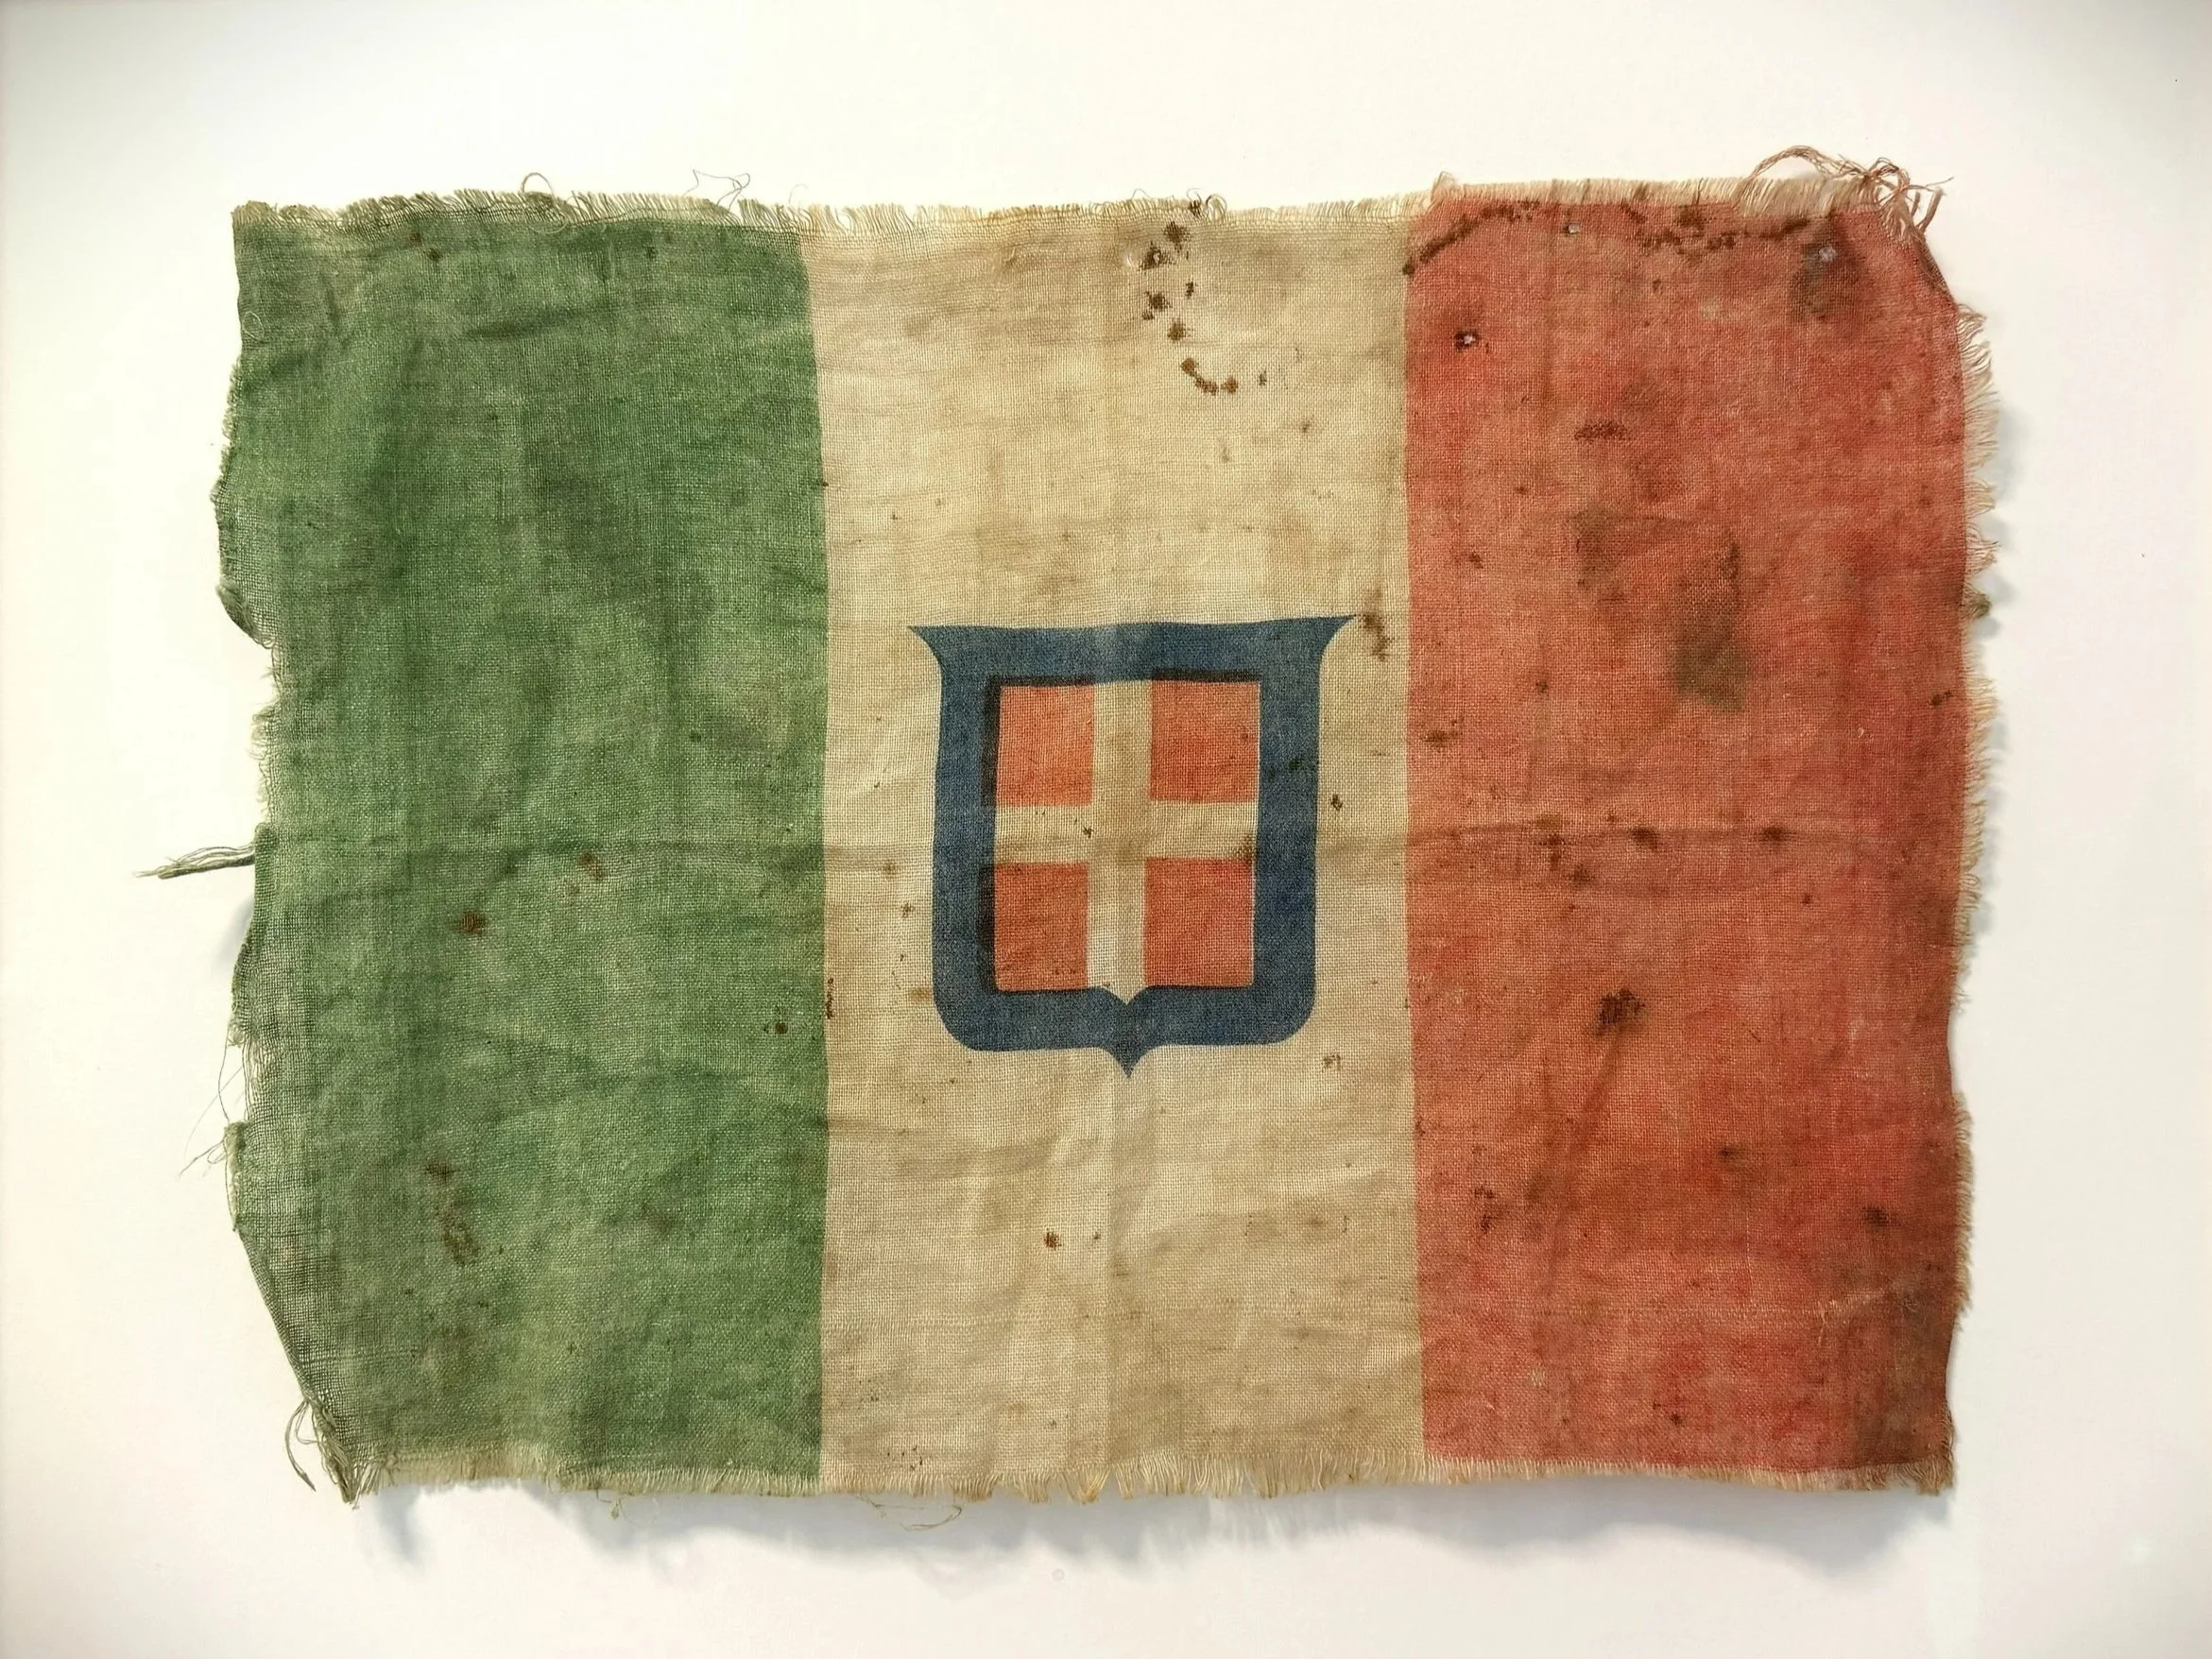
Kingdom of Italy flag (1861-1946), bearing the Savoy shield. Hung at Stewart Group Hastings

This week falls within the anniversary of the Second Battle of El Alamein, which opened on 23 October 1942 and proved to be the turning point of the war in North Africa [1].

A campaign too easily forgotten

North Africa is one of the more underappreciated chapters of the Second World War. Public memory, perhaps understandably, gravitates to the great set-piece moments we still tell stories about, including the Battle of Britain, the Dam Busters, the famous bombing raids and naval engagements. North Africa is, by comparison, a forgotten campaign. Yet for New Zealand forces, it was the longest and most important land campaign of the war. The 2nd New Zealand Division, under Bernard Freyberg, fought from 1941 through to the Axis surrender in Tunisia in May 1943 [2]. The cost was severe. By the end, almost 14,000 New Zealanders had been killed, wounded, or taken prisoner [3]. Keith Elliott and Te Moananui-a-Kiwa Ngārimu were awarded the Victoria Cross, while Charles Upham earned a bar to his existing VC. [4] Ngārimu’s was posthumous, awarded for his actions at Tebaga Gap in Tunisia in March 1943 [5].

I’ve been reading Saul David’s recent history of the campaign, Tunisgrad [6]. The title is a deliberate echo of Stalingrad, and the parallel is more than rhetorical. Tunisia was an attritional, brutal phase of the war that effectively destroyed Axis power on the African continent. By the time it ended in May 1943, more than a quarter of a million Axis troops had been taken prisoner [7]. New Zealand units, including the 28th (Māori) Battalion, were instrumental in the final push [8]. The campaign succeeded not through any single moment of brilliance but through grinding, disciplined, collective effort.

Supply lines and lost vehicles

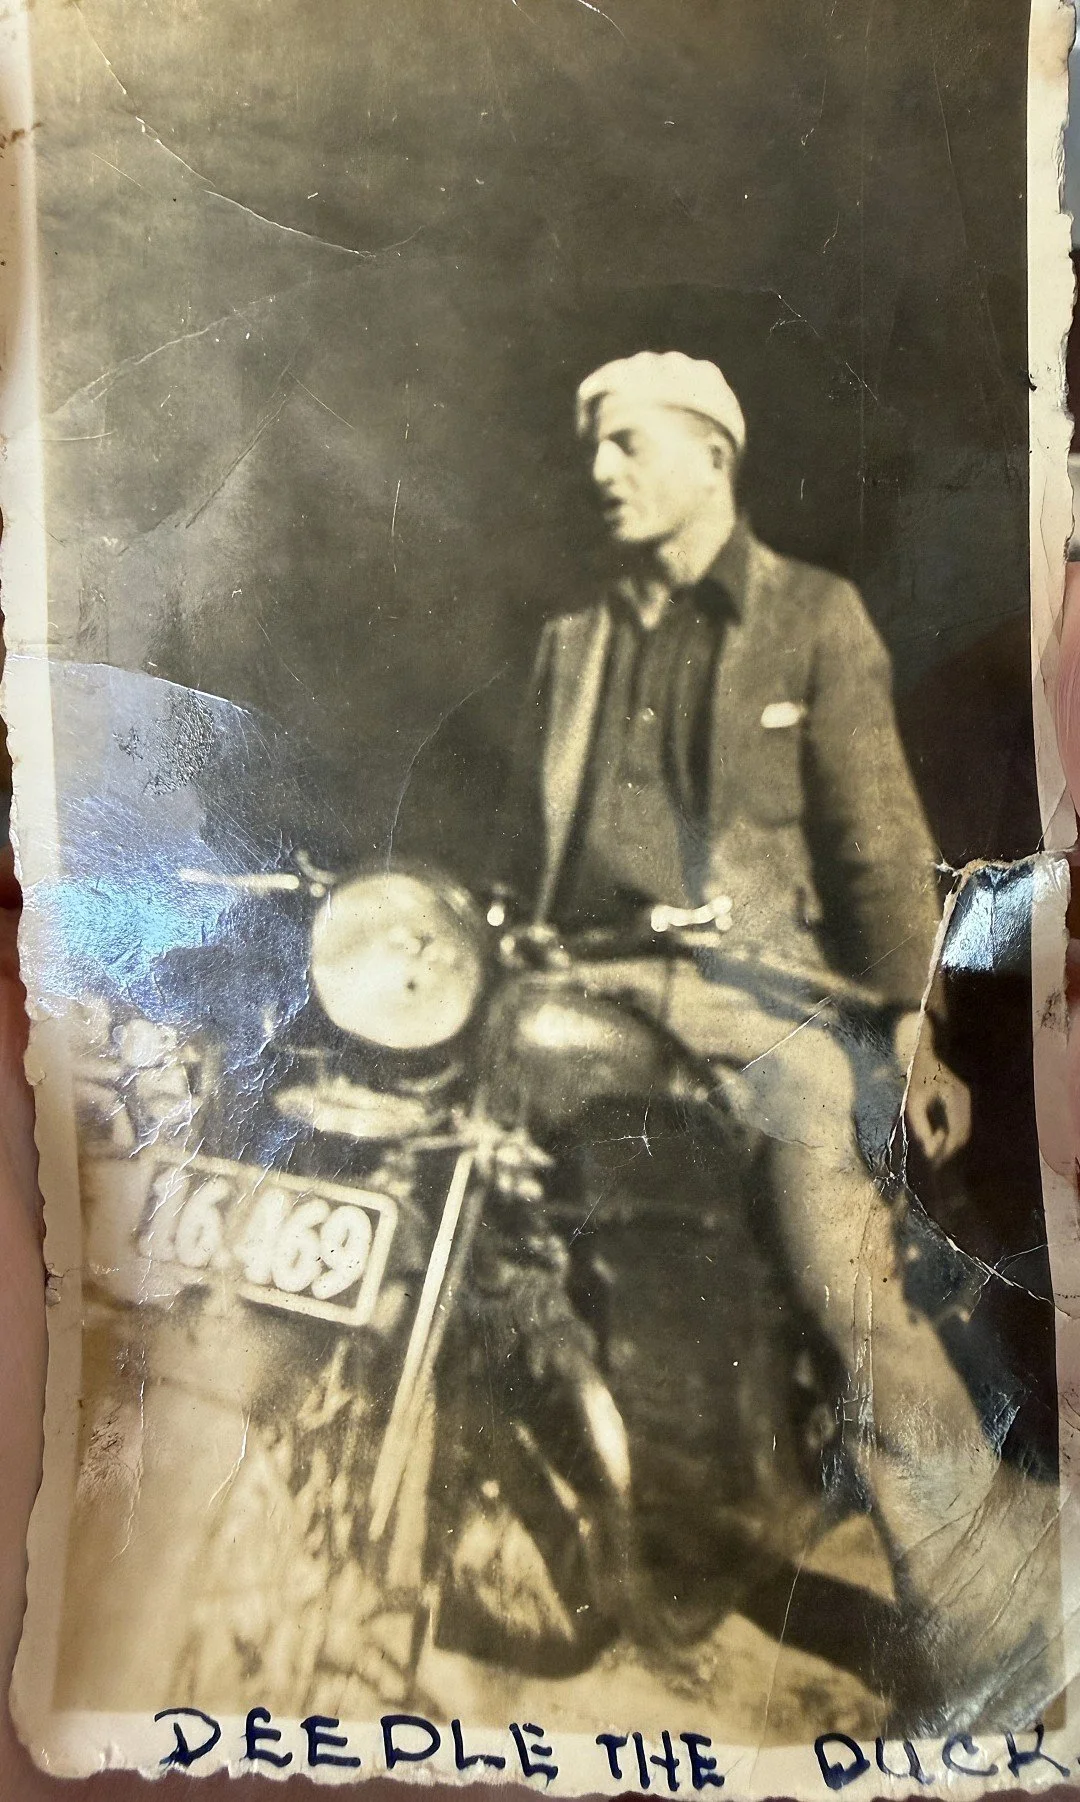
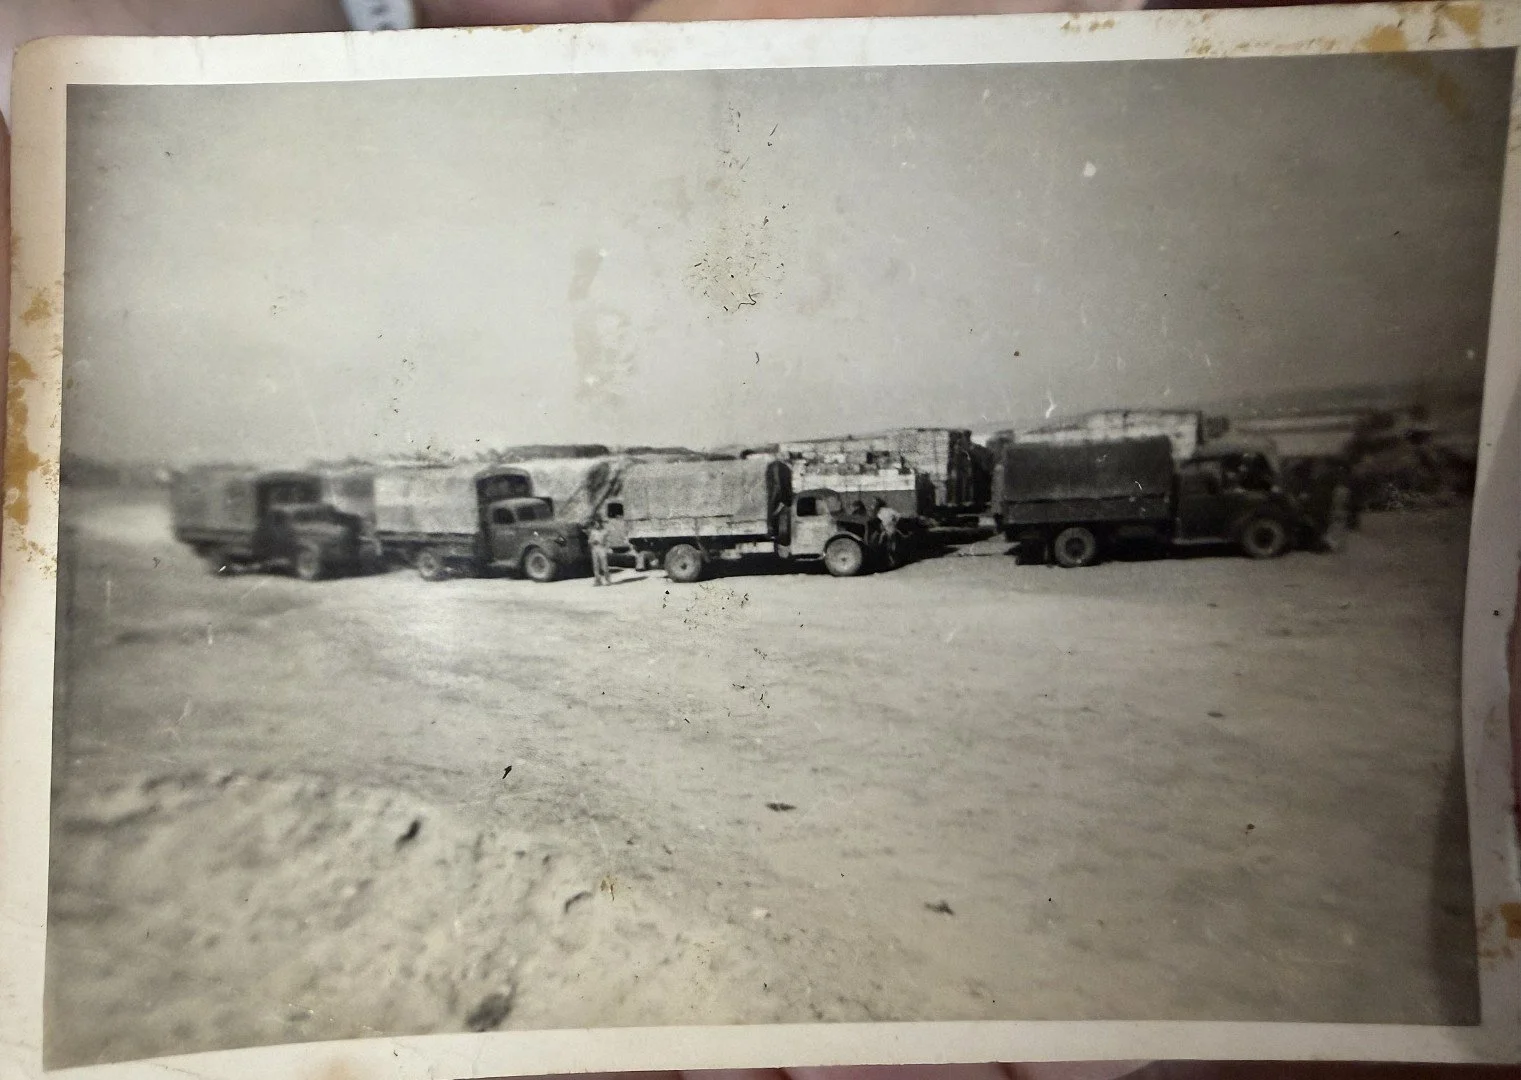
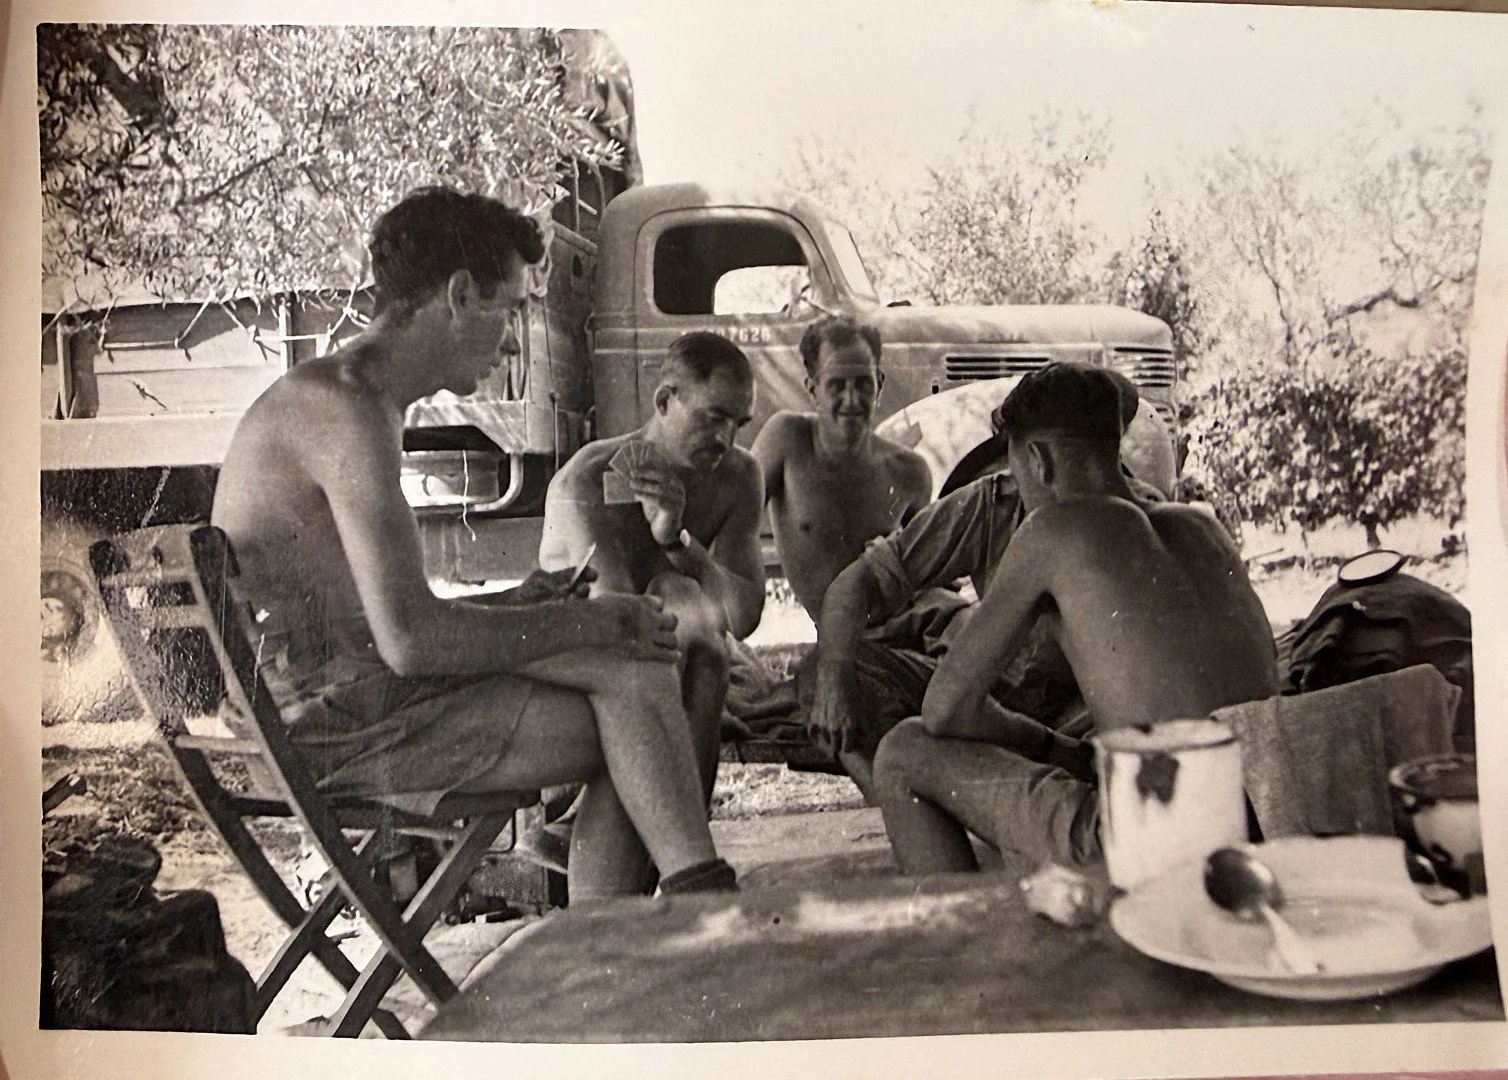
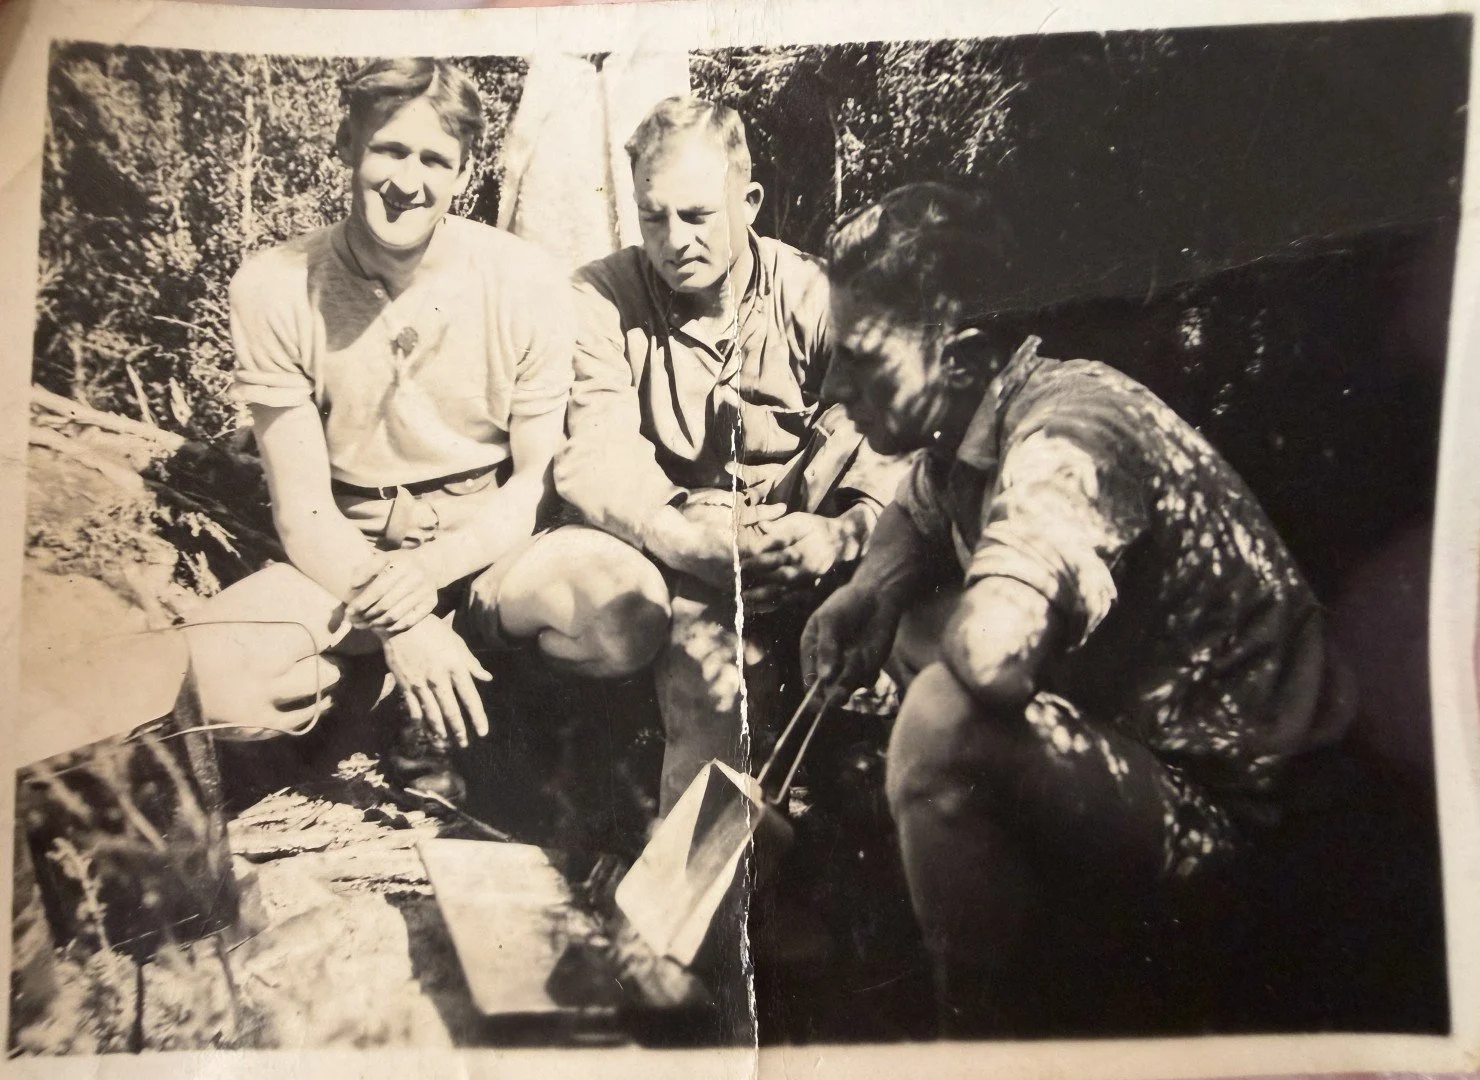
That phrase, grinding, disciplined, collective effort, has a personal resonance for me. My uncle’s father, Mick, drove trucks through the campaign. Long-haul supply runs across hundreds of kilometres of empty desert, the same featureless terrain stretching away to the left and to the right, hour after hour. He told stories of vehicles ahead and behind that simply vanished, lost, misdirected, captured after wandering unwittingly into enemy lines. The desert did not care whether you were brave or careful. It swallowed people whole.

Even the highest-ranking commanders were not safe. In April 1941, Lieutenant-General Richard O’Connor, the architect of Operation Compass, the man who had just destroyed an Italian army many times the size of his own, was lost to the desert in exactly the way Mick described. His unescorted staff car ran into a German patrol at night. He spent more than two years as a prisoner of war [9]. One of Britain’s most capable early-war generals, removed from the campaign after encountering enemy forces in the dark.

What that tells you about the campaign is what stays with me. North Africa was won by men like Mick, hauling fuel, water, ammunition and food day after day across terrain that could swallow you in an afternoon. It was a war of logistics. The headlines went to the Upham VCs, and rightly so. But the campaign was won by the truck drivers, the signallers, the engineers, the cooks, and the riggers. The unglamorous work that, together, kept everything else possible.
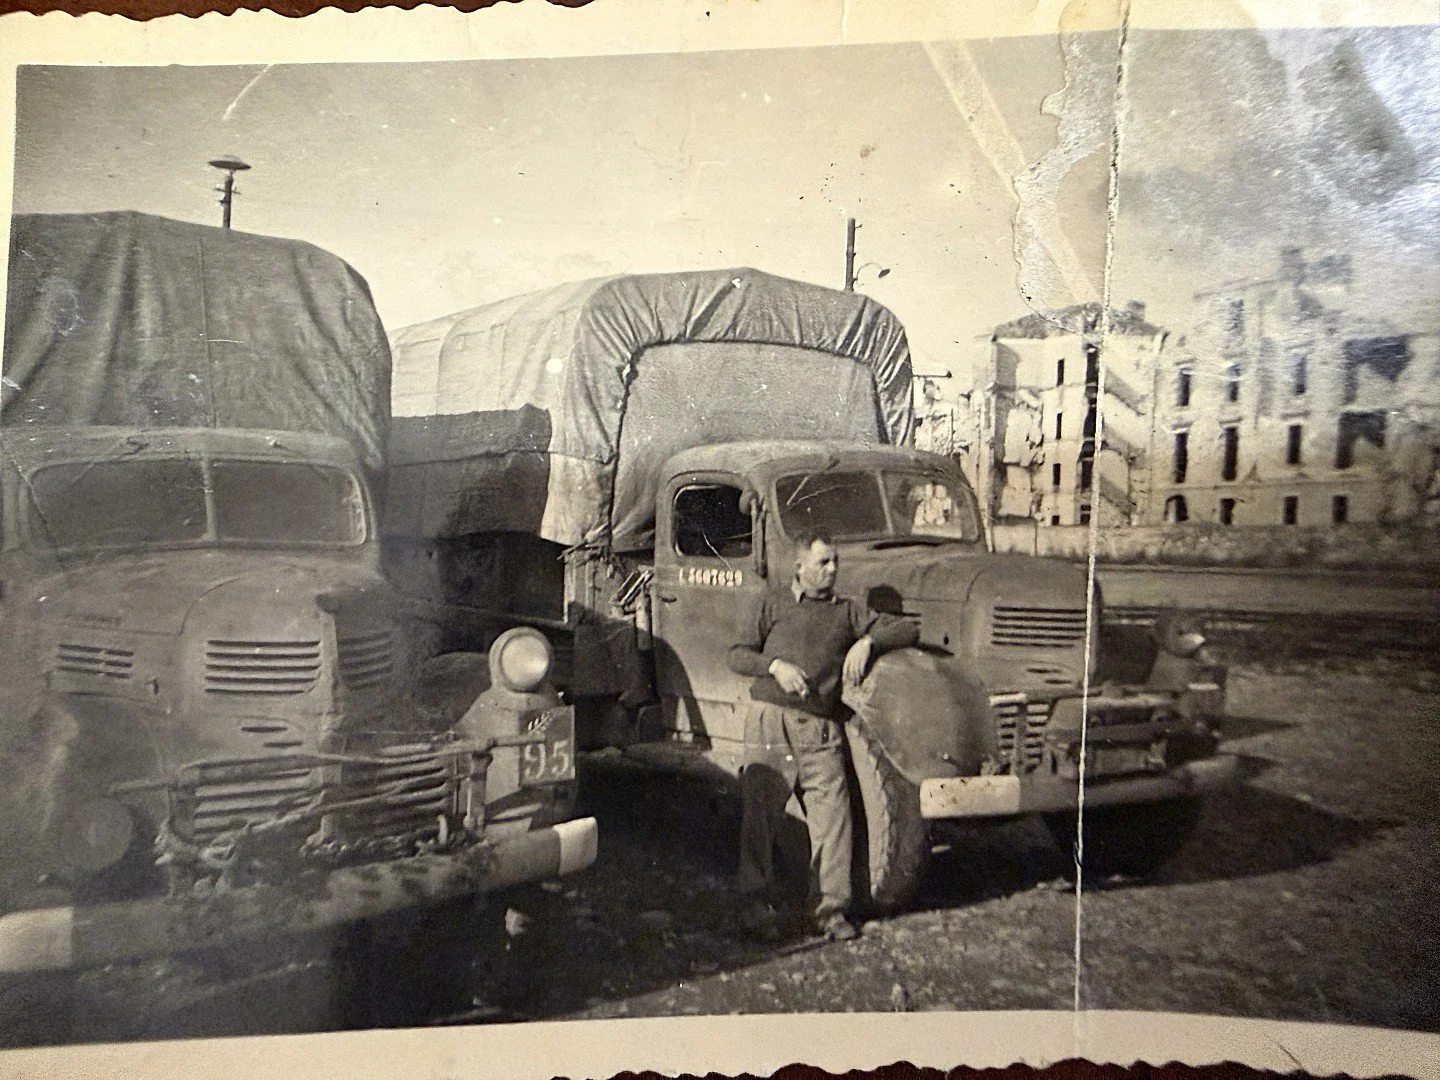
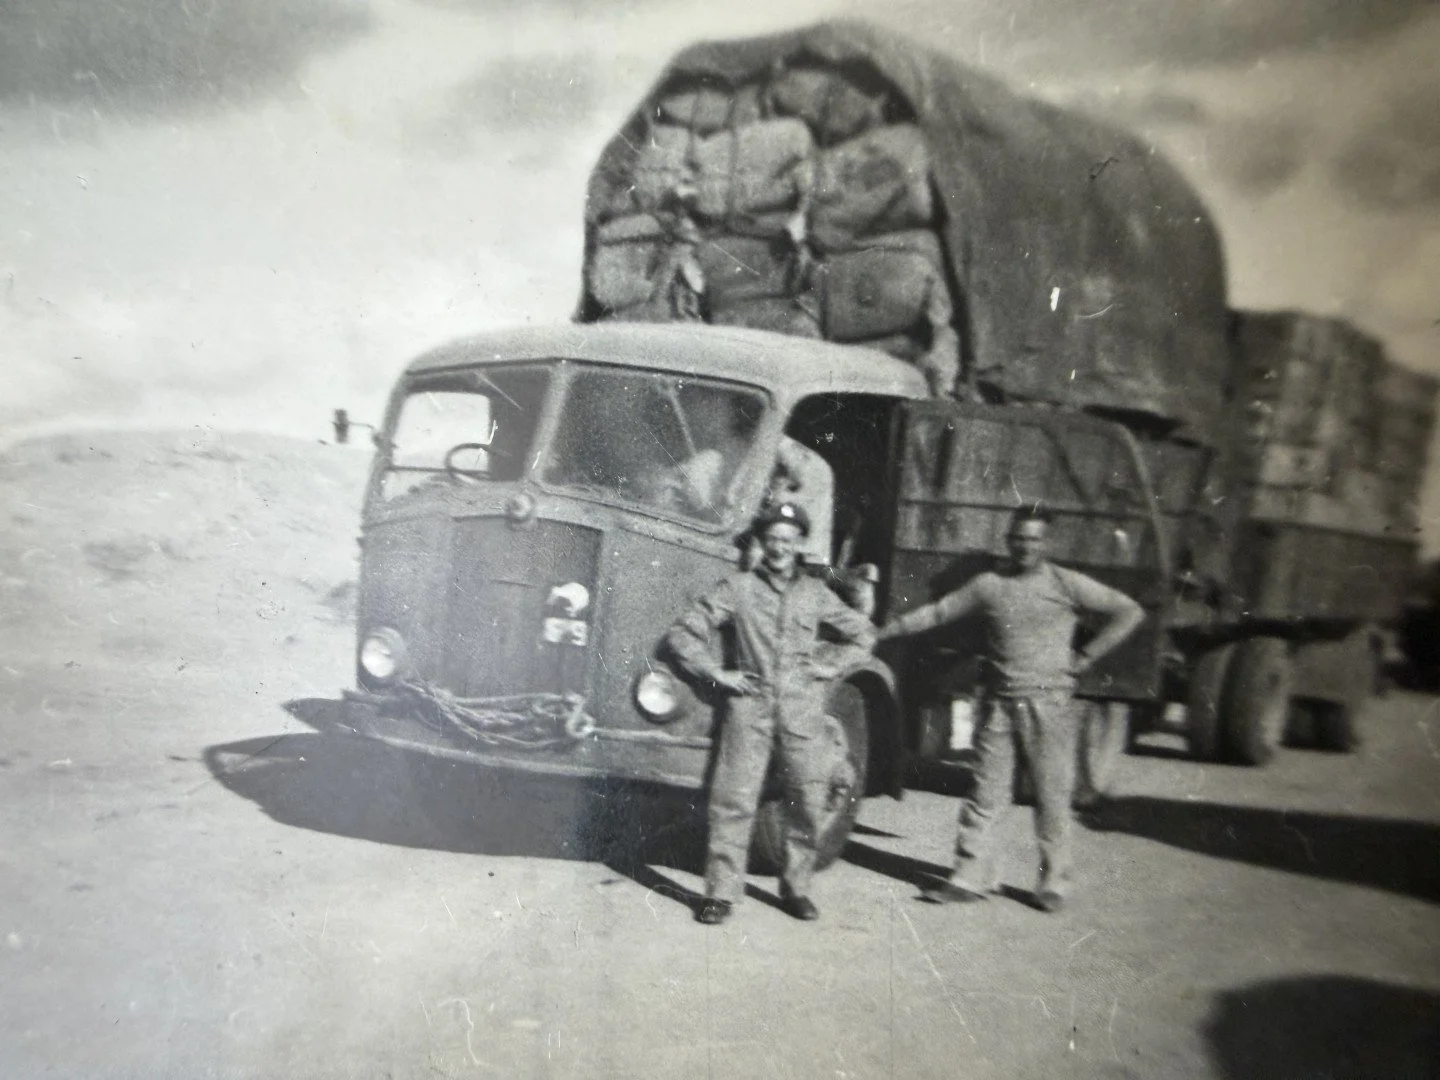
Photographs of Mick Harper and his fellow servicemen during the North African campaign. From his personal collection.

The investor’s mistake

I see the same pattern, again and again, in the way investors approach their capital.

In 2025, emerging markets were the top-performing asset class in Mercer’s table of investment returns [10]. The year before, it was something else. The year before that, something else again. The financial press, the broker community, and a fair share of advisers spend extraordinary energy trying to identify next year’s winner ahead of time. Portfolios get reshaped around the standout of the moment. The steady holdings that quietly do their job (international bonds, defensive equities, infrastructure, cash, sometimes even the unloved local market) get treated as dead weight. Investors look at them with disdain and ask why they aren’t pulling their weight.

This is, I believe, the central error of contemporary investing. Winners are hard to find in advance. Winners are not consistent. Persistence studies of actively managed U.S. funds show that sustained outperformance relative to peers is difficult to maintain [11]. A portfolio that constantly chases the leader is, in effect, fighting the last war.
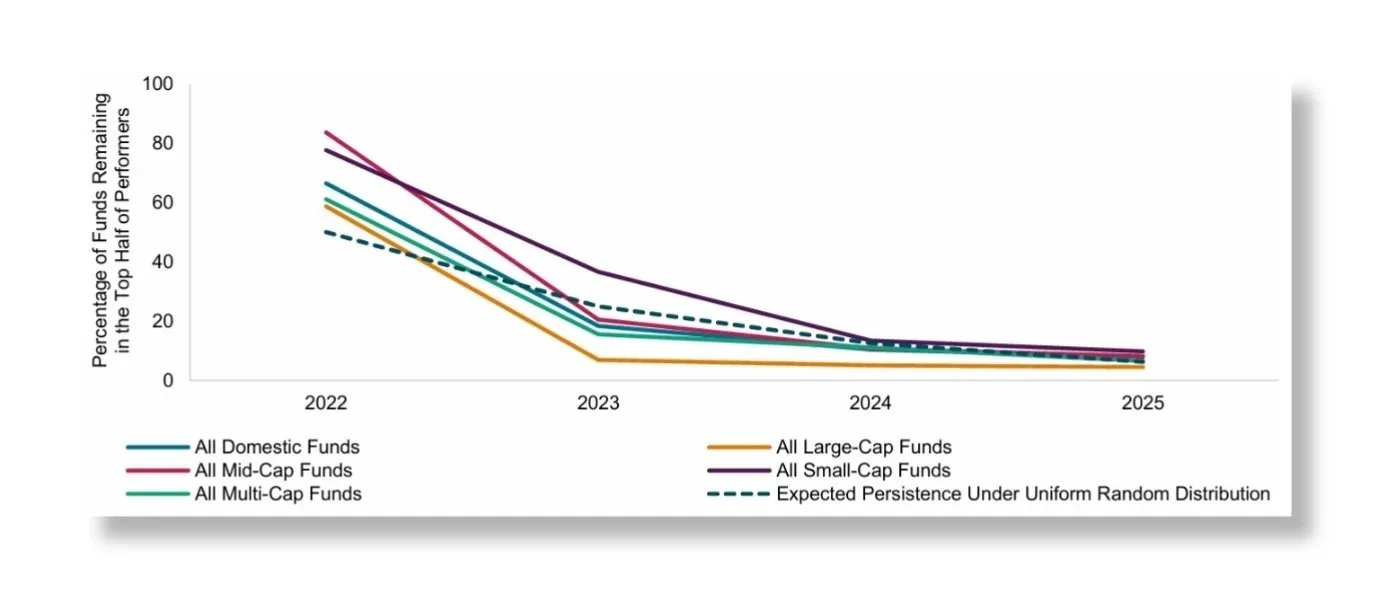
Source: S&P Dow Jones Indices LLC, CRSP. Data as of Dec. 31, 2025. Chart is provided for illustrative purposes. Past performance is no guarantee of future results.

A portfolio built like a campaign

A well-constructed portfolio looks rather more like the El Alamein order of battle than a Victoria Cross citation. It contains assets that, individually, may never make headlines but which, together, hold the line when conditions turn. Diversification is the discipline of accepting, in advance, that you cannot pick the winner every time, and structuring accordingly. Each holding has a job to do. The bond allocation isn’t there to outperform equities; it’s there to absorb the shock when equities sell off. The international exposure isn’t there to beat the local market; it’s there to ensure that when the New Zealand economy struggles, you aren’t entirely captive to it.

The investors I’ve seen do well over decades are not the ones who called emerging markets right in 2025 or technology in 2020. They are the ones who held a sensible mix, rebalanced when they had to, and resisted the urge to chase. Their portfolios looked, frankly, a little boring. That was precisely the point. Their wealth compounded quietly while flashier portfolios round-tripped through booms and busts. Separately, research by Brinson and colleagues found that asset-allocation policy explained most of the variation over time in the pension portfolios’ returns [12].

History repeats because human nature does. The temptation to swap a steady asset for something flashier is the same temptation that, in another context, has had armies betting on single decisive engagements rather than the patient grind. Discipline wins campaigns. Discipline builds wealth. The mechanisms are different; the underlying principle is the same.

What the flag reminds me of

There is a further lesson here, and it is harder to express. The soldiers who fought at El Alamein and through Tunisia were, in the main, ordinary people. They were not, for the most part, looking for glory. They were looking to do their job, survive, and come home to their families. The freedom and the global prosperity we enjoy today rests on what they did and on what those who did not come home gave up.

When I look at that flag, I’m reminded that the work of building something durable, whether a free society or a family’s financial future, is rarely glamorous. It is mostly about turning up, doing the right thing in front of you, and trusting the plan even when no single day feels decisive. Those who appreciate history understand that history repeats, and that lessons from one domain can illuminate another. The principles of disciplined risk management, broad diversification, and patience are not financial inventions. They are something far older.

This Saturday, as you read this, spare a thought for the soldier who carried that flag home, and for the thousands who didn’t. Then, if you’re reviewing your portfolio, ask yourself whether it’s built like a campaign or like a gamble. Built like the former, it will, in time, give you and your family what those soldiers fought for, a chance at a stable and prosperous future.

Lest we forget.

Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References 

1.“A 5-Minute History of the Battle of El Alamein,” Imperial War Museums. https://www.iwm.org.uk/history/second-world-war/north-africa-campaign/history-of-battle-of-el-alamein

2. “The North African Campaign,” NZ History (Manatū Taonga, Ministry for Culture and Heritage). https://nzhistory.govt.nz/war/the-north-african-campaign

3. “The North African Campaign,” NZ History. https://nzhistory.govt.nz/war/the-north-african-campaign

4. “NZ Victoria Cross recipients,” NZ History. https://nzhistory.govt.nz/page/nz-victoria-cross-recipients

5. Whai Ngata, “Ngārimu, Te Moananui-a-Kiwa,” Dictionary of New Zealand Biography, Te Ara, The Encyclopedia of New Zealand. https://teara.govt.nz/en/biographies/5n9/ngarimu-te-moananui-a-kiwa

6. Saul David, Tunisgrad: Victory in Africa (William Collins, 2025).

7. Saul David, Tunisgrad: Victory in Africa (William Collins, 2025).

8. “Tunisia and victory,” NZ History. https://nzhistory.govt.nz/war/the-north-african-campaign/tunisia

9. “Richard Nugent O’Connor,” Encyclopædia Britannica. https://www.britannica.com/biography/Richard-Nugent-OConnor

10. Mercer, “2025 Table of Investment Returns.” https://www.mercerfinancialservices.co.nz/mercer-magazine/investments/2025-table-of-investment-returns.html

11. S&P Dow Jones Indices, “U.S. Persistence Scorecard, Year-End 2025.” Copy hosted by Aries Advisors. https://www.ariesadvisors.com/files/persistence-scorecard-year-end-2025.pdf

12. Brinson, Hood & Beebower, “Determinants of Portfolio Performance,” Financial Analysts Journal, 1986; Brinson, Singer & Beebower, “Determinants of Portfolio Performance II: An Update,” Financial Analysts Journal, 1991.
Until the Pips Squeak

Article #479

Squeezing the lemon

During the December 1918 election campaign, Sir Eric Geddes promised to squeeze Germany until you could hear the pips squeak [1]. Germany never paid anything like the bill. Squeezing is easy to promise. The juice is another matter.

More than half a century later Denis Healey borrowed the image. In Lincoln in February 1974, as Labour's shadow chancellor, he promised to squeeze property speculators until the pips squeaked. The press turned that into squeezing the rich, and the line has stood for the rich in general ever since [2].

Labour had committed itself to a wealth tax. Healey spent five years as Chancellor trying to design one. Looking back in 1989, he admitted he could not draft one that would raise enough revenue to be worth the administrative cost and the political hassle [3].

In the meantime Britain ran out of money. On 28 September 1976 Healey was at Heathrow, bound for the IMF annual meetings, when sterling slid. He turned back to the Treasury and announced that Britain would seek a record $3.9 billion loan. The Letter of Intent, signed on 15 December, committed the government to deep cuts in public spending [4][5].

The squeezer had become the squeezed. Within three years of promising to squeeze the speculators, the Chancellor was negotiating terms with Britain's creditors. It is worth remembering as New Zealand heads to the polls on 7 November.

What is on the table

The Green Party proposes a 2.5% annual tax on net assets above $10 million, covering property, shares and bonds, with the family home exempt. Alongside it sits a 33% capital acquisitions tax on inheritances and gifts worth more than $1 million, paid by the person receiving, with family homes and family farms exempt [6].

The revenue would fund a $10,000 tax-free threshold and a 45% top rate above $160,000, which the Greens say would cut tax for 96% of New Zealanders [6].

They are not alone. Te Pāti Māori want a targeted wealth tax on the wealthiest 3%, at 1.5% on net assets above $2 million, 2% above $5 million and 2.5% above $10 million [7]. Opportunity proposes an annual land tax of 1.75% on urban land and 0.5% on rural land [8]. Same instinct, different coat. Across the left, the reach is for a levy on what you hold rather than what you receive.

And here is the irony. Opportunity is the kingmaker in the latest 1News Verian poll, on 8%, so its plan is not idle talk [9]. Yet Gareth Morgan, who founded the party now called Opportunity, argued on 10 October that “Wealth taxes kill entrepreneurship” and called the tax plans of Labour, the Greens and now Opportunity regressive for New Zealand [10]. The man who once campaigned to rid the country of cats now seems keen to see off his own creation.

Who could deliver it

Before anyone panics, a reality check. National, ACT and NZ First oppose wealth, inheritance and comprehensive capital gains taxes [11]. Labour has ruled out a wealth or inheritance tax. Its own centrepiece is a 28% tax on gains from the sale of investment and commercial property, excluding the family home, applying only to gains made after 1 July 2027 [12].

Under MMP, the Green package could only arrive as the price of a coalition, and then only in whatever form the negotiation produces. Election night tells you the direction. The coalition talks tell you the substance.

A valuation is not cash

There is a hard truth under all of this. A wealth tax is levied on a valuation. It is paid in cash.

Take an owner with $20 million of net assets, most of it a business built over two generations. Under the Green rules the first $10 million is free. The second $10 million attracts 2.5%. That is $250,000 a year, every year, due whether the business had a record year or a bad one. The business does not pay it. The owner does, from income already taxed, from borrowing, or from selling a slice of the thing that employs people.

A lower threshold bites harder. Take a family company worth $14 million, with the family home left out. The Greens tax the $4 million above their line, which is $100,000 a year. On Te Pāti Māori's published tiers, treating each band as a marginal rate, the same company faces about $245,000 a year. Their published summary leaves open whether the family home counts towards the $2 million base.

Then someone has to value it. Listed shares are easy. So, mostly, are an orchard or a commercial building in Hastings, because a valuer can work from recent sales. A private trading company is not. Nor is a minority shareholding in a family business or a partnership interest. Every annual valuation is an argument with Inland Revenue waiting to happen.

As the old line goes, you may call a cat a fish, but it can’t swim. You may call a valuation wealth, but it can’t pay the bill.

The Greens’ own costings assume 28.5% of the super-rich tax is never collected, lost to avoidance and minimisation, on advice from the Parliamentary Library informed by Treasury [13]. When the people designing a tax concede that more than a quarter leaks away before it starts, the rest of the brochure is a wish.

The proposed inheritance tax has the same flaw in a different coat. Because the person receiving pays, a son or daughter who inherits a $3 million share of a family business could face a bill in the hundreds of thousands of dollars. The asset does not come with that cash attached.

The scoreboard

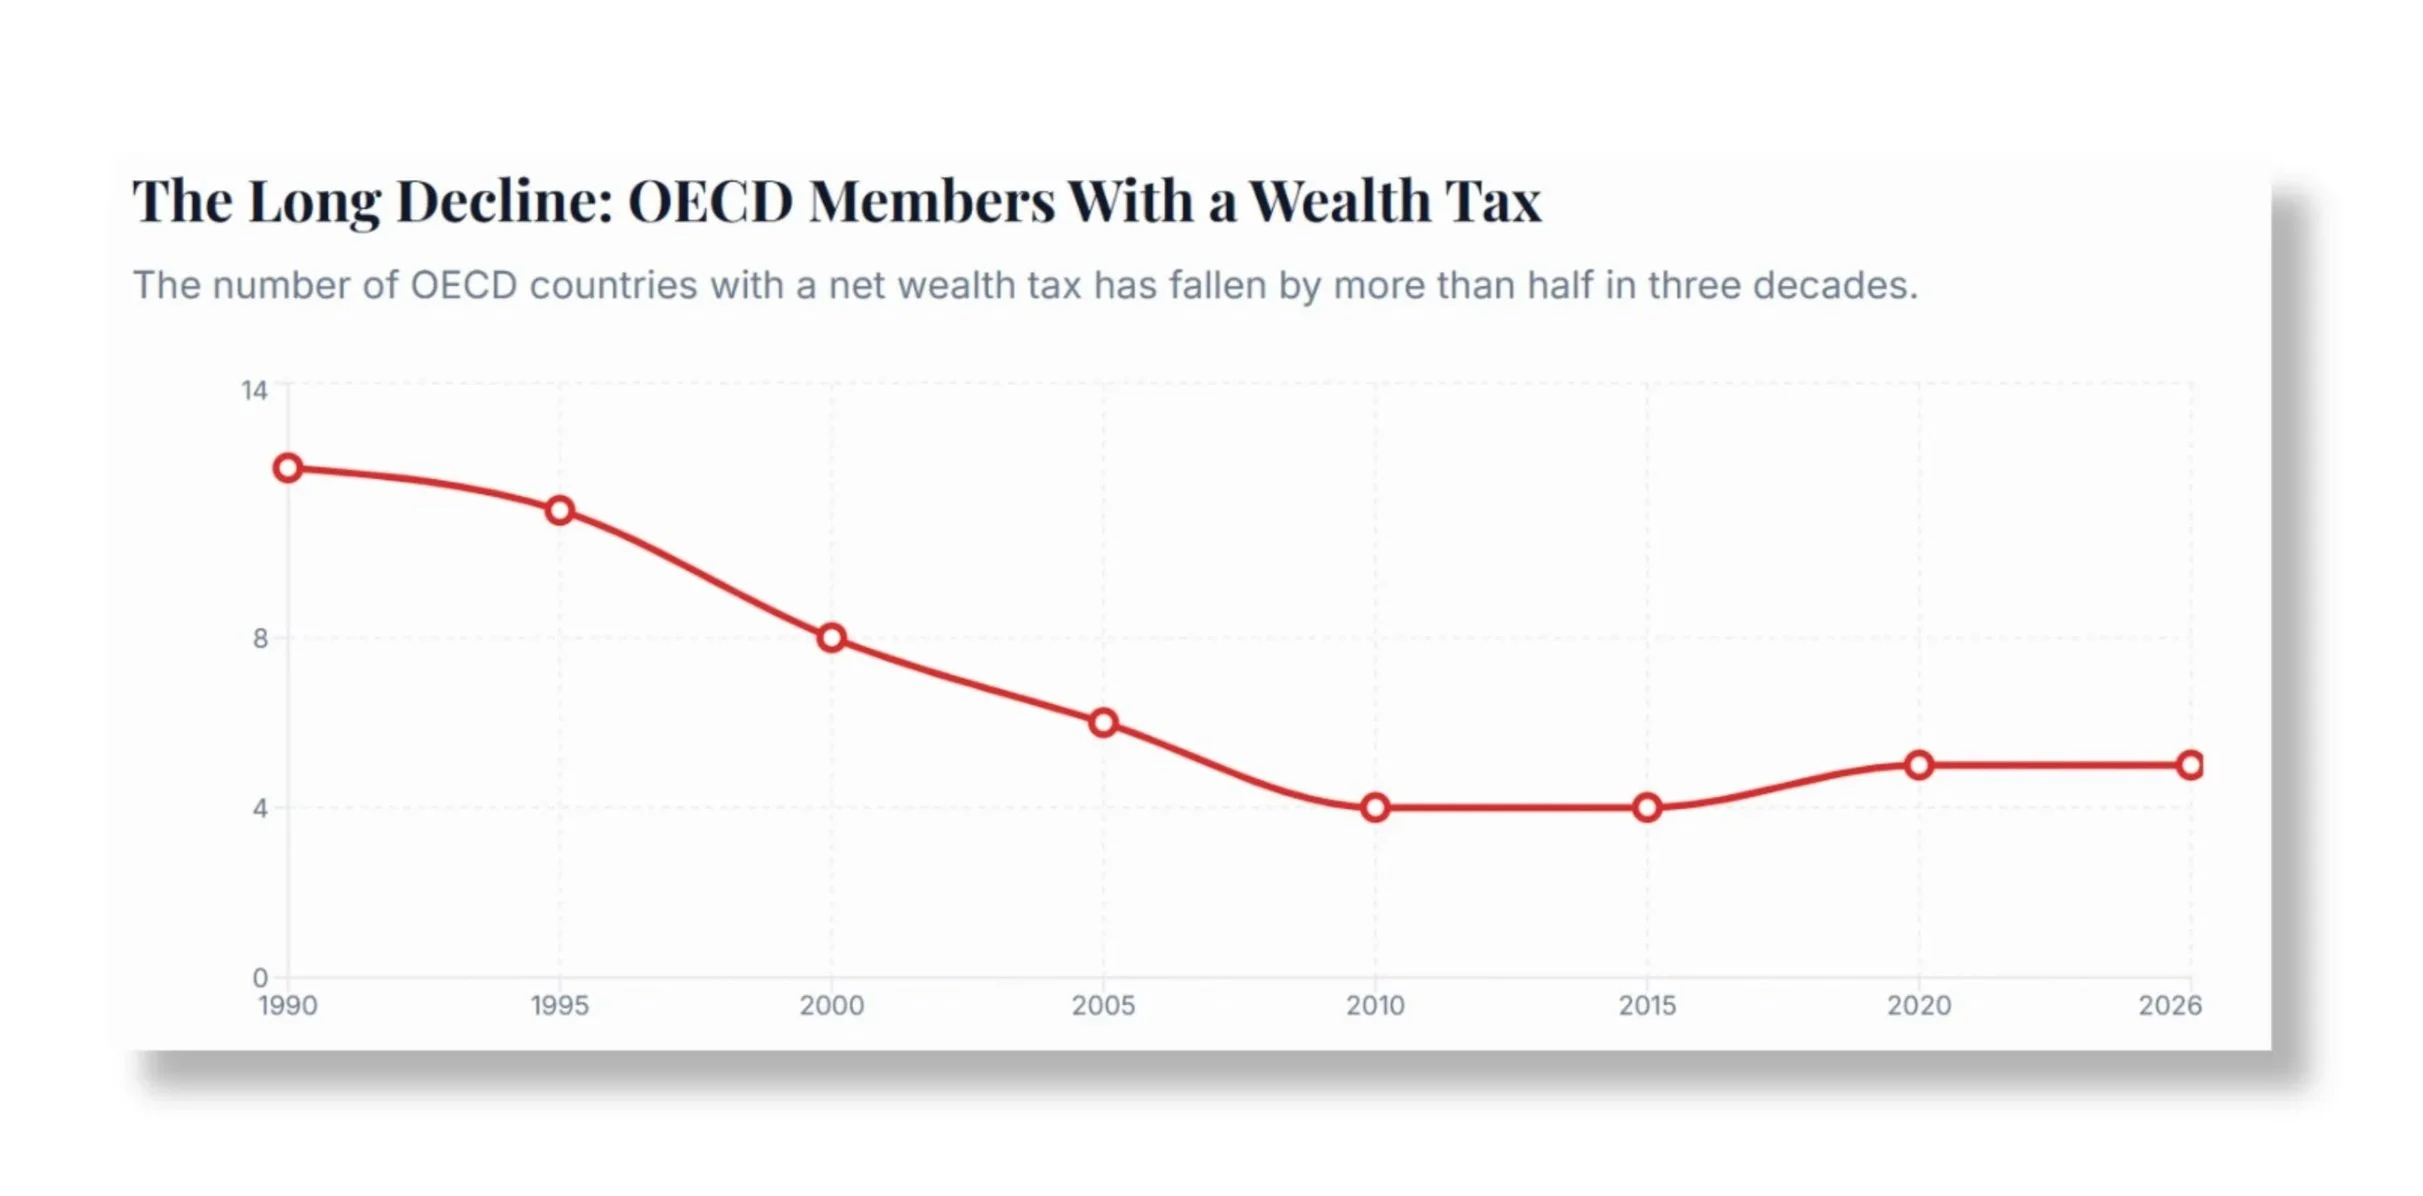
The OECD found 12 member countries had a net wealth tax in 1990 and only four by 2017. Repeals were usually justified on efficiency and administrative grounds, and the taxes often failed to meet their redistributive goals [14].

Norway is the case study everyone reaches for. In 2022 a rise took its top combined rate to 1.1%. That year more than 30 billionaires and multimillionaires left, according to Dagens Næringsliv [15]. Capital has legs. Its owners have passports.

The Netherlands has just learned the same lesson the quick way. In February the lower house passed a law taxing the annual rise in value of shares, bonds and crypto at 36%, whether or not anything was sold. A petition gathered more than 61,000 signatures and coalition senators preferred a tax on sale. The cabinet has now proposed taxing shares and bonds only when they are sold, from 1 January 2028 [16]. Tax the cash, not the valuation.

Source: Regen-Fin

The grain of truth

The counter-case deserves a fair hearing.

New Zealand has no general capital gains tax and no inheritance tax [11]. A salary earner pays tax on every dollar from the first. A long-term property or share investor can see large gains taxed lightly or not at all. That is a genuine gap, and these parties are at least trying to fill it with a number rather than a slogan. The OECD itself accepts that where capital is lightly taxed, or inheritances are not taxed, a net wealth tax may play a substitution role [14].

The administration case is not all one way either. Research in Fiscal Studies puts the central cost of running a well-designed UK wealth tax at about 0.1% of taxable wealth for taxpayers and 0.05% for the tax authority [3]. That counts the cost of collecting the tax, not the cost to the owner of finding the cash.

But a wealth tax is the hardest tool for that job. A capital gains tax is levied when cash changes hands. Even Labour's narrower version bites only on sale. A wealth tax is levied when it does not. It taxes the paper, year after year, and leaves the owner to find the money.

Whose interest is being served

For families, the practical question is not who you vote for. It is whether your structure works under more than one government.

Who holds what. How it would be valued, and by whom. Where the cash would come from in a lean year. Whether the succession plan still works if a 33% tax falls on the next generation. Whether a trust settled decades ago still serves the people it was meant to.

Do not restructure in a panic for a policy that may never pass. But do know your position, your structures and your succession plan before election night hands the file to a coalition room. Those are planning questions, and they are better answered calmly before a policy lands than in a rush after it.

Healey learned the lesson over five years. The pips squeaked, but it was the Treasury that ran out of juice. Grow the pie first, then argue about the slice.

Position for your goals, not for a caucus vote. When the noise gets loud, seek advice and wise counsel.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References 

1. Langworth, R. (2014). Squeeze Germany until the pips squeak. Churchill Project, richardlangworth.com. On Sir Eric Geddes, First Lord of the Admiralty, and the 1918 election. The Cambridge speech of December 1918 is recorded at phrases.org.uk.
2. Healey, D. Speech at Lincoln, 18 February 1974, reported in The Times, 19 February 1974 (as quoted in Wikiquote: Denis Healey). Often misreported as “tax the rich until the pips squeak”. See also LabourList (October 2015), 10 of the best Denis Healey quotes.

3. Burgherr, D. (2021). The costs of administering a wealth tax. Fiscal Studies, 42(3-4), 677-697 (quoting Denis Healey, 1989). https://doi.org/10.1111/1475-5890.12276

4. Pickford, S. (9 December 2016). Britain’s big bailout, December 15, 1976. The World Today, Chatham House.

5. OMFIF (28 September 2016). When Britain went bust. https://www.omfif.org/2016/09/when-britain-went-bust/

6. 1News (21 June 2026). Greens propose wealth, inheritance taxes to fund income tax changes. https://www.1news.co.nz/2026/06/21/greens-propose-wealth-and-inheritance-taxes-to-fund-income-tax-changes/

7. 1News (26 August 2026). Te Pāti Māori launches new tax policy, says most would pay less. https://www.1news.co.nz/2026/08/26/te-pati-maori-launches-new-tax-policy-says-most-would-pay-less/ and Deloitte New Zealand (September 2026). Election tax policies, part three.

8. Opportunity Party (May 2026). Tax Reset policy. https://cdn.opportunity.org.nz/documents/policy/Opportunity%20Policy%20-%20Tax%20Reset.pdf, and 1News (30 June 2026). Explainer: What are the Opportunity Party’s policies? https://www.1news.co.nz/2026/06/30/explainer-what-are-the-opportunity-partys-policies/

9. 1News (13 October 2026). Poll: Hipkins and Luxon now neck and neck, Opportunity on track for 10 MPs. https://www.1news.co.nz/2026/10/13/poll-hipkins-and-luxon-now-neck-and-neck-opportunity-on-track-for-10-mps/

10. Morgan, G. (10 October 2026). Opportunity’s tax plan joins Labour, Greens as regressive for NZ. Newsroom. https://newsroom.co.nz/2026/10/10/gareth-morgan-opportunitys-tax-plan-joins-labour-greens-as-regressive-for-nz/

11. KPMG New Zealand (August 2026). Election 2026 party tax policies tracker (updated to 6 August 2026), and Grant Thornton New Zealand (2026). Tax policy at the crossroads: growth, simplicity and redistribution in Election 2026.

12. Deloitte New Zealand (August 2026). Election tax policies, part two (Tax Alert), and interest.co.nz (June 2026). Labour finance spokesperson Barbara Edmonds says the only tax policy Labour will campaign on is its capital gains tax.

13. interest.co.nz (2026). Natalia Albert says finally the Green Party has mostly got its tax policy right (28.5% of the super-rich tax assumed uncollected, on Parliamentary Library advice informed by Treasury). https://www.interest.co.nz/public-policy/139129/natalia-albert-says-finally-green-party-has-mostly-got-its-tax-policy-right

14. OECD (2018). The Role and Design of Net Wealth Taxes in the OECD. OECD Tax Policy Studies No. 26. OECD Publishing, Paris.

15. IFC Review (April 2023). Europe’s super-rich abandoning Norway at record rate as wealth tax rises slightly (citing Dagens Næringsliv).

16. IMI Daily (16 September 2026). Netherlands retreats from 36% unrealized gains tax, will propose sale-based model instead; and DutchNews.nl (30 September 2026). The box 3 tax changes: what they are and what they mean for you.

Betting on the Wrong Team

Article #478

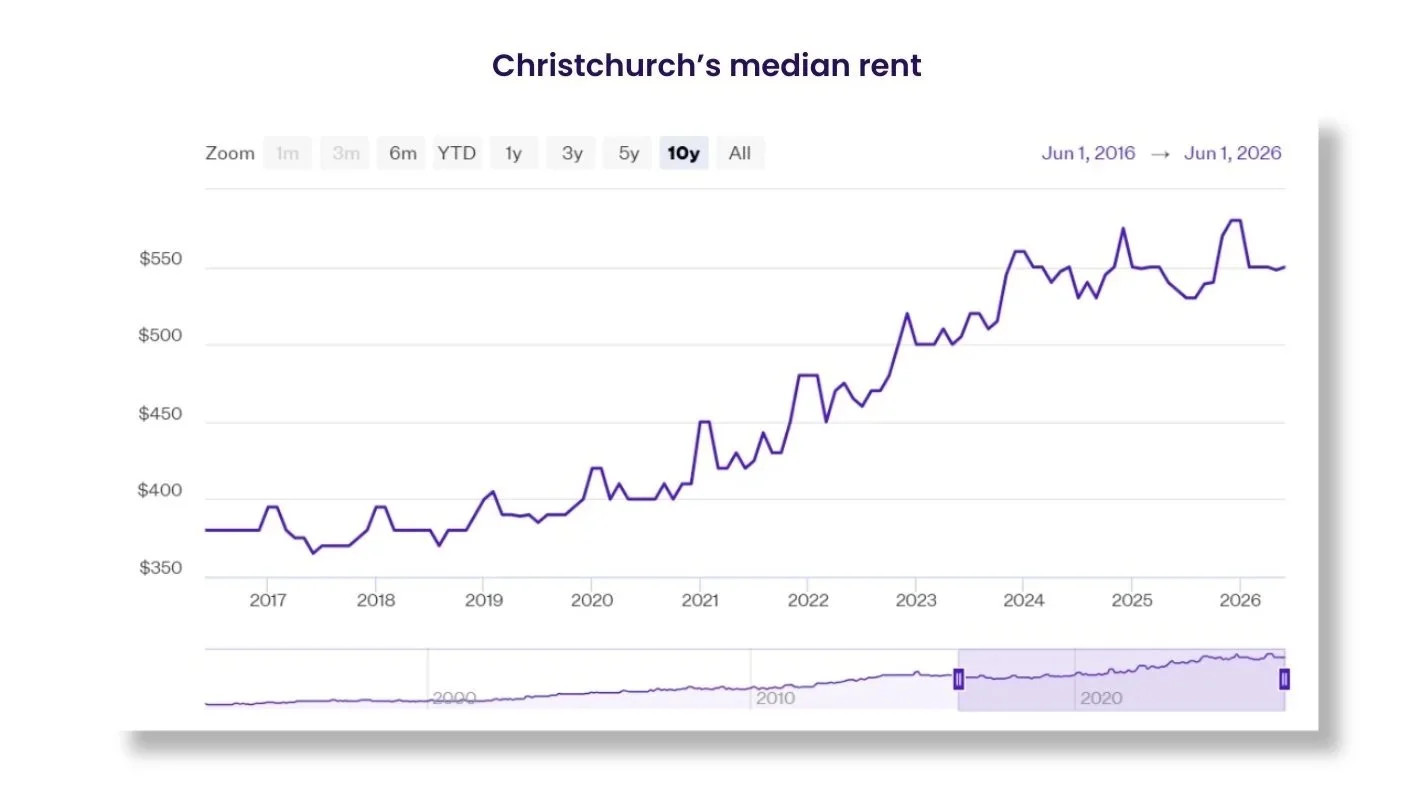
Buying in Christchurch because you can't afford Auckland sounds like a canny move. But renting where you live while your investment sits somewhere else carries a risk most people never properly account for.

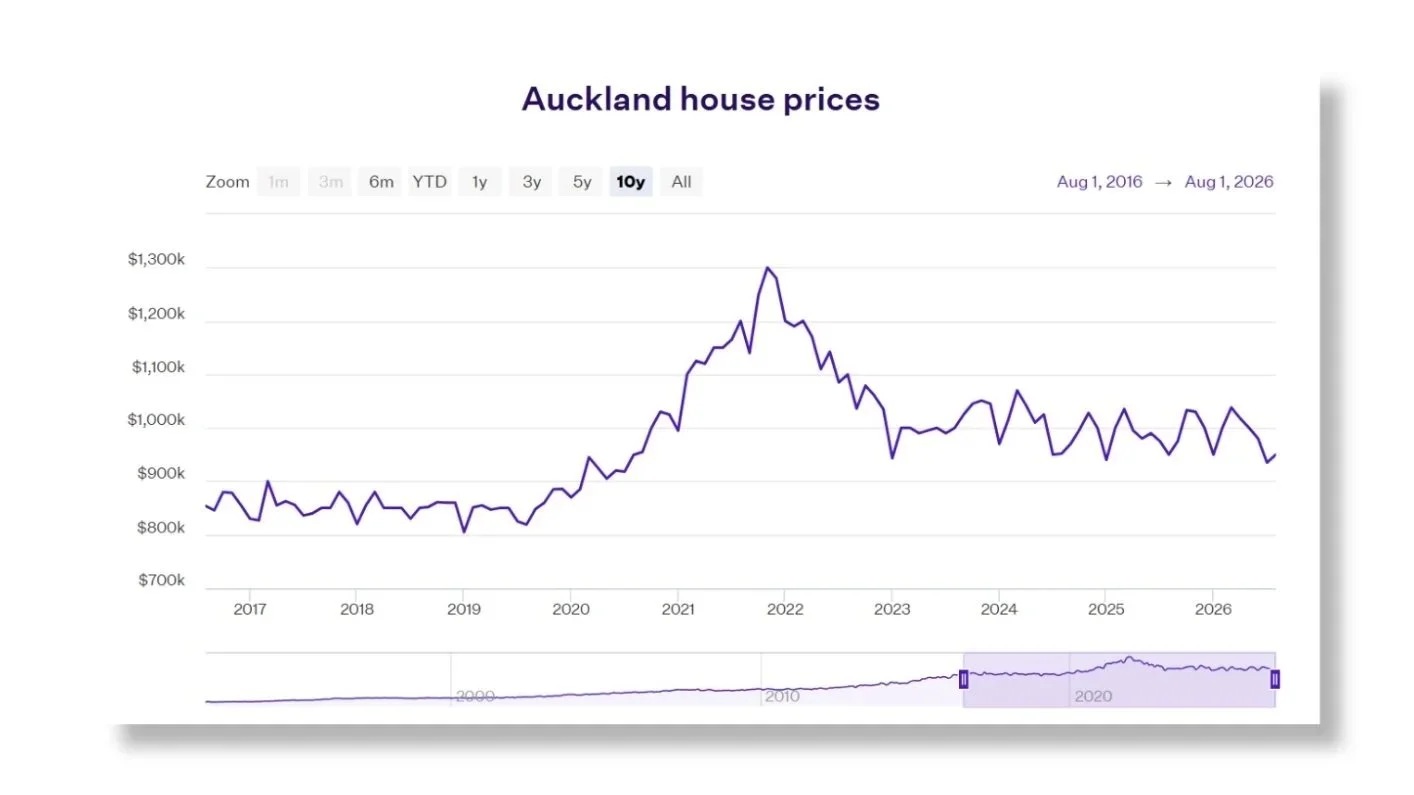
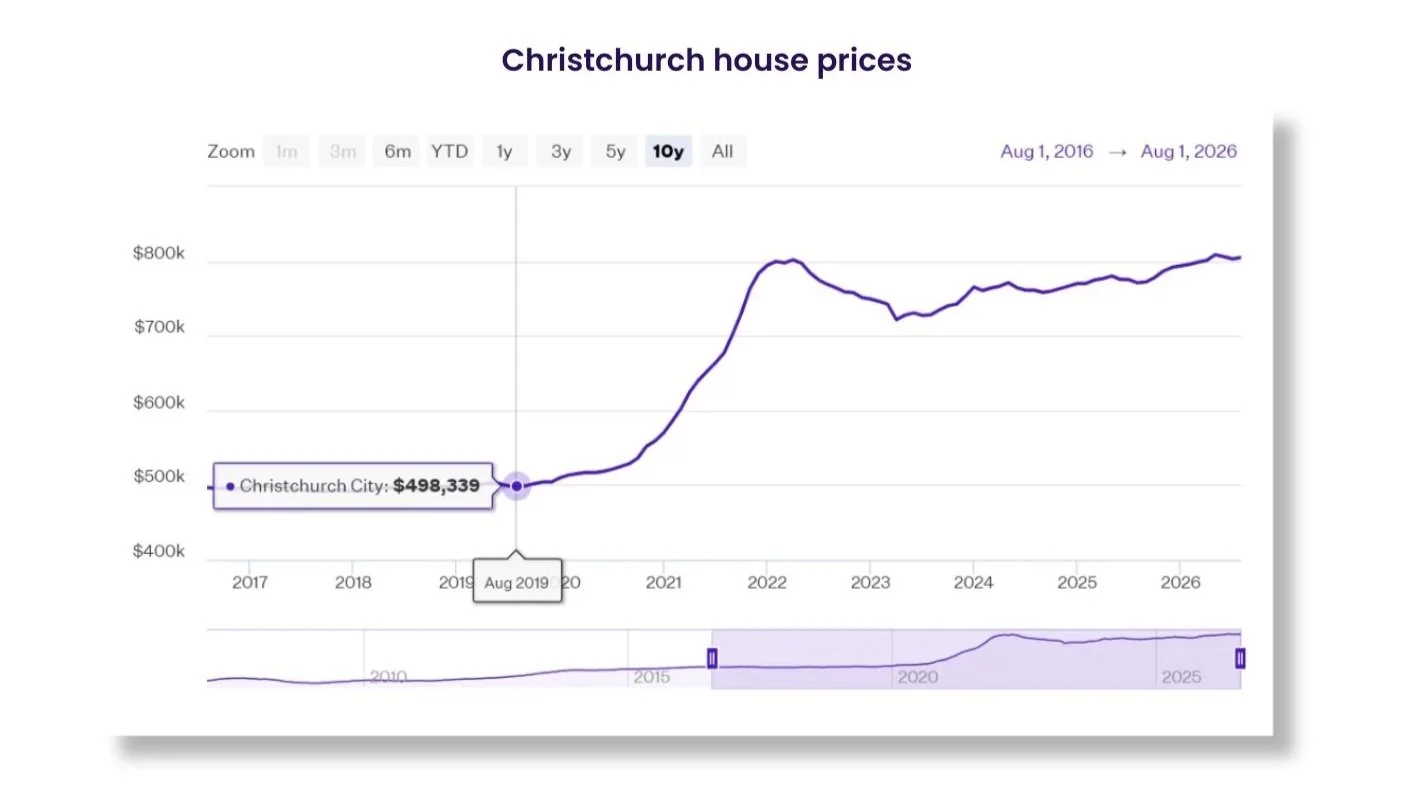
The logic is seductive, and on the surface it looks almost elegant. You live in Auckland. You want to get into the property market. The Auckland median house price currently sits at $950,000 [1], a figure that has made entry feel like a cruel joke for first-time buyers for years. But Christchurch? Christchurch you can manage. The average Christchurch property value is $804,850 as of August 2026 [2] — a meaningful gap. So you buy there, tenant it out to cover the mortgage, and rent yourself in Auckland. Rentvesting, they call it, and the strategy has a growing number of advocates.

The trouble is, a surprising number of people who adopt it are making a subtler mistake than they realise. They think they are hedging their exposure to the property market. They are not. They are placing two separate bets, and one of them is quietly working against them.

Source: Opes Partners

Source: Opes Partners

The wrong side of the TAB

With the Bledisloe Cup kicking off at Eden Park this weekend, the TAB odds tell an interesting story: All Blacks at $1.22, the Wallabies at $4.00 [3]. The ABs are overwhelming favourites and almost unbackable; you'd need to stake nearly five dollars just to make one. So you eye the Wallabies instead. Both tier one nations. Same corner of the world, same game, broadly similar talent. The Wallabies have been improving. At $4.00, they start to look tempting. The potential payoff is larger, the narrative is compelling, and it feels like genuine value, a smart contrarian bet on a credible alternative.

But rugby doesn't do partial results. One team wins, one team loses. There is no credit for geographic proximity, no points for picking the right hemisphere. If the All Blacks win and you backed the Wallabies, you have not hedged anything. You have simply lost.

Property works the same way. As an Auckland renter, rising prices hurt you directly: every time the market runs, the gap between what you can afford and what you need widens. Your Christchurch investment is not tracking that exposure. It runs on its own fundamentals: a different local economy, different employer base, different migration pressures, and the long-unfolding story of the post-earthquake rebuild.

Source: Opes Partners

The correlation problem

In investment terms, a hedge only works if the two positions are genuinely correlated. Auckland and Christchurch property are not that. Median Auckland values are down 26.9% from their peak, while Christchurch is down 1.32% and has been edging upward [1,2]. The two markets are moving on different timetables, driven by different forces. The correlation between them is low enough that owning one does not reliably protect you against the other; both can work against you simultaneously.

Over the past two decades, Auckland has experienced extraordinary price appreciation driven by supply constraints, population growth, and land scarcity that simply do not apply in Christchurch. The Canterbury rebuild added significant housing stock to the city. The dynamics are different. The risk profile is different. Buying one as a proxy for the other is, at best, a partial solution and, at worst, a false sense of security.

The real cost of remote landlording

Being a landlord costs more than being an owner-occupier. Significantly more. And doing it from another city costs more still. Property management fees typically run at eight to ten percent of rental income before letting fees, which can add another week or two of rent each time a tenant turns over [4]. A leaking tap in your own home costs you an hour. The same tap in a Christchurch rental managed from Auckland costs a callout fee, a plumber's rate, and a property manager's coordination time.

Add landlord insurance, rates, body corporate levies if applicable, and the compliance obligations under the Healthy Homes Standards [5]. Meeting insulation, heating, and ventilation requirements in older rental stock can run to several thousand dollars. These are not optional, and they are not cheap.

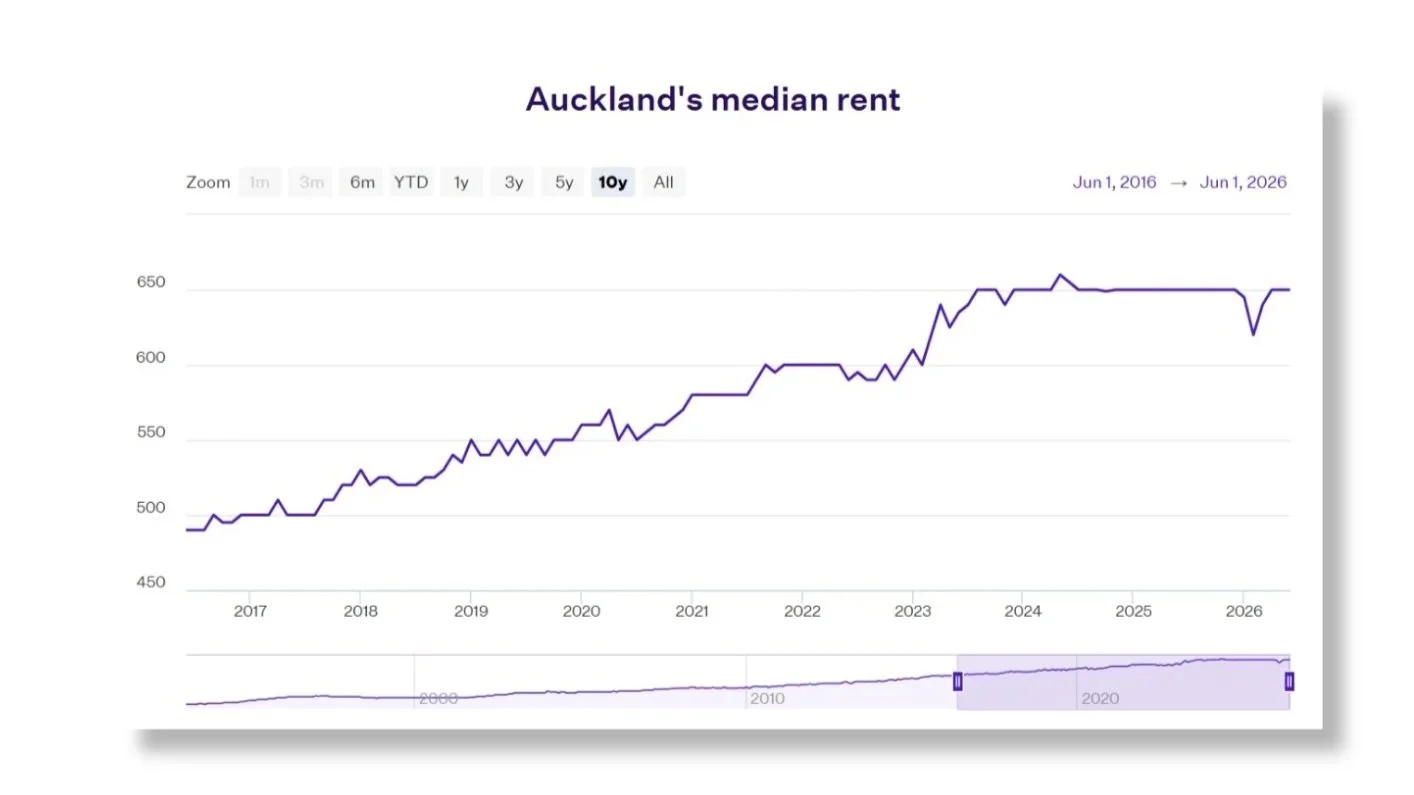
Then there is the tax asymmetry that catches many people off guard. Net rental income is taxable at your marginal rate [6]. The rent you pay in Auckland is not deductible in any form; it comes straight out of after-tax dollars. The average weekly rent is $650 in Auckland and $550 in Christchurch [1,2]. The real comparison is not $550 received versus $650 paid. It is $550 received, less expenses and tax, versus $650 paid from net income with no relief whatsoever. That gap is wider than most spreadsheets suggest.

Vacancy is the silent killer. Every week the property sits empty, the mortgage runs without the rent. From Auckland you cannot simply drive past, tidy the garden, and get it listed. You wait. Your property manager moves at their pace, not yours.

The risk nobody puts in the plan

The most underappreciated risk is personal circumstance, and the risk nobody likes to plan for. Life changes. Relationships shift. Jobs move. Children arrive and schooling zones start to matter. When the day comes that you need to own the roof over your head, you will be selling a Christchurch asset into whatever market conditions exist at that moment, then trying to buy into an Auckland market that has been doing its own thing for years. The timing is entirely outside your control.

None of this means rentvesting is a bad idea. For some people, in some situations, it remains a perfectly sensible first step onto the ladder; better to build equity somewhere than nowhere. But it should be entered as what it actually is: an investment position with real, specific, and knowable risks. Not a clever workaround that sidesteps the hard questions.

The property market does not reward good intentions. It rewards good planning. And good planning starts with being honest about which team you are actually backing, and whether the odds genuinely make sense for the result you need.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References 

  1. Opes Partners, Auckland Property Market (2026): Average House Prices, 16 September 2026. https://www.opespartners.co.nz/property-markets/auckland

  2. Opes Partners, Christchurch Property Market (2026): Average House Prices, 22 September 2026. https://www.opespartners.co.nz/property-markets/canterbury/christchurch

  3. TAB New Zealand, Bledisloe Cup match odds.

  4. RentManager, How Much Do Property Managers Charge in NZ? (2026 Fee Breakdown), updated 14 August 2026. https://rentmanager.nz/blog/how-much-do-property-managers-charge-nz

  5. Tenancy Services, Healthy homes compliance. https://www.tenancy.govt.nz/healthy-homes/healthy-homes-compliance/

  6. Inland Revenue, Pay tax on your rental income, updated 1 April 2026. https://www.ird.govt.nz/property/renting-out-residential-property/residential-rental-income-and-paying-tax-on-it/pay-tax-on-your-rental-income

The Prison of the Middle Class

Article #477

A lazy shorthand dominates every cost-of-living conversation here: the haves and the have-nots. Two boxes, a line down the middle, a moral position attached to each. It survives because it is easy, not because it is true. 

Mark Carney put it plainly: if you are not at the table, you are on the menu [1]. The households carrying the weight of this are the least represented in the argument about it. 

Some have-nots have far more than others. Some haves are one interest rate reset from the wrong side of the ledger. The surface tells you little. The four-wheel drive is a liability with a registration plate. The holiday home is a security instrument with a view. Wealth, for many New Zealanders, is illusory: a number on a valuation notice that funds nothing but demands payment every month. 

The people trapped by that illusion are not the poorest New Zealanders. They are the battlers; around 1,200,000 households on Pita Alexander's count, roughly 58 percent of the country's 2,072,000 households [2]. 

The arithmetic of the squeeze 

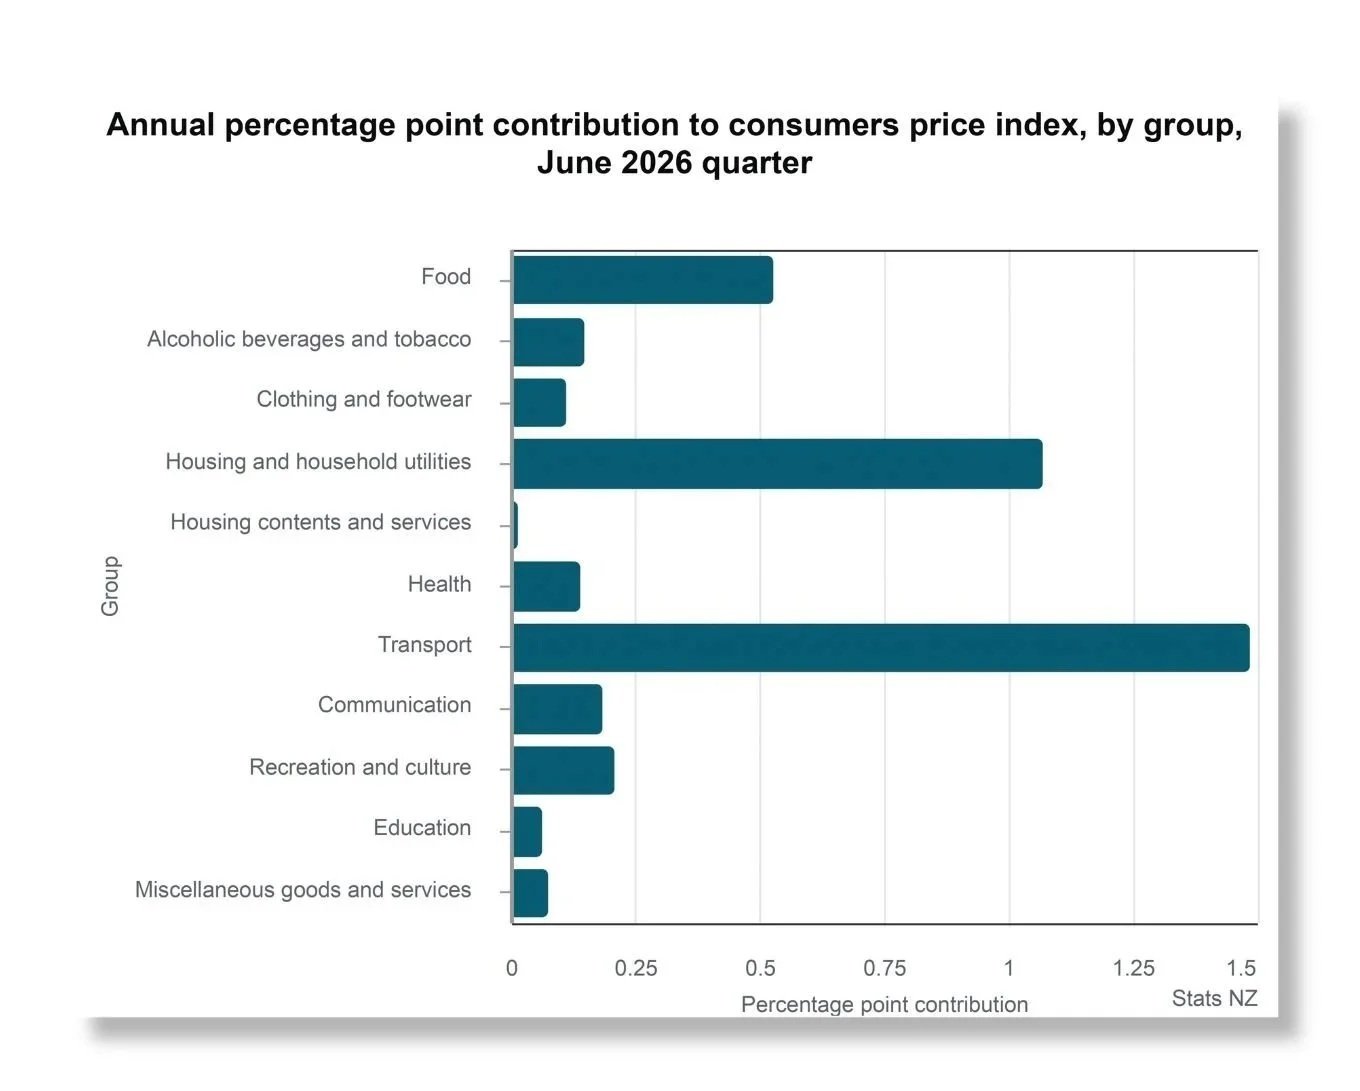
Take a Hastings household on two incomes, two cars and a mortgage. Run the last twelve months across it. Petrol up 27.5 percent. Tertiary education up 22.6 percent. Electricity up 12.0 percent. A GP visit up 10.3 percent [3]. 

Then add the line no minister has to sign. The average proposed council rates rise for 2026/27 is 6.9 percent, against annual inflation of 4.1 percent [4]. Petrol was the largest single contributor to that 4.1 percent [3]. Rates were the quiet one, up 34.4 percent across the last three-year council term while general inflation ran at 13.7 percent [5]. 

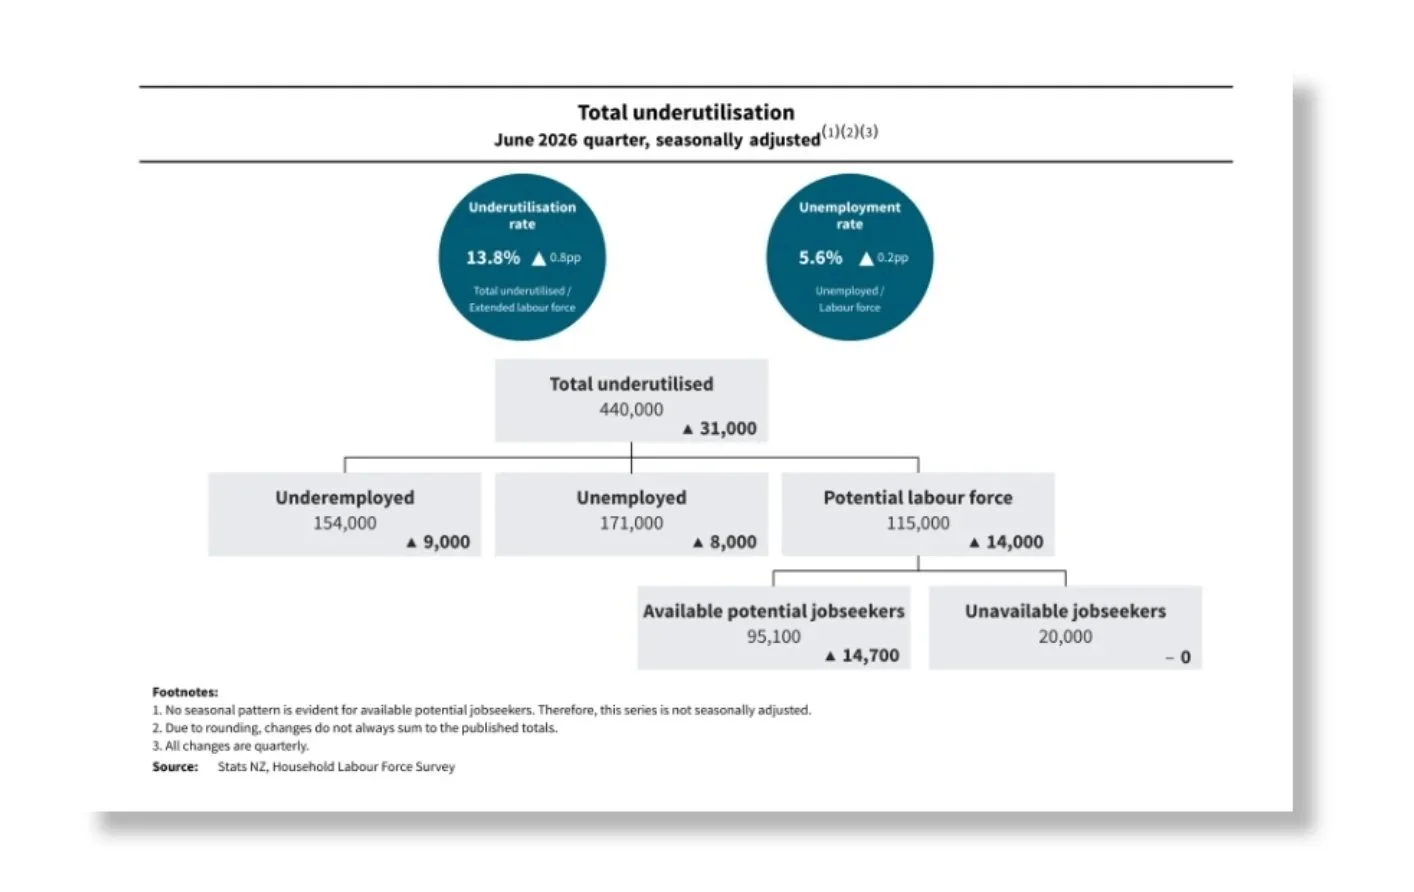
At $1.25 per kilometre on a full running-cost rate, those two cars eat $19,500 a year [2]. Before the mortgage. Unemployment has reached 5.6 percent, the highest since 2015, with underutilisation at 13.8 percent [6]. Both adults still work, both cars move, and the 3 percent pay rise was gone before it arrived. On those two Hastings incomes the surplus this year is a few hundred dollars, if the hot water cylinder holds. That is not a lifestyle. It is the hire that does not happen. 

None of this is attitude. When Rotorua business owners told the Prime Minister they could not pass their costs on, he called the framing negative and said the country had a parent-child mentality. He apologised days later. The apology was the right instinct; the original answer treated arithmetic as mindset [7]. 

The evidence is in the withdrawals 

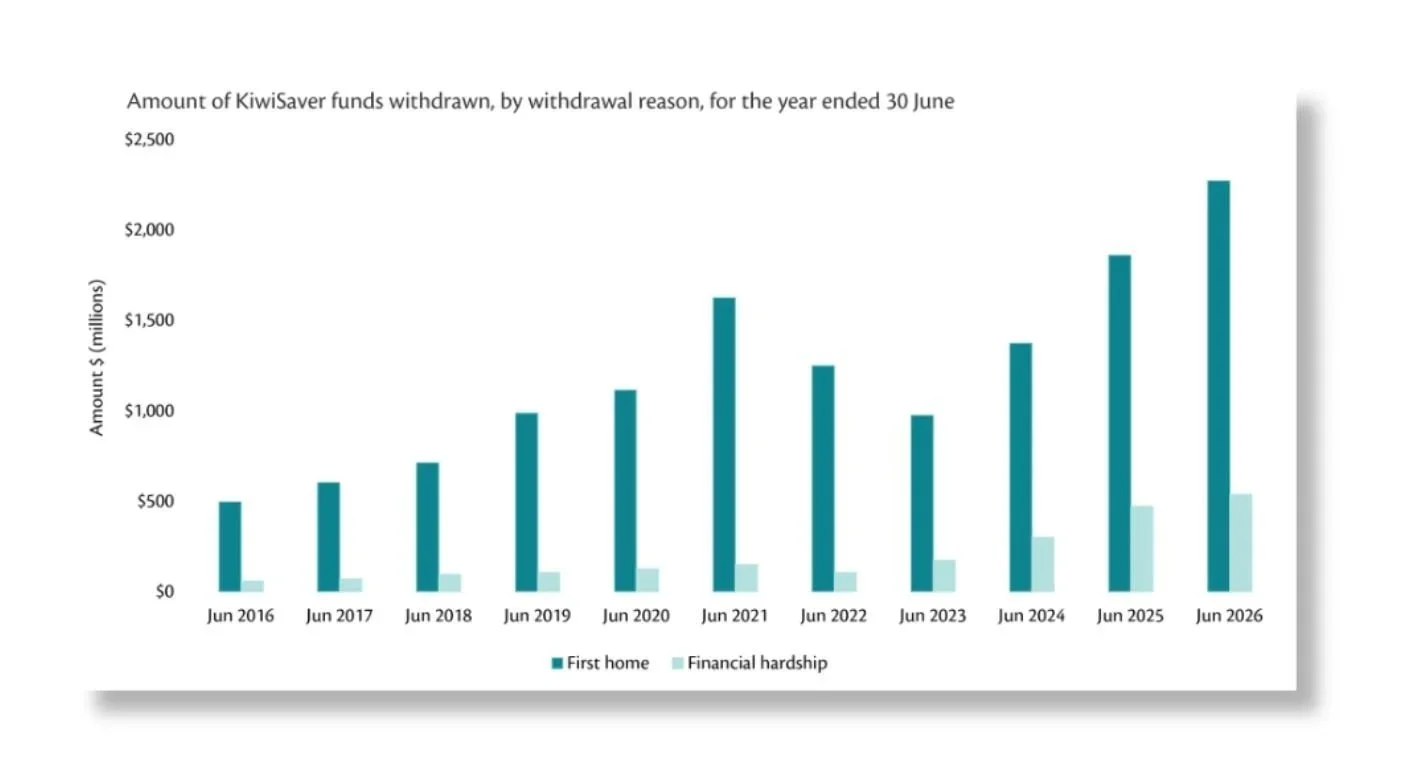
Ignore the rhetoric; look at what people do with their savings. KiwiSaver hardship applications doubled in two years, passing 58,000 in 2025, and are running higher again in 2026. Inland Revenue paid out $471.2 million on hardship grounds in the June 2025 year [8] [9]. These are not people gaming a system. They are breaking open the last jar in the house. 

Source: Inland Revenue

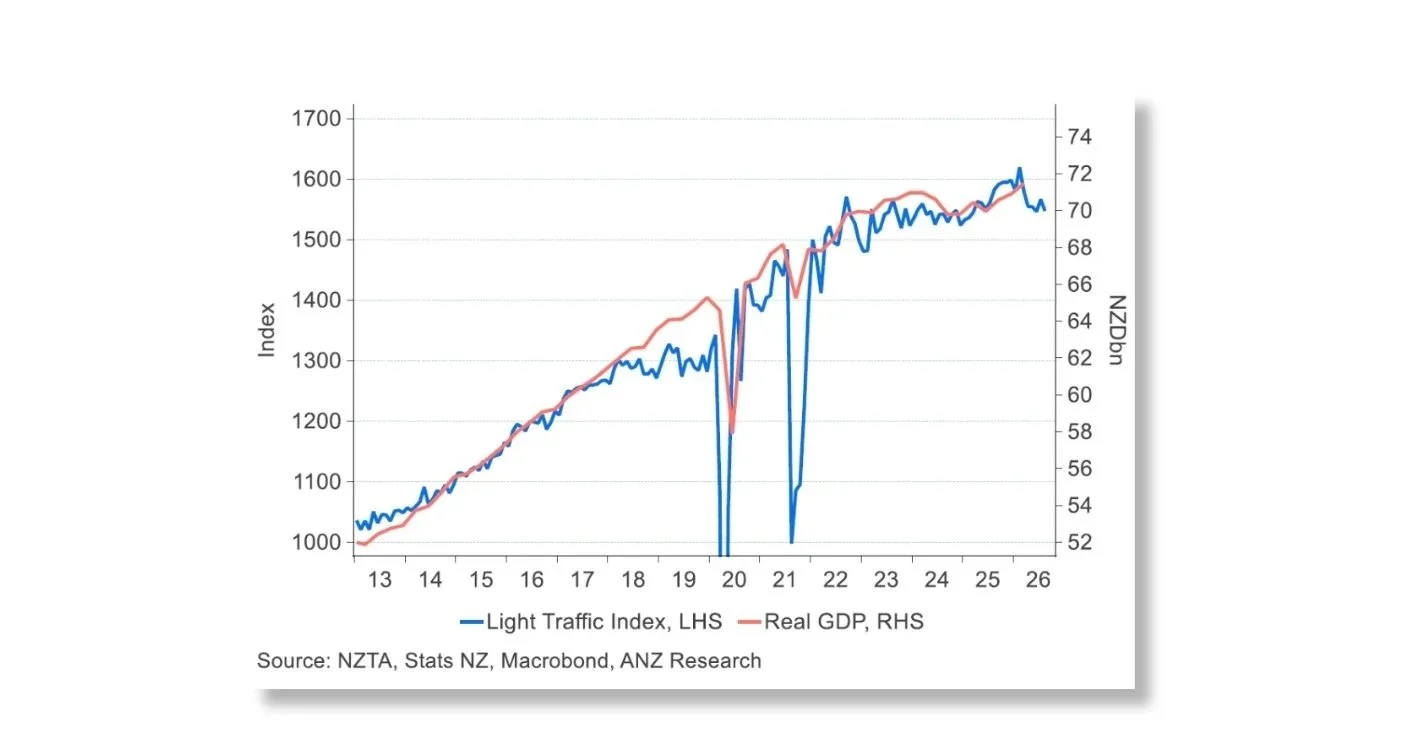
ANZ's Truckometer says the same in another language: light traffic sits below a year ago, because fewer of us drive to work [10]. Sixty thousand applications in a year is structural failure, one family at a time. 

Source: NZTA, Stats NZ, Macrobond and ANZ Research

What actually lifts a country 

Our best resource sits under our feet. We have an extraordinary climate and exceptional soils, and through every hard period, it is what we grow and sell abroad that sees us right. On the East Coast that comes with a payroll. Take the orchard contractor running four utes through the apple season. His fuel is up more than a quarter, his rates too. What his growers can pay him has not moved. In a normal February he would take on an extra picker. This year he runs the crew short and works the weekends himself. That wage is never offered, never spent in a Hastings shop, never taxed. Regulation that adds a form, a fee or a delay to that operation is not neutral. It comes out of the same ledger. 

A healthy, aspirational middle class is not a nice-to-have in a growth economy. It is the engine. Aspiration requires surplus. Strip the surplus away and you do not get a poorer middle class, you get a stationary one: households that stop taking risks, stop hiring, and optimise for survival. That is a prison, and it has no obvious bars. 

Run the Hastings household forward six years. KiwiSaver contributions drop to the minimum, to keep the mortgage current, and never go back up. Buying a rental remains a conversation. The contractor never hires the extra picker, and the business his daughter was meant to take over is still his. No single year looks like failure, but together they make a household that stopped moving. 

History is blunt on this point. Rome ran on its smallholding farmers. They owned a few acres, paid their way, and filled the legions. Then the wars grew longer. Men were away for years, debts mounted, and the great estates bought the land behind them. Rome kept its wealth. It lost its middle. The century that followed was not a happy one. 

No nation announces the moment its middle class stops moving upward. It finds, a generation later, that something load bearing has gone. 

Look abroad and the pattern holds. Two decades ago, Poland’s income per head was a third of Britain's. It is now about 87 percent of it on a purchasing power basis and projected to draw level around 2030 [11]. Britain did not choose that; it simply let the squeeze run. We are not Britain yet, but the mechanism that took it there is the one running here now. 

Where this is heading 

Very little suggests relief. Both major parties are working at the fringes. 

The Reserve Bank lifted the official cash rate to 2.75 percent on 2 September, a second consecutive rise, and has said it may need to go further this year [12]. For a household already one reset from the wrong side of the ledger, that is not a forecast. It is a repayment. A rates cap begins its transition on 1 January 2027, after the election [13]. Pita Alexander puts the Crown $10 to $12 billion short of fiscal income and reckons that group needs about $4,000 a year more, $2,800 after tax, to restore a buffer [2]. Neither is on offer. 

The battlers are not asking to be rescued. They are asking for the arithmetic to work again. 

The arithmetic from Wellington is not yours to change. The arithmetic at your kitchen table is. Know those numbers as precisely as you would demand of a council to know its own, and get a clear-eyed view of a position a valuation notice will flatter, and a mortgage statement will not. Take good counsel on it. 


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References 

[1] Prime Minister of Canada. (2026, January 20). "Principled and pragmatic: Canada's path" Prime Minister Carney addresses the World Economic Forum Annual Meeting. https://www.pm.gc.ca/en/news/speeches/2026/01/20/principled-and-pragmatic-canadas-path-prime-minister-carney-addresses  

[2] Alexander, P. "The Cost of Living is a Core Problem in New Zealand". Pita's Perspective, 6 August 2026. 

[3] Stats NZ. Consumers price index: June 2026 quarter. 21 July 2026. https://www.stats.govt.nz/information-releases/consumers-price-index-june-2026-quarter/.  

[4] New Zealand Taxpayers' Union. Rates Dashboard 2026. 9 July 2026. https://www.taxpayers.org.nz/rates2026. 

[5] New Zealand Taxpayers' Union. “2025 Rates Dashboard Exposes Out of Control Rates Burden”. 14 July 2025. https://www.taxpayers.org.nz/2025_rates_dashboard_exposes_rates_burden. 

[6] Stats NZ. Labour Market Statistics: June 2026 quarter. 5 August 2026. 

[7] Moir, Jo. “Prime Minister Christopher Luxon's ‘parent-child mentality’ description of NZ businesses ‘valid’ in some cases: Seymour”. RNZ, 2 August 2026. https://www.rnz.co.nz/news/politics/858368/prime-minister-christopher-luxon-s-parent-child-mentality-description-of-nz-businesses-valid-in-some-cases-seymour. RNZ. “Watch: PM Christopher Luxon apologises for ‘parent-child mentality’ comments”. 3 August 2026. https://www.rnz.co.nz/news/politics/874803/watch-pm-christopher-luxon-apologises-for-parent-child-mentality-comments  

[8] Inland Revenue. Statistics on KiwiSaver funds withdrawn, by amount. Updated 24 August 2026. https://www.ird.govt.nz/about-us/tax-statistics/kiwisaver/withdrawals/amount. 

[9] Edmunds, Susan. “Exhaust other options first, withdrawing KiwiSavers told”. RNZ, 25 June 2026. https://www.rnz.co.nz/news/business/620439/exhaust-other-options-first-withdrawing-kiwisavers-told. 

[10] ANZ Research. ANZ Truckometer: August 2026 data. 10 September 2026. https://www.anz.co.nz/content/dam/anzconz/documents/economics-and-market-research/2026/ANZ-Truckometer-20260910.pdf. 

[11] International Monetary Fund. World Economic Outlook Database, April 2026: GDP per capita, current prices, purchasing power parity. https://www.imf.org/external/datamapper/PPPPC@WEO. 

[12] Reserve Bank of New Zealand. Monetary Policy Statement September 2026. 2 September 2026. https://www.rbnz.govt.nz/monetary-policy/monetary-policy-statement/monetary-policy-statement-filtered-listing-page/2026/sep-0209/monetary-policy-statement-september-2026. 

[13] New Zealand Government. “Government to cap rates”. 25 August 2026. https://www.beehive.govt.nz/release/government-cap-rates. New Zealand Government. “Rates Capping Bill passes first reading”. 1 September 2026. https://www.beehive.govt.nz/release/rates-capping-bill-passes-first-reading. 

What a Chilean coin knows about breaking up the supermarkets

Article #476

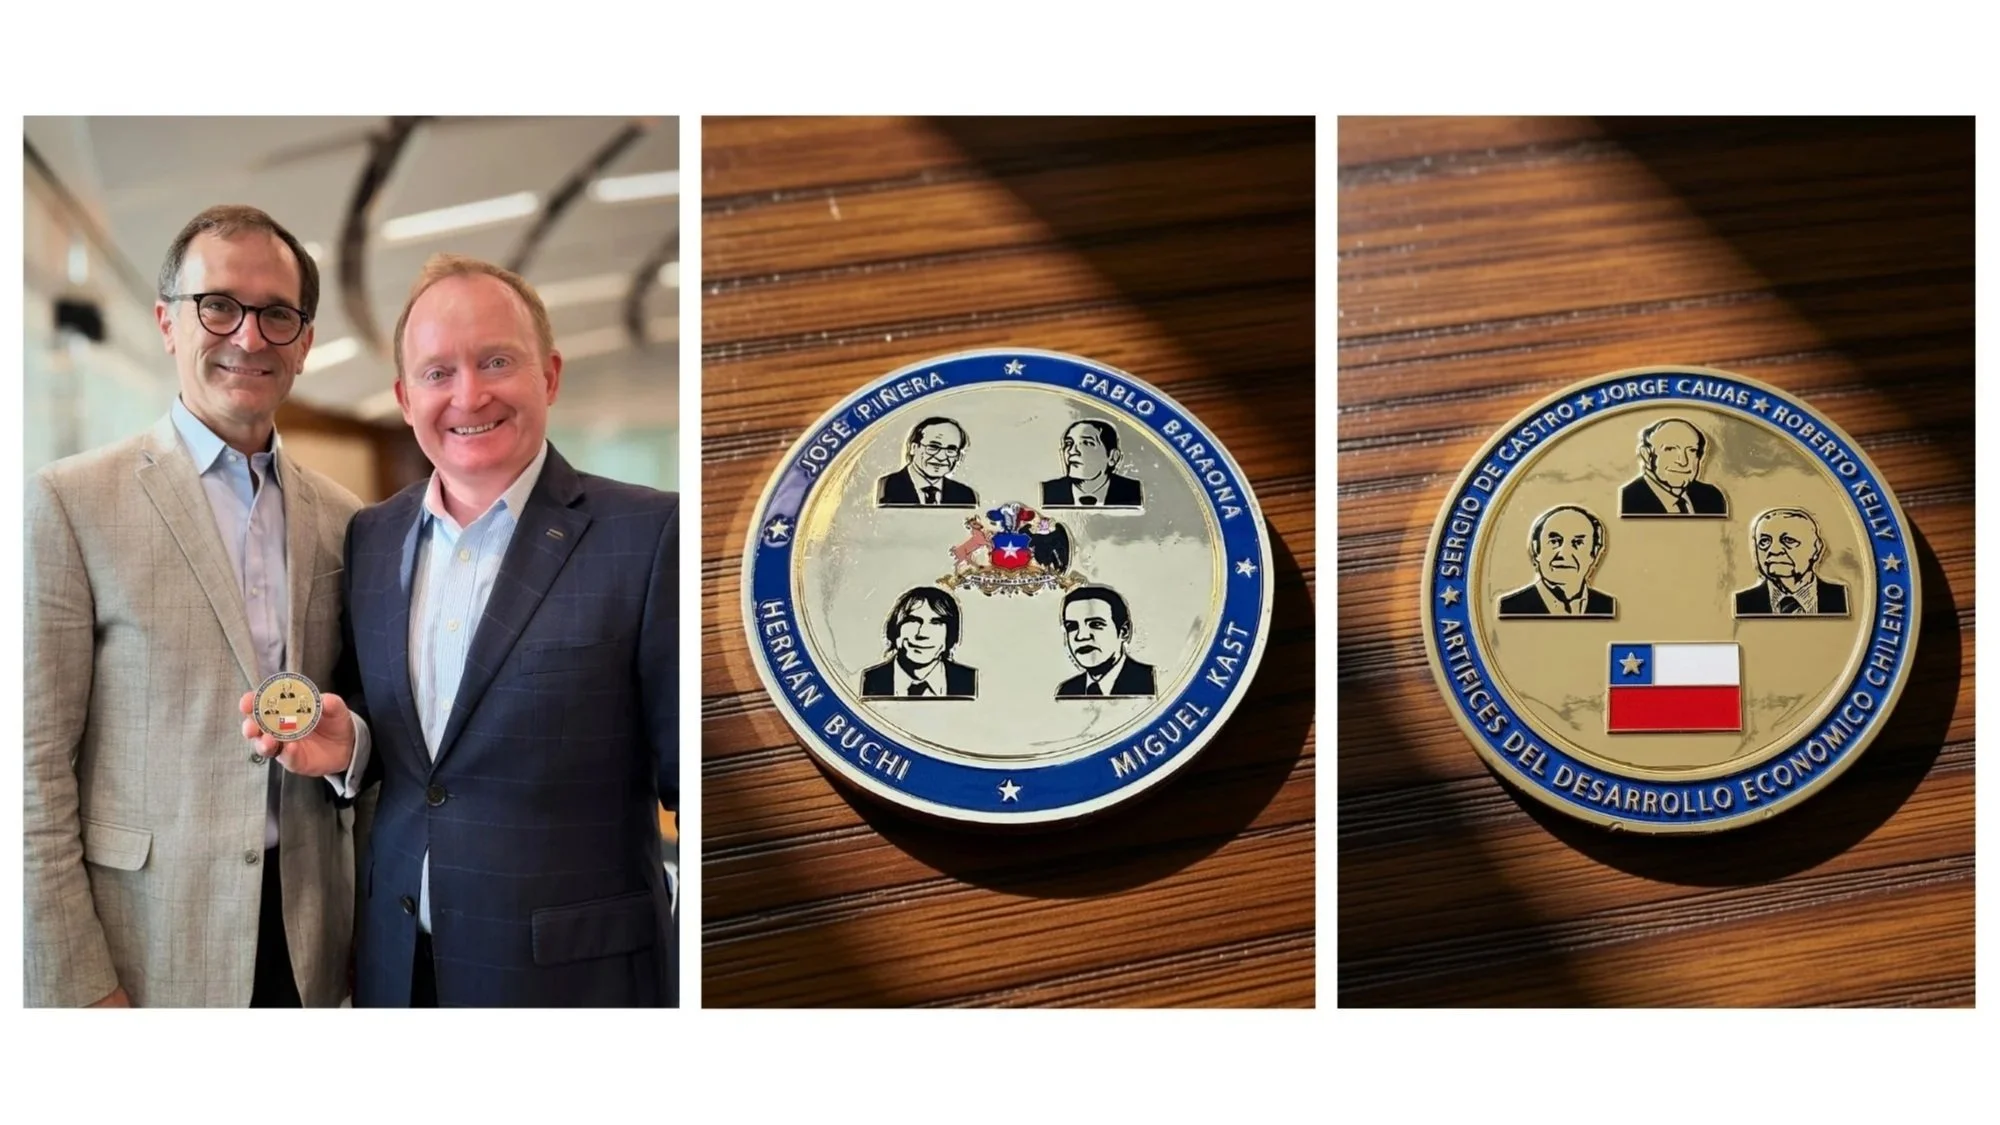
A friend and colleague in Chile was knocked off his bike by a delivery motorcycle, rupturing a hamstring. Four months off the bike. I wanted to post him honey from our hives, but quarantine rules will not let honey near a border, so he got possum and merino socks instead. Back came an intriguing coin.

One coin, two sides. Seven economists, the “Chicago Boys”, are featured, with one face honouring them as the architects of Chilean economic development. On the reverse sits Chile’s coat of arms and its national motto: Por la razón o la fuerza. By reason or by force. The coin tells the story of a country that tried both.

Nick with Rodrigo and the Chilean coin he kindly gifted him

From 1971 the Allende government nationalised copper, with Congress voting for it. It took the banks, and by late that year the state controlled seventeen of them holding around 90% of the country’s credit. Factories were requisitioned into public ownership. Wages rose and prices were held down. [1]

Then the shelves emptied. A black market grew. By January 1973 the government was rationing dozens of essentials, bread among them, and neighbourhood supply and price committees decided who got what. By December 1973, consumer prices were 508% higher than a year earlier. [2]

Now look at our ballot.

The Greens would force Foodstuffs and Woolworths to sell 120 stores and two distribution centres into public ownership as KiwiMart, at a cost of $2.8 billion. New Zealand First would buy the BNZ back from NAB and merge it with Kiwibank, at $7.5 billion upwards, with compulsory acquisition held in reserve. Labour would not take ownership but would set the price by banning excessive pricing on essentials. National, which normally resists this sort of thing, would split Pak’nSave from New World and Four Square if the Commerce Commission agreed that the separation would leave shoppers better off. [3]

Four parties, four instruments, one instinct. Peters calls it “taking back our country” rather than nationalisation, recalling the warning attributed to Emerson: “The louder he talked of his honour, the faster we counted our spoons.”

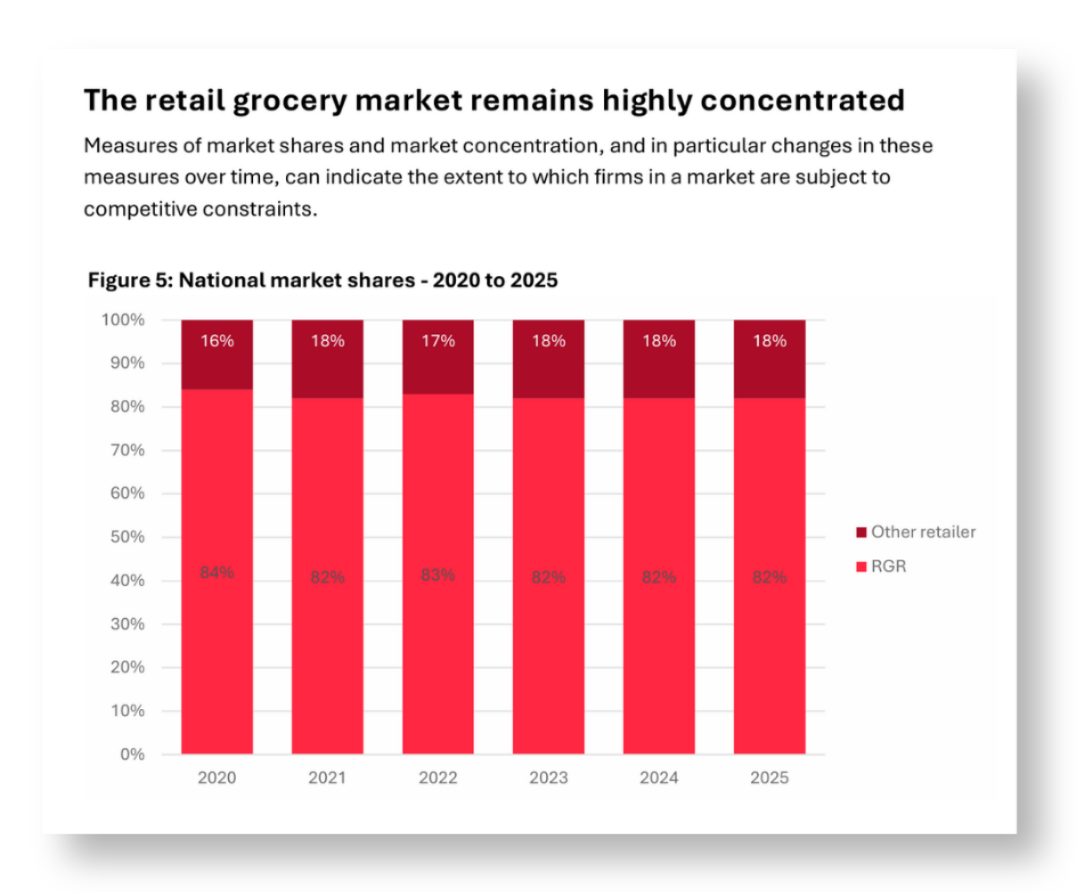
The grievance is real. The 2022 market study found the duopoly controlled about 90% of main grocery shopping, with excess profits the Commission then put at more than a million dollars a day. Four Australian-owned banks hold about 84% of lending. Nobody doing the weekly shop needs convincing that something is wrong. [4]

Source: Annual Grocery Report 2025/2026 - Commission analysis of sales revenue provided by industry participants and Statistics New Zealand data. RGR = Regulated Grocery Retailer

National’s proposal is the only one that changes market structure rather than ownership. It leaves every store in private hands and defers to the Commerce Commission. Willis is right that incremental reform has not delivered. ACT is against it. Foodstuffs points out that more than 500 owner-operated stores sit inside the two co-operatives. [5]

But all four reach for the till when the harder question is why nobody can build a shop.

Here is what that question looks like on the ground, twenty minutes from our Hastings office. In 2012, Foodstuffs North Island bought a site across the road from Pak’nSave Tamatea in Napier. It sold the site in 2015 with a covenant barring its use as a supermarket, one of a set running for up to 99 years. Woolworths had two stores in central Napier and none in the south of the city. The High Court found the covenant had been lodged to stop Woolworths, or anyone else, from developing a supermarket there. Justice Radich called the conduct deliberate and serious and, in August 2024, fined Foodstuffs $3.25 million, the largest penalty yet under section 28 of the Commerce Act. [6]

That is a Napier site that could have carried a third banner but did not. No act of nationalisation would have put one there. A rule did the damage, and a rule undid it. Grocery land covenants were banned in 2022 and are now unenforceable, but the Commission pursued the case anyway. [8]

Milton Friedman drew a distinction worth keeping in mind here. Being pro-free enterprise is not the same as being pro-business. Business corporations in general, he wrote, are not defenders of free enterprise but one of the chief sources of danger to it. Almost every owner wants open competition for everybody else and a little protection for himself. [7]

A covenant on a title is a moat dug by a company. A consent that takes years is a moat dug by a council. Both keep the third banner out, and the shopper pays for both. Defending property rights is not the same as defending the incumbent.

Yet four years on, there is still no third full-line chain in this country. Costco entered as a warehouse club, with its second site set to go up in Drury’s fast-tracked town centre. The Government now has a bill before the House creating a consenting express lane for new supermarkets. That is the admission. The binding constraint is not who holds the title. It is how long it takes to get a shop out of the ground. [8]

What changed Chile was not who held the shares but the conditions for competition: stable money, open entry, enforceable contracts and taxes that businesses could live with. From 1987 to 2015, the proportion of Chileans living below the national poverty line fell sharply, while income per person rose substantially. [9]

Scotsman Adam Smith made the same case centuries earlier: little else was needed to carry a state from the lowest barbarism to the highest degree of opulence but peace, easy taxes and a tolerable administration of justice. [10]

Source: Commerce Commission New Zealand

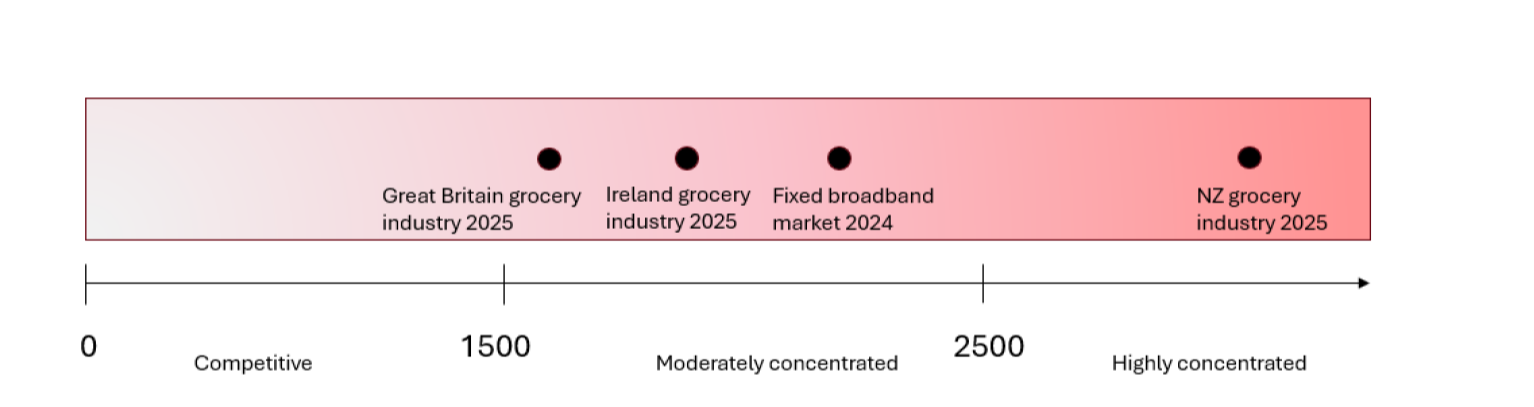
Herfindahl-Hirschman Index (HHI) takes the market shares of each firm in a market.

New Zealand’s grocery industry HHI for 2025 was 3,585 which indicates limited competitive pressure. Concentration in Auckland also remains high, with the HHI increasing to 2,635 in 2025, from 2,561 in 2024.

Click to view Annual Grocery Report

Smith’s other observation was our propensity to truck, barter and exchange. Nobody directed the socks or the coin, no price was named, and both of us came out ahead. The only authority involved was the biosecurity rule that stopped the honey, exactly the sort of plain, predictable rule Smith meant.

The honest part is what the coin leaves off. Chile’s reforms were imposed by a dictatorship, which stripped them of legitimacy. Growth continued after democracy returned in 1990: force set the policy, but reason made it stick. [9]

There is a cost in all of this that appears in none of the parties’ costings, and it lands on people who did not vote for any of it.

Every valuation rests on what a business will earn and the rate at which those earnings are discounted. Political risk goes into that rate. Lift it and the value falls, with no change in the till.

Neither Foodstuffs nor Woolworths New Zealand is listed here, and BNZ belongs to NAB, so no New Zealand portfolio moved directly on those announcements. The precedent is what moves. If a government can force an owner to sell a profitable business at a price set by the Crown, or legislate its structure apart, every regulated business in this country carries a little more risk than it did a month ago. Contact, Meridian, Genesis and Mercury are on that list, and New Zealand First has named them for a split of its own. So are the ports, airports and lines companies.

KiwiSaver held $138.8 billion at March 2026. Those companies sit inside it. The people who own them are not speculators. They are teachers, shearers and people in their sixties who have been contributing since 2007. [11]

Property rights are not an ideological flourish. They underpin every valuation of the shares held in your portfolio and KiwiSaver.

Fix the rules and competition follows. Buy the shops and the government owns the queue.

The Chileans put both options on their coat of arms and have tried each one: by reason or by force.

The vote will decide which of those we reach for. How you respond is still your choice and worth good counsel.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References

1. Espinosa, R. (2021). Salvador Allende’s development policy: lessons after 50 years. Economic Affairs; De Vylder, S. (1974). Allende’s Chile. Cambridge University Press.

2. Edwards, S. (2023). The Debauchery of Currency and Inflation: Chile, 1970–1973. NBER Working Paper 31890; Datosmacro.com. (1973). IPC de Chile 1973, reporting December 1973 CPI inflation of 508.0% year-on-year.

3. RNZ and 1News, 16 September 2026, National to pursue Pak’nSave and New World break up; NZ Herald, 3 September 2026, Greens promise to nationalise 120 supermarkets; RNZ and interest.co.nz, 17 May 2026, NZ First proposal to buy back BNZ and merge with Kiwibank; NBR, 16 September 2026, Labour price gouging policy.

4. Commerce Commission (2022). Market study into the retail grocery sector: Final Report, 8 March 2022; Reserve Bank of New Zealand banking sector statistics, 2026.

5. RNZ and 1News, 16 September 2026, National to pursue Pak’nSave and New World break up. The independent analysis cited by Nicola Willis modelled grocery prices 3.5% lower after one year and 5% lower after six, with $12.6 billion of consumer benefit over twenty years. Foodstuffs and ACT responses reported the same day.

6. Commerce Commission v Foodstuffs North Island Ltd, High Court, Wellington, August 2024; Commerce Commission media release, 8 August 2024; Simpson Grierson, Competition and Consumer Law Update, August 2024.

7. Friedman, M. (1999). The Business Community’s Suicidal Impulse. Cato Policy Report, Vol. XXI No. 2, for the quoted sentence; the wider argument runs through Friedman, M. and Friedman, R. (1980). Free to Choose. Harcourt Brace Jovanovich.

8. Commerce (Grocery Sector Covenants) Amendment Act 2022; Commerce Commission v Foodstuffs North Island, $3.25 million penalty, 2024; RNZ and Beehive, 12 November 2025, second Costco store at Drury and the supermarket consenting express lane bill.

9. World Bank. Poverty headcount ratio at national poverty lines (% of population) – Chile, 1987–2015; World Bank. GDP per capita (constant 2015 US$) – Chile, 1987–2015; Edwards, S. (2023). The Chile Project: The Story of the Chicago Boys and the Downfall of Neoliberalism. Princeton University Press.

10. Stewart, D. (1793). Account of the Life and Writings of Adam Smith LL.D., quoting a paper by Smith of 1755; Smith, A. (1776). An Inquiry into the Nature and Causes of the Wealth of Nations, Book I, Chapter 2.

11. Plan For Life research, KiwiSaver funds under management at March 2026.

Into the Tenth Year: the Froth, the Fear and What I Got Wrong

Article #475

This week Canny View rolls into its tenth year under that masthead. I had been writing and being interviewed for a good while before the name went up in print, but the masthead has its own anniversary, and this is it. Ten years is also the period our industry uses to judge anything worth judging, so rather than mark the occasion with sentiment, let us mark it by looking at the decade just gone.

Rewind to 2016. John Key was Prime Minister and would resign within three months. The Official Cash Rate had just been cut to 2 percent, a record low at the time. Bitcoin was about US$600. KiwiSaver held roughly $35 billion. New Zealand, after a remarkable run, had been one of the best performing developed sharemarkets in the world over the preceding decade.

AI was a research topic, not an investment theme, and rockets were the business of governments. Had you suggested the most talked about launch company of the coming decade would be firing satellites into orbit from a paddock at Mahia, you would have been humoured and offered another drink.

The settled view then was that returns would be thin for years. It was wrong, as it usually is. The scoreboard since then is a useful reminder of how poorly certainty ages.

The scoreboard

Including dividends, a dollar invested in United States shares in September 2016 is worth roughly four times what it was. Morningstar puts the return of US equity funds at 13.3 percent a year over the decade to December 2025, the most profitable ten years in the category's history.

Source: Trading View

The NZX 50 almost doubled, reaching 13,757 at last close*. Respectable. But the market that led the developed world to 2016 spent the ten years after it well behind.

Then there is Rocket Lab. Launching from Mahia, listed on the Nasdaq, and worth around NZ$80 billion. One company, built here and launching from here, is worth two fifths of every company on our own sharemarket combined, while sitting outside it.

Leadership rotates without warning and never announces the handover. That is the whole argument for owning the world rather than the paddock you happen to live in.

Source: Stuff

What we lived through to get there

Four times your money looks serene on a chart, yet it was not serene to live through: the late 2018 slide, the 2020 crash that took a third off global markets in thirty-three days, the 2022 bear market when shares and bonds fell together, and this year’s crypto unwind and Middle East tension. Each one was a headline. Not one was a reason to dismantle a properly built portfolio.

Source: CRSP Market Deciles 1-10 Cap-Based Portfolio (total returns in USD). All US exchanges rebalanced quarterly.
Data provided by the Center for Research in Security Prices (CRSP), University of Chicago.

Edmund Burke wrote in 1790 that because half a dozen grasshoppers make the field ring with their importunate chink, while thousands of great cattle chew the cud in silence, we should not imagine that those who make the noise are the only inhabitants of the field.

Two hundred and thirty six years on, the grasshoppers have a podcast and a following. The cattle still say nothing.

The habit gap

Here is the finding that should stop every investor cold. Morningstar examined 23,000 American funds over the same ten years. The funds returned 9.9 percent a year; the average dollar invested in them earned 8.7 percent. That gap is not fees and not fund performance. It is timing: buying after the good news and selling after the bad. Across the decade, it cost investors about US$3.8 trillion.

The encouraging half is that the gap shrank wherever temptation was hardest to indulge. Investors in broadly diversified all-in-one funds captured almost all of their return; those in index funds gave up 0.1 of a percentage point. That is not evidence that advisers rescue people mid-panic. It is evidence that the gap was smallest where the structure had already removed the decision: broad diversification, rebalancing on a date rather than a feeling, and contributions that arrive whether or not you fancy investing.

Architecture, not heroics. Less doing, more owning.

Bitcoin, meme coins and the black dog

Bitcoin has been the decade's most spectacular chart, from about US$600 to a peak of US$126,209 in October 2025, and its clearest lesson in the gap between an asset's return and an investor's return. Crypto ETFs listed since January 2024 returned 8.5 percent a year to 30 June 2026, yet the average dollar in them lost 5.8 percent a year, a gap of more than fourteen points. Money arrived after Bitcoin had climbed and left after it had fallen. Beneath it sits the meme coin, priced on nothing but the hope that the next person is willing to pay more.

Chasing it has been like chasing a black dog in the night: money pouring after something you cannot quite see, arriving after the climb and leaving after the fall. Calling something digital gold does not make it gold.

Where I got it wrong, and where the design spared me

Very few of our macro calls have gone badly wrong across the decade, and that is not luck dressed as skill. Do not mistake us for a passive firm. We work very hard, but the work goes into engineering, not forecasting. The plan is engineered on evidence, tested and rebuilt, and everything flows from it.

Nor are the portfolios index trackers. They lean deliberately on the dimensions the research has borne out over decades: company size, relative price, and profitability, the work of Fama and French and what followed it. That is a design decision, made on evidence and held, rather than a view on next quarter. We are active in the design and the planning, not in the stock picking or the market timing. My job is to engineer, not to predict.

The errors that cost were process errors. Choosing who you build your business with is pivotal, and I have twice chosen badly: one supplier over-promised, one developer under-delivered. Neither cost much money, but both cost time, and time compounds into the money you never got around to making. The lesson is the old one: it is either up to standard or down to price.

Then two judgement calls, neither about markets.

I hoped our love affair with residential property would cool. It has not, despite the asset delivering one of its more sobering decades. The average New Zealand house is down 15 to 17 percent from its 2021 peak in dollar terms and 28 to 31 percent adjusted for inflation, twice as deep as the post-global financial crisis trough of 16 percent. Here is the part that stopped me: in real terms, Cotality has the average house worth about what it was in mid-2016. A full decade, and in purchasing power the family home has gone precisely nowhere. And still we treat one leveraged, undiversified, illiquid asset in one small corner of the world as a retirement plan.

Source: CoreLogic

The House Price Index (HPI) measures the movement in house prices throughout New Zealand, providing an indicator of capital growth. The data is compiled and published by CoreLogic. Data from 1990 is available in the key graph data file.

The second was not a market call at all. I assumed my father would age gracefully. He died at 76. Every retirement plan I build carries a longevity assumption, and I had quietly applied a generous one to my own family without examining it. I see the same blind spot in households: people can often recite every detail of the money: salaries, perks, KiwiSaver contributions, cover held through work, yet cannot say when they last had a check-up, or what their cholesterol, PSA, or calcium heart score might be. We measure what is easy to measure and quietly assume the rest will hold, but the plan assumes years you may not be given, so spend some of them while you can.

Beyond those, I have been fortunate to take counsel from some beautiful minds with big hearts, which is rather the point of this column.

What has not changed

A client without a documented plan is a client without a map: the journey is perhaps exciting, but the destination is unknown and chosen by no one. When the values are known, the decisions are easy. Clients who could tell me what the money was for held their nerve in March 2020; those who could only tell me what it was worth generally did not. We are in the goal achievement business, not the market beating business, and beating the market while missing your goals is a poor trade.

A fiduciary's job is not to keep you comfortable. It is to speak the unspoken truth and sit opposite you when the noise is loudest. Some of the most valuable advice of the past decade fitted into two words: do nothing.

Evidence favours patience. Like a freshly poured beer, you do not drink it while it is all head. Let the froth settle. The investors who did best over the decade were rarely the cleverest in the room. They were the ones who repeatedly did the dull thing when it felt wrong.

Whatever you have built so far is the smaller half of the story. What matters is what is still in front of you, and whether it is engineered rather than merely hoped for.


* NZX 50 as at close on  Thursday, September 17 2026 = 13,756.59


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


Cheap Money has a Maturity Date

Article #474

In January 1672, Charles II stopped paying his creditors. 

The Stop of the Exchequer was announced as a temporary suspension. A delay, not a default. The distinction mattered a great deal to the Crown and not at all to the people who were owed the money. A borrower who cannot pay on the day they promised has defaulted, whatever the announcement calls it. 

The goldsmith bankers of Lombard Street, who had lent the Crown the money, were ruined. English government credit took a generation to recover. What eventually replaced it was something better than a king's promise: a funded national debt, the Bank of England in 1694, and a Parliament standing behind the borrowing rather than a monarch who could walk away from it. 

Over the century that followed, Britain outlasted Louis XIV and then Napoleon, both of whom governed larger and wealthier countries. Britain did not win because it was richer. It won because it could borrow more cheaply, for longer, and go on borrowing when its rivals could not. Creditworthiness turned out to be a weapon. 

The price of borrowing is not set by announcement. It is set at auction, by whoever turns up with capital and a choice about where to put it. Central banks can turn up too, and for a decade they did. But the auction reasserts itself the moment the official bid is withdrawn.

The OCR is not the whole story 

On 2 September the Reserve Bank lifted the Official Cash Rate to 2.75%, with annual inflation at 4.1% in the June quarter, driven largely by fuel prices flowing from the Middle East conflict [1]. 

The OCR sets the short end. It does not set the rate on a five-year term deposit, a two-year fixed mortgage, or a ten-year bond. Those price off wholesale rates, and wholesale rates are set in a global auction New Zealand does not run and cannot influence. 

A great many borrowers are turning up to that auction at once. 

Germany is funding a substantial military expansion by borrowing, with no corresponding retreat from its welfare state. Britain plans to expand its own. The bill for both goes to the same auction. The pattern repeats across the West, while the technology companies raise enormous sums to build artificial intelligence data centres. 

Nor is this only a Western habit, and China is the clearest case of a number that is not what it is announced to be. Beijing's headline deficit for 2026 is 4% of GDP. Once the CNY 4.4 trillion of local government special purpose bonds and the CNY 1.3 trillion of ultra-long special treasury bonds sitting outside that headline are counted, the consolidated deficit reaches a record 9.1% of GDP [2]. National debt is set to rise by close to CNY 14 trillion this year alone. 

The rate matters more than the level. Mark Williams, chief Asia economist at Capital Economics, calculates that China's total debt outside the financial sector has doubled as a share of GDP since 2010 and now tops 300%, putting its indebtedness, in his words, in a league of its own. The comparison most readers expect runs the other way. Broad American debt, public and private, has fallen as a share of GDP since 2010, to around 265% [3]. Nearly 40% of China's is owed by the public sector, local government financing vehicles included [3]. 

The numbers are not small. OECD central governments issued USD 17 trillion of bonds in 2025 and are projected to issue USD 18 trillion this year. Corporates added USD 6.8 trillion. All of it lands in a market where central banks, having spent a decade as the buyer of last resort, have stopped buying [4]. Local government sits in the same queue, one step removed, borrowing through agencies that price off the sovereign. 

More bonds offered, not proportionately more buyers at the same price, so the yield must rise to attract the capital. German ten-year yields are at their highest since 2011, Japanese yields have crossed 3%, and British gilts are at their highest since the financial crisis [5]. 

The honest counter-argument 

It would be tidy to say that governments and technology companies are crowding everybody else out, and leave it there. It would also be a little too tidy. 

Corporate borrowing did reach a record in 2025, USD 13.7 trillion raised across bond and syndicated loan markets, passing the 2021 peak. Nine large technology companies accounted for USD 122 billion of it, around 45% of all bond issuance by technology firms worldwide and more than three times the annual average since 2000. Yet the OECD's own assessment is that this came to no more than 15% of investment grade issuance by non-financial firms in the United States, and was absorbed without market-wide friction [6]. Capital markets are deep, and the pool is not fixed in the way the word crowding suggests. 

There is also a competing explanation for the move in yields that has nothing to do with supply at all. The oil price shock has reignited inflation expectations, and investors demanding more compensation for inflation will lift yields whether or not another bond is ever issued. 

Both explanations are probably doing some of the work. That is usually how markets behave, and anyone offering a single clean cause is selling something. What is not in dispute is the direction of travel, or that a borrower refinancing in 2029 will pay whatever the market asks in 2029, regardless of which explanation was correct. 

There is a second detail in the OECD data worth sitting with. Issuers have been shortening their maturities. In 2025 the ratio of bonds issued at thirty years and beyond, compared with those issued at one to five years, was the lowest since at least 2008 [4]. Short borrowing is cheaper today. It also means the debt comes back around sooner, and more often. That is a decision to pay less now, in exchange for finding out later. 

Cheap money has a maturity date 

A higher yield is not felt today. It is felt at maturity. 

Nearly 80% of what OECD governments borrow this year is not new spending at all. It is refinancing debt that already exists [4]. Borrowers who locked in cheap fixed rates a few years ago keep them right up to the day the debt rolls off and must be refinanced at whatever the auction is charging then. It will bite hardest where the debt is largest and the maturities shortest. Heavily indebted institutions are not repriced gradually. They are repriced in instalments, on a timetable set years ago by people who are frequently no longer there. 

New Zealand is not exempt. In March, Fitch revised New Zealand's outlook to negative while affirming the AA+ rating, forecasting general government debt at 56% of GDP by June 2027 and citing delayed fiscal consolidation [7]. Six days later the Local Government Funding Agency received the same revision, automatically, because as a government-related entity its rating is equalised with the Crown's [8]. LGFA provides most council borrowing in this country, Hastings included. 

Everyone drinks from the same pond.

Sovereigns, councils, banks, businesses, then the household. Different straws at different depths, the same water. Nobody in Taihape voted on the German defence budget. It is in the swap rate all the same, and the swap rate is in the mortgage at renewal. 

Milton Friedman's advice was to keep your eye on one thing only, how much government is spending, because that is the true tax. Thatcher put it less gently, that we have been ruled by men who live by the illusion that you can spend money you have not earned without eventually falling into the hands of your creditors. Whatever one makes of the politics, the arithmetic has not been repealed. The auction is where the bill arrives, and it arrives with interest. 

What this means for the investor 

For anyone with savings, this cuts both ways. 

After a decade of being told the coupon was a rounding error, it is worth having again. Income that had effectively disappeared from conservative portfolios has come back, and for retirees drawing on capital that is a meaningful improvement rather than a technical one. 

But a yield is not a gift. It is compensation, and the whole question is compensation for what. Credit quality, term, currency, and who stands behind the issuer. A bond paying more than the one beside it is priced that way for a reason, and the reason is rarely generosity. When someone offers a return well above the market for what they describe as much the same risk, one of those two claims is wrong, and it is not usually the return. 

Nor is the answer to reach for duration simply because longer bonds pay more today. Term is a risk, not a free lunch, and the investor who buys a long maturity to capture an extra sliver of yield has taken a view on the next decade of inflation whether they meant to or not. 

Bonds belong in a well-engineered portfolio. Not every bond belongs in yours. All bonds are equal, as Orwell might have put it, but some are more equal than others. 

Charles II discovered that credit, once lost, is not bought back. It is earned back, slowly, and usually by someone else's generation. The investor who reaches for yield without asking what it is paying for learns a smaller version of the same lesson. That question is easier to answer when the person answering it is bound by duty to put your interests before their own.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References 

1. Reserve Bank of New Zealand (2 September 2026). OCR increased by 25 basis points to 2.75%. https://www.rbnz.govt.nz/news-and-events/news/2026/09/ocr-increased-by-25-basis-points-to-2-75 

2. China Power Project, Center for Strategic and International Studies (2026). Making Sense of China's Government Budget. https://chinapower.csis.org/making-sense-of-chinas-government-budget/ 

3. Fortune (11 May 2026). Forget US debt, China's total borrowing is in a league of its own. https://fortune.com/2026/05/11/us-debt-china-total-borrowing-public-private-gdp-ratio-lgfv/ 

4. OECD (2026). Global Debt Report 2026: The investor base for government and corporate bond markets. https://www.oecd.org/en/publications/global-debt-report-2026_e9d80efd-en/full-report/the-investor-base-for-government-and-corporate-bond-markets_e68b90b3.html 

5. CNBC (3 September 2026). Global bond yields rising: Treasuries, JGB, Bunds. https://www.cnbc.com/2026/09/03/global-bond-yields-rising-treasuries-jgb-bunds.html 

6. OECD (2026). Global Debt Report 2026: Corporate debt market outlook in a transforming world. https://www.oecd.org/en/publications/global-debt-report-2026_e9d80efd-en/full-report/corporate-debt-market-outlook-in-a-transforming-world_cf86a220.html 

7. Fitch Ratings (20 March 2026). Fitch revises outlook on New Zealand to negative; affirms at AA+. https://www.fitchratings.com/research/sovereigns/fitch-revises-outlook-on-new-zealand-to-negative-affirms-at-aa-20-03-2026 

8. New Zealand Local Government Funding Agency (26 March 2026). Credit Rating Outlook Revised to Negative by Fitch Ratings. NZX announcement. https://announcements.nzx.com/announcement/469979 


When the Ram Touches the Wall

Article #473

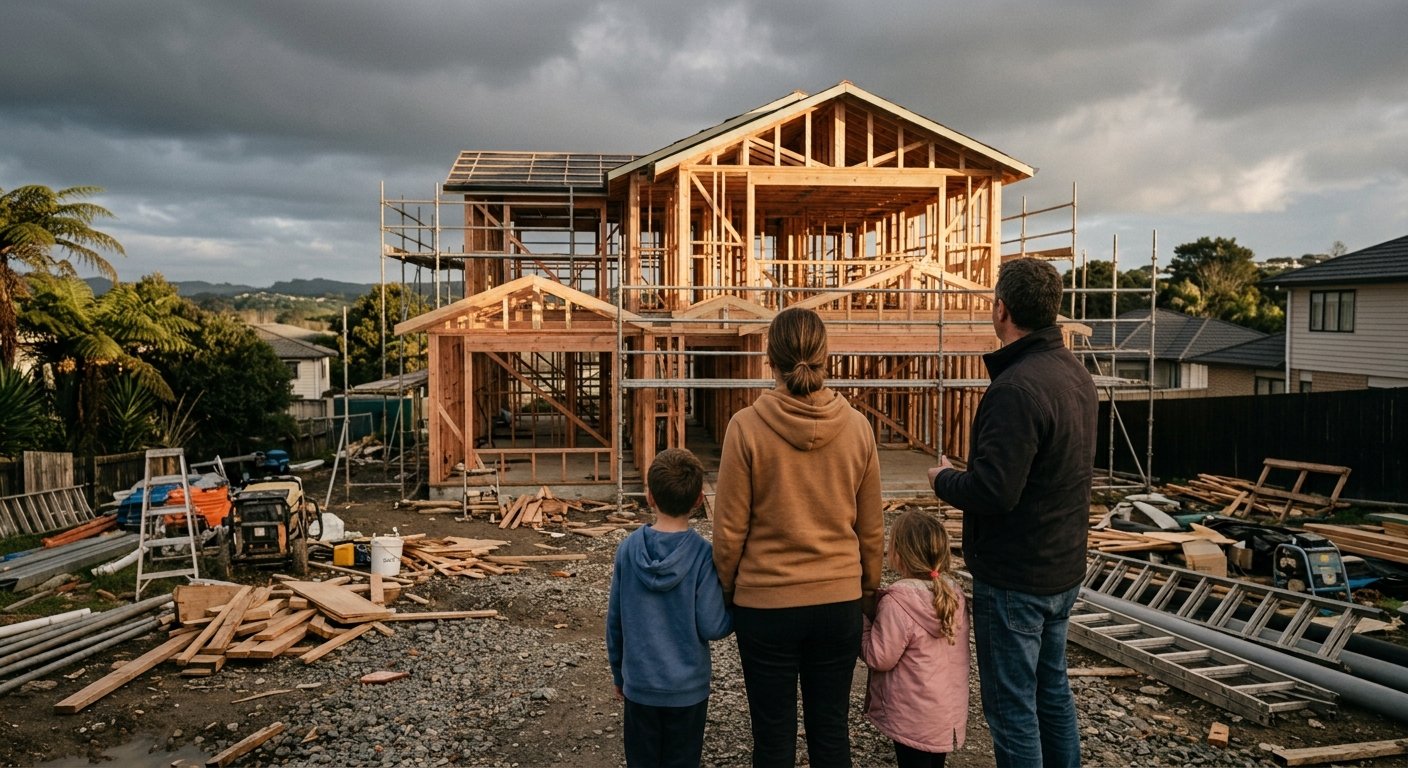
Picture the young family who’ve saved for years. They pay the builder their deposit, the framing goes up, and then the phone stops being answered. The company’s in liquidation. The director walks away, the guarantee dies with the business, and they’re left with a half-built home and almost no recourse. 

That collapse has a second victim you don’t see – the honest builder down the road who quoted the job properly, priced in his tax, and lost the work to a rival who never intended to pay his way. 

The idea of walking away from your debts is as old as commerce itself. The Romans had a grim phrase, murum aries attigit – the ram has touched the wall. A battering ram was tipped with a heavy bronze or iron ram’s head, and once that head struck the city wall, the defenders could expect no mercy under the customs of war – the siege was over, and quarter was no longer owed. The image was one of a point of no return. Yet modern commerce has inverted that ancient severity. The ram touches the wall, the debts fall due, and the aggressor strolls off to trade next week under a fresh name, the old company left as rubble for the creditors to pick over. 

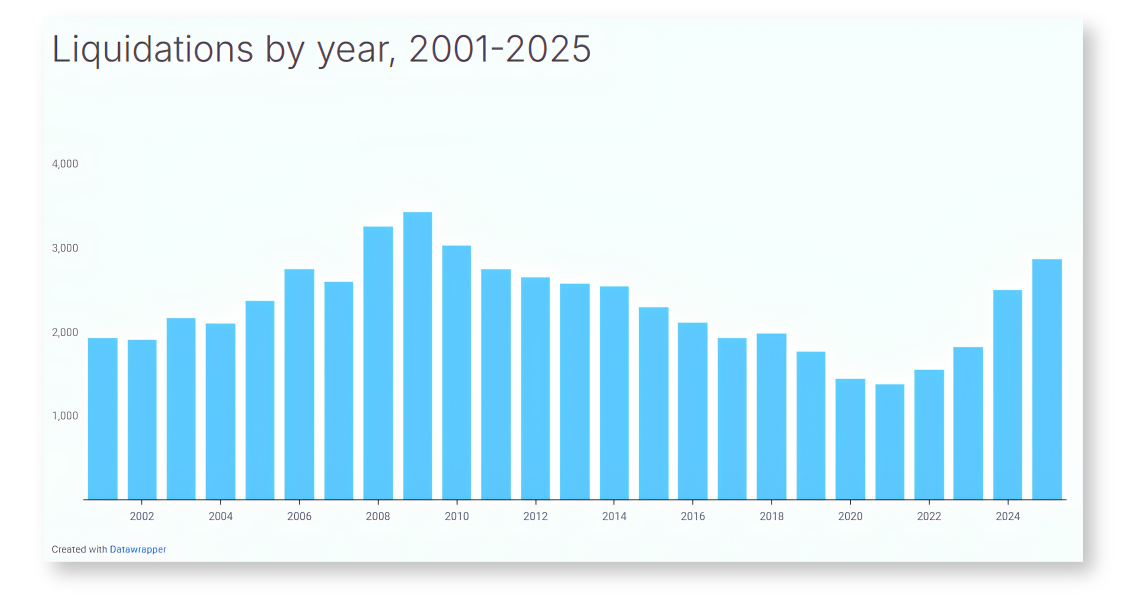
The numbers tell the story. Over 3,000 companies have gone into liquidation in the past year, leaving company failures at levels not seen for more than a decade. Construction still accounts for the largest share, with 764 liquidations; hospitality remains under pressure too, with 422 failures, up 42%. Inland Revenue is now the applicant behind roughly 70% of winding-up applications, as the leniency of the Covid years gives way to a long overdue reckoning. 

Source: Waterstone Insolvency

Here is the moral hazard. During Covid, the Labour government asked Inland Revenue to go easy, and at the time that was fair and humane. Businesses were shuttered by decree, cash flow evaporated overnight, and a temporary forbearance kept many good firms alive. But leniency without an end date breeds zombie firms – businesses trading on, not paying their GST or their PAYE, quietly undercutting the honest operator who cannot possibly compete with someone who simply isn’t paying their way. Audits went uncompleted for years, enforcement was paused, and the tax owed built quietly in the background like water behind a dam. 

And who ultimately foots that bill? You do. Every dollar of GST and PAYE that a ghost firm never pays is a dollar the honest taxpayer must cover, whether through higher taxes tomorrow or services forgone today. GST, remember, is money the firm has already collected from its customers on the Crown’s behalf; PAYE is money already deducted from its workers’ wages. When a ghost firm fails to hand it over, it has not merely gone broke, it has spent money that was never its own. The zombie firm does not just wound its competitor, it quietly picks the pocket of every citizen who does pay their way. 

The distortion runs deeper than a single lost contract. When a firm can undercut the market by the margin of its unpaid tax, it sets a false price for everyone. Honest competitors are forced to choose between matching an impossible number or losing the work. Some cut corners to survive; some cut their own obligations; a few simply give up. In this way the rot spreads outward from one bad actor, and the market slowly learns that paying your way is a competitive disadvantage. That is precisely the lesson a healthy economy cannot afford to teach. 

I noted one in the list of failed firms that had gone to the wall, having proudly offered a lifetime guarantee on its workmanship. It sounds reassuring, and no doubt it won the firm plenty of work. But a lifetime guarantee is only as good as the lifetime of the company. When the business is gone, so is the promise, and the customer is left holding a worthless piece of paper, or a whispered word gone with the wind. 

The remedy is not cynicism, but vigilance. So the burden falls back on you, the customer, to do your due diligence. It is not the headline price that counts; it is the fine print. As a mentor of mine puts it, pay attention to the fine print: it is far more important than the selling price. So ask the questions. Is your builder a Registered Master Builder? Does the firm carry serious credit accreditation and a clean Centrix credit history? Are they carrying forms of debt they cannot service? These are not rude questions, they are prudent ones, and the reputable operator will welcome them. 

Damien Grant, the principal of insolvency firm Waterstone, sees the same pattern from inside the system. “One of the challenges of doing business in New Zealand is that it is too easy for firms not to pay their PAYE or GST, and they can do so for years before the IRD moves to liquidate them,” he says. “Many of these zombie firms continue on well beyond the point at which they should have ceased trading.” 

The result, he argues, is twofold: honest firms are forced to compete against businesses carrying an unfair tax advantage, and when those businesses finally fail, the unpaid bills and wider economic damage are larger than they needed to be. 

And we close here. When you’re handing over your deposit, or your life savings, the cheapest quote can prove the most expensive decision you ever make. This is where a fiduciary matters – someone whose duty is to tell you the unspoken truth, not to sell you comfort. Do the homework before you sign, because when the ram touches your wall, it is already too late. 


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References

  1. RNZ, “Last call: 3000 hospitality businesses gone in a year as business feels the crunch”, 1 September 2026. Centrix reported 3,092 company liquidations in the past 12 months, up 14 percent year-on-year, with construction recording 764 liquidations and hospitality recording 422 liquidations, up 42 percent. 

  2. McDonald Vague / LawNews, “Dealing with the spike in IRD-induced business liquidations”, 26 June 2025. McDonald Vague reported that Inland Revenue accounted for seven out of every ten liquidation applications in the referenced period. 

  3. interest.co.nz, “Liquidations are rising, but the real problem isn’t Inland Revenue enforcement”, 18 April 2026. The article reported 365 winding-up applications in the first quarter of 2026, the highest first quarter in a decade, and noted Inland Revenue’s significant role in March 2026 applications. 

  4. Newsroom, “Inland Revenue audit surge is tapping deep, deep well of unpaid tax”, 4 June 2026. Newsroom reported that Inland Revenue’s boosted compliance activity followed a period of Covid-era leniency and that compliance returns remained strong, suggesting persistent tax gaps. 


The Trains Ran but the Dividends Did Not

Article #472

In August 1845 the index of British railway shares stood at 1,984. By April 1850 it was 673. [1]

What makes the Railway Mania worth remembering is not that it was a swindle, largely it was not. The technology was real, and what the money built is still there.

Parliament authorised thousands of miles of new line and the network more than tripled by 1850. At the peak, railway construction ran close to seven percent of national income, roughly half of all capital formation in the country. About a third of the authorised lines were never built. The rest ran for a century and a half. [2]

The story was right. The shareholders were still ruined. Clergymen, widows, country solicitors, Charlotte Bronte. People not greedy so much as correct about the future and wrong about the price. Something similar has just finished happening in China.

What China was promised, and what it delivered

Ten years ago, the story almost wrote itself. China would overtake the United States, and its currency would take a seat among the world’s reserve currencies. On 1 October 2016, the renminbi was fast tracked into the IMF’s Special Drawing Rights basket. [3]

The growth half largely came true. China’s economy grew from roughly USD 11 trillion in 2015 to USD 19.63 trillion in 2025, and is expected to cross USD 20 trillion this year. [4] Seventy percent in a decade, off an already enormous base.

The other half did not. It did not overtake the United States, which reached USD 30.77 trillion in 2025, and the IMF has quietly cut its own 2030 projection for China from USD 27.5 trillion to USD 23.1 trillion. [4] [12] Still, anyone who bought the growth story in 2015 was not badly wrong about growth. The mistake was assuming that national growth would translate cleanly into shareholder return.

Source: Statista | Largest economies worldwide 2026

What the shareholders got

For the period to 31 July 2026, the MSCI China Index returned minus 2.13% a year over five years and 4.88% a year over ten. These are net returns, after the withholding tax a foreign investor actually pays. Compounded, the five-year result is a cumulative loss of about 10.2%. [5]

Over the same periods, the MSCI All Country World Index returned 10.85% and 12.32% a year, while emerging markets returned 8.03% and 9.19%. [5] Put simply, a dollar in the world index grew to about USD 1.67. A dollar in China became about USD 0.90.

China did not merely lag the Americans, which is the comparison everyone reaches for. It lagged the emerging world it was supposed to be leading.

Nor is the ten-year figure as flattering as it looks. It was rescued by two strong years at the end.

Explore the full MSCI China Index Factsheet HERE

The middle of the period is where the damage was done. The index fell 21.72% in 2021, 21.93% in 2022 and 11.20% in 2023. [5] Together, those three losing years compounded to a cumulative loss of nearly 46%. A dollar invested at the start of 2021 was worth about USD 0.54 by the end of 2023.

The recoveries of 2024 and 2025, at 19.42% and 31.17%, look handsome in isolation. They are the arithmetic of climbing out of a hole. A 46% fall needs an 85% gain simply to get back to even.

Note what the ride cost. Over those five years, the index carried an annualised standard deviation of 27.89%, against 15.07% for the world index, and a Sharpe ratio of minus 0.08 against 0.53. [5] In plain English, China delivered nearly double the volatility and still a negative return. Investors were not paid for the risk. They paid for it.

An investor who bought at the loudest point fared worse still. The Shanghai Composite peaked at 5,166 on 12 June 2015 and, eleven years on, has not been back. [9]

The currency that never arrived

The reserve-currency promise is the cleaner failure, because it was measurable from the start. In the first quarter of 2026, the renminbi accounted for 1.99% of global foreign exchange reserves, down from 2.18% at the end of 2024 after dipping to 1.92% in the third quarter of 2025. The US dollar sat at 57.13%, and the euro at 20.03%. [6]

The IMF attributes most of the latest uptick to exchange-rate valuation rather than to reserve managers buying, and COFER revises prior quarters as reporting is corrected. [6] The useful reading is the broad trend, not the second decimal place: flat to down across a decade of ambition. Reserve managers proved unwilling to hold a currency they could not move freely.

New Zealand's exposure was in the order book

For New Zealand, the direct investment loss was probably not the main story. Very few New Zealanders held Chinese shares directly. Our exposure arrived through customers rather than the share register, which is harder to rebalance because nobody runs an annual review on their order book.

Wine is the clean example. Shipments to China rose 47% in the year to mid 2025, to $56 million, against total wine exports of $2.10 billion. [7] Volumes are climbing again this year, but prices are falling, with a bulk wine price war running through Marlborough as a record harvest looks for a home. [8]

The saviour story turned out to be champagne without the fizz. The litres arrived. The dollars did not.

The point runs past wine. A grower or packhouse built around one fast-growing market holds a concentrated position as real as any portfolio holding, and far less liquid. Plantings take years to come into production, and cool stores, packing lines and market accreditation are not reallocated over a weekend.

Worse, that exposure correlates with everything else on the balance sheet. Land value, the borrowing secured against it, the labour bill and forward sales all move in the same direction. When the market that was going to take everything decides to pay less, the hit lands everywhere at once.

The order book is the least diversified asset most owners have, and the only one they rarely review as an investment risk. If the business is already a concentrated bet on one market, the owner’s portfolio has no business becoming a second concentrated bet on the same story.

The grain of truth

The other side deserves its best case. Chinese shares are cheap: 14.09 times trailing earnings against 23.24 for the world index, 10.97 times forward earnings against 17.13, and a dividend yield of 2.26% against 1.59%. [5] Shanghai also posted its strongest year since 2020 and touched decade highs in March 2026. [9]

The trouble is that cheapness has been available the whole way down. China traded at a discount for most of the decade, and for much of it the discount widened. That did not stop 2021, or 2022, or 2023. A low multiple is not a floor. It is the market pricing risk, and sometimes it prices that risk correctly.

Nor should the recent strength be mistaken for a full recovery. The rest of the world ran hard over the same stretch, so China has closed no gap, and the five-year number is still negative after it. Selling today solely because of the last five years would repeat the 2015 error in reverse. The direction changes. The mistake does not.

Evidence favours patience. Let the froth settle before committing, like a freshly poured beer you do not drink while it is all head.

The fiduciary question

The plain question is who was telling you the story, and what they were holding while they told it. Growth narratives sell funds, conference tickets and column inches. That is not a conspiracy; it is how incentives work. But none of those people were in your portfolio when the five-year number came in negative.

A fiduciary has the less enjoyable job of saying that a good story and a good investment are not the same thing, and that the gap between them is where most money is lost.

A frog in a well

Sun Tzu put it plainly. A victorious army wins first and then goes to battle, while a defeated army goes to battle first and then looks for the victory. [10] The asset allocation is settled before the market does anything.

Calling economic growth a return does not make it a return.

The trains ran. The dividends did not. Both things were true at once in 1850, and both have been true again.

So before the next irresistible story arrives, seek advice and wise counsel. Remember what Zhuangzi wrote some twenty-three centuries ago: a frog in a well cannot be talked with about the sea, for he is confined to the limits of his hole. [11]

The frog was not wrong about his well. The well was real. It simply was not the ocean.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References

1. Campbell, G. and Turner, J.D. (2012). Dispelling the Myth of the Naive Investor during the British Railway Mania, 1845-1846. Business History Review, 86(1). Railway share price index at 1,984 in August 1845, falling to 673 by April 1850.

2. Arnold, A.J. and McCartney, S. (2022). Managerial Failure in early Victorian Britain: Network and capital expansion during the Railway Mania. Business History. Network reached 6,621 miles by 1850, tripled since 1844; railway capital formation near 7% of GDP in 1847; about a third of authorised lines never built.

3. International Monetary Fund. Currency Composition of Official Foreign Exchange Reserves (COFER), dataset notes. The renminbi has been separately identified in COFER from 2016Q4, following its inclusion in the Special Drawing Rights basket on 1 October 2016.

4. International Monetary Fund, World Economic Outlook, as compiled by Statista and Worldometer. China nominal GDP of USD 19.63 trillion (2025) and an estimated USD 20.85 trillion (2026); United States USD 30.77 trillion (2025).

5. MSCI (2026). MSCI China Index (USD) Index Factsheet, data as at 31 July 2026. Net returns in USD: MSCI China five year minus 2.13% and ten year 4.88% annualised; MSCI ACWI 10.85% and 12.32%; MSCI Emerging Markets 8.03% and 9.19%. Annual net returns 2021 minus 21.72%, 2022 minus 21.93%, 2023 minus 11.20%, 2024 19.42%, 2025 31.17%. Fundamentals: MSCI China P/E 14.09, forward P/E 10.97, dividend yield 2.26%; MSCI ACWI P/E 23.24, forward P/E 17.13, dividend yield 1.59%. Five year annualised standard deviation 27.89% against 15.07% for MSCI ACWI; five year Sharpe ratio minus 0.08 against 0.53.

6. International Monetary Fund (1 July 2026). IMF Data Brief: Currency Composition of Official Foreign Exchange Reserves, World Aggregates, First Quarter 2026. Renminbi 1.99% (from 1.95% in 2025Q4), US dollar 57.13%, euro 20.03%. Earlier briefs give the renminbi at 2.18% in 2024Q4 and 1.92% in 2025Q3. COFER revises prior quarters as reporting is corrected.

7. New Zealand Winegrowers (2025). Annual Report 2025. Exports to China up 47% to $56 million; total wine exports $2.10 billion.

8. Vino Joy News (July 2026). China's white wine boom has triggered a Marlborough price war.

9. Shanghai Stock Exchange data via CEIC and Trading Economics; Global Times (January 2026) reporting the Shanghai Composite's 18.41% gain in 2025 and its return to decade highs.

10. Sun Tzu, The Art of War, Chapter 4, Tactical Dispositions. Rendered by Thomas Cleary as: a victorious army first wins and then seeks battle; a defeated army first battles and then seeks victory.

11. Zhuangzi, Outer Chapters, The Floods of Autumn (Qiushui), 4th century BCE. James Legge translation: a frog in a well cannot be talked with about the sea, he is confined to the limits of his hole.

12. ChinaPower Project, Center for Strategic and International Studies (2026). Unpacking China's GDP. IMF projection for China in 2030 revised from USD 27.5 trillion (April 2023) to USD 23.1 trillion (April 2025).


Don't Buy All You Can Borrow

Article #471

Your parents lied to you.

Not about Santa Claus, or carrots improving your eyesight, or the dog going to live on a farm. About something far more expensive, and something you probably did with a pen in your hand and a banker smiling across a desk.

“Buy the best house you can afford,” they said, somewhere between the roast lamb and the pavlova. “Property always goes up.” They smiled knowingly, the way parents do when they think they have just handed you the map to the treasure.

They handed you a map, alright. To a different kind of buried thing entirely.

There is a peculiarly New Zealand religion around property, and we are its most devoted congregation. We flip through TradeMe listings the way other cultures read scripture, and attend open homes on Saturdays like it is church. We have been raised to believe that the house is the thing. The bigger the better. Stretch for it. The bank will say yes.

And the bank will say yes. That is precisely the problem. Banks are not your parents and they are not your friends. They exist to extract a return from the spread between what they pay for money and what they charge you for it, and are content to lend you every last dollar you can theoretically service. The bank's interest is not your interest. Literally.

Property Always Goes Up

Except when it does not. Cotality data released this month shows that in the second quarter of 2026, 13.1% of New Zealand homes resold at a loss, the highest since 2012, at a median $60,000 below purchase price and $159 million across the quarter. Investors fared worst at 13.5%, against 12.2% for owner-occupiers.[1] In fairness, 86.9% still resold at a gross profit, so this is a slide rather than a rout, and it has come without the mortgagee sales of the global financial crisis.

Source: Cotality | Explore Insights and Report HERE

But the number that matters most for this argument is the hold period. Profitable resales had been owned for a median of 10.4 years, a record high. Loss-making resales, 4.3 years.[1]

That is the whole case in two figures. Time rescues a property purchase, and borrowing to the absolute ceiling is what takes time away from you, because when the rate cycle turns or the premium arrives or the job changes, you sell when you must rather than when you choose. The buffer is not a luxury. The buffer is the hold period.

The counter-case deserves an honest hearing. Property has, over long periods, rewarded those who bought as much as they could as early as they could, while inflation eroded their debt. That is true, and it is also survivorship talking. The three conditions that made maximum leverage work, being falling interest rates, cheap and available insurance, and council rates rising near inflation, have now reversed at once.

The Rate Rollercoaster

Between November 2021 and May 2023 the Reserve Bank lifted the OCR from a record low 0.25% to 5.50%, and by January 2024 the average one-year fixed rate had climbed to 7.5% from 2.58%.[2] Households borrowed to the maximum of their serviceability were suddenly underwater. Rates came down through 2025 as the Bank cut nine times to 2.25%.[3] On 8 July 2026 it raised the OCR for the first time in three years.[4] The cycle is shorter than anyone expected.

Source: www.rbnz.govt.nz/statistics - New residential mortgage standard interest rates

Then Comes the Insurance Bill

House insurance averaged $2,815 in the final quarter of 2025, a 37% jump in three years, and Consumer NZ puts the rise at three times general inflation since 2011.[5,6,7]

Explore the full Consumer Insurance Report HERE

But price is no longer the whole story. Availability is, and that is a different order of problem. A premium is a negotiation. A refusal is a wall. You cannot get a mortgage without insurance, so a house that cannot be insured cannot really be sold. The valuation does not fall because the building changed. It falls because the finance did.

In January 2026 AA Insurance told the Buller District Mayor it would stop issuing new home, business and landlord policies across the postcode covering Westport, Carters Beach and Cape Foulwind.[8] Existing customers could renew. New buyers could not get cover at all. Within weeks it paused new policies in Woodend, citing seismic exposure rather than flood, then declined new business across Blenheim, Renwick and Seddon.[9] Legal commentators call this the beginning of a new kind of insurance retreat.[10] AA Insurance was simply the one that announced it. Others declined quietly.

Closer to Home

In April 2026 it emerged that Tower Insurance was refusing to cover some homes in Parklands Residential Estate, a modern council-owned development near Park Island in Napier. Buyers entering estate addresses into Tower's website were told cover could not be offered, the insurer citing a high risk of flooding from sea surge.[11]

These are new homes, with ground levels the council says were set above significant storm surge scenarios. And yet a major insurer would not touch them. Napier City Council is meanwhile spending $37.4 million on stormwater to protect Te Awa and Maraenui.[12] Public money, directed at a problem an insurer had already priced into its underwriting.

Cyclone Gabrielle caused $2.17 billion in insurance losses across this region, and the review that followed found new housing in areas of known flood risk suggested past lessons had not been learned.[13,14] Nobody mentioned any of this at the open home. Before you sign, enter the address into an insurer's website, read the LIM, and look at the flood hazard maps. That is the due diligence our open-home culture trains us to skip in favour of admiring the benchtops.

And Then There Are Rates

Not mortgage rates. Council rates, which are moving the same way. Stats NZ has local authority rates and payments up 8.8% in the year to March 2026, against headline inflation of 3.1%, and rates were the single largest contributor to that inflation figure.[15] Where water charges are shifting to a separate delivery entity under Local Water Done Well, the number on the rates notice is no longer the number leaving your account.

One More Thing: The Election

Every party to the left of centre now favours taxing property in some form. The differences are of instrument and degree, not direction.

Labour is campaigning on a 28% capital gains tax covering residential investment and commercial property, applying only to gains made after 1 July 2027, with the family home, farms, shares and KiwiSaver exempt. It would replace the bright-line test.[16,18]

The Greens go further, proposing a 2.5% annual super-rich tax on net assets above $10 million per individual, and a Capital Acquisitions Tax charging 33% on inheritances and gifts received above a lifetime threshold of $1 million, with family homes and family farms carved out and the tax paid by the recipient rather than the estate.[17] Opportunity, formerly TOP, proposes a land value tax of 1.75% urban and 0.5% rural.[19]

Te Pāti Māori has not published its 2026 tax policy, so its numbers for this election are not known. The direction is. The party campaigned in 2023 on a wealth tax rising to 8% on net wealth above $10 million, a 2% annual levy on property appreciation and taxes on undeveloped and vacant land, and KPMG counts it among those pressing for structural reform this time round.[16,20] Treat the 2023 figures as history rather than policy until the manifesto lands.

National, ACT and NZ First are not the mirror image of this. Neither proposes new property taxes, and their emphasis is on lower-tax settings and targeted reforms to boost investment.[16] That is closer to holding the current line than reversing it, and the current line is already favourable, with the bright-line test back to two years since July 2024 and full interest deductibility restored from April 2025. Their position is continuity, not a counter-offer.

KPMG notes that a capital gains tax is now the common denominator across the likely alternative government, although Chris Hipkins has ruled out Labour backing a wealth or inheritance tax.[16] None of it is law, and coalition negotiation will decide what any of it looks like. Voters decide on 7 November. But on one side of the House the direction of travel points squarely at property, and on the other it does not move at all.

What the Buffer Actually Buys

Take two buyers on the same street and the same income. One borrows $900,000 against a $1.05 million house. The other borrows $700,000 against an $850,000 house ten minutes further out. At 5.5% over thirty years, the gap in repayments is roughly $1,100 a month.

Nothing separates them while conditions hold. The difference appears when something moves. A one percentage point rise on $900,000 costs about $9,000 a year, against $7,000 on $700,000. A 37% jump in the premium lands on a household that has $1,100 a month of room, or on one that has none. A redundancy is a difficult year for one and a forced sale for the other.

That $200,000 was never really about the house. It was about buying the ability to wait, and the resale data says waiting is the whole game.

The Boring Alternative

Buy less than you can borrow. Keep a buffer. Sleep at night.

The house ten minutes further from the school zone that costs $200,000 less is not a failure. It is a margin of safety, and more to the point it is time. It is the difference between selling at 4.3 years because you have to and holding for 10.4 years because you can. It is the room to fix the roof without going back to the bank, and to stop doing anxious arithmetic at 2am. If you think professional advice is expensive, try using an amateur.

Property can be a wonderful long-term asset. But the best house you can afford is not the best house for you. It is just the biggest risk you were allowed to take.

The bank will tell you what you can borrow, not what you should. For that, seek impartial advice and wise counsel.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References

1. Cotality - Share of NZ Homes Selling for a Profit Falls to Lowest Level Since 2012. cotality.com/nz, 17 August 2026. https://www.cotality.com/nz/insights/articles/share-of-nz-homes-selling-for-a-profit-falls-to-lowest-level-since-2012

2. Mortgage Express NZ - Is Now the Right Time to Lock in Your Home Loan Rate? mortgage-express.co.nz

3. Canstar NZ - In Which Direction Are Mortgage Interest Rates Headed? canstar.co.nz, June 2026

4. Reserve Bank of New Zealand - Official Cash Rate raised 25 basis points to 2.50%, 8 July 2026. rbnz.govt.nz

5. Quashed - Why Is My House Insurance So Expensive? 2026 NZ Premium Hike Guide. quashed.co.nz

6. Reserve Bank of New Zealand - Insurance Availability and Risk-Based Pricing, Financial Stability Report, May 2024. rbnz.govt.nz

7. Consumer NZ - What's Going On With Home Insurance? consumer.org.nz, February 2026

8. RNZ - Insurer Temporarily Halts New Policies in Westport Due to Flood Risk. rnz.co.nz, 28 January 2026

9. NZ Herald - Major Insurer Declines New Home Insurance Policies for Blenheim. nzherald.co.nz, 3 February 2026

10. Minter Ellison - Insurers Dial Back Flood Risk Exposure: Where Will This Lead? minterellison.co.nz, May 2026

11. 1News - Insurer Flags Sea Surge Risk for Some Napier Estate Properties. 1news.co.nz, April 2026

12. Napier City Council - $37.4M Stormwater Investment Unlocks 400 Homes and Flood Protection for Napier. napier.govt.nz, December 2025

13. Insurance Business NZ - Hawke's Bay Homeowners Face Insurance Woes, Rising Security Risks. insurancebusinessmag.com, November 2024

14. Insurance Business NZ - Hawke's Bay Flood Review Highlights Need for Improved Risk Management. insurancebusinessmag.com, July 2024

15. Stats NZ - Annual Inflation at 3.1 Percent in March 2026: Local Authority Rates and Payments Up 8.8 Percent. stats.govt.nz, April 2026

16. KPMG New Zealand - Summary of 2026 Election Tax Policies. kpmg.com/nz, August 2026

17. 1News - Greens Propose Wealth, Inheritance Taxes to Fund Income Tax Changes. 1news.co.nz, 21 June 2026

18. Buddle Findlay - Labour's Capital Gains Tax: Time to Think Ahead. buddlefindlay.com, 2026

19. The Post - Opportunity Party Reveals Policies on Land Tax, Universal Basic Income and KiwiSaver Reform. thepost.co.nz, May 2026

20. RNZ - Te Pāti Māori Proposes Suite of Changes in New Tax Policies. rnz.co.nz, 27 July 2023. No 2026 tax policy published as at 20 August 2026


The Mozart Problem and the Bill New Zealand Keeps Refusing to Read

Article #470

Everything costs more, yet by every measurable standard, we are producing less. Welcome to Baumol's cost disease, with a Wellington twist. 

Picture a string quartet performing Mozart in 1790. Four musicians, half an hour, a finished piece of music. Now picture the same quartet performing the same piece in 2026. Four musicians, half an hour, the same music. 

The output is identical. The cost is not. 

This is Baumol's cost disease - economist William Baumol's 1966 observation that some sectors cannot get more productive no matter how clever you are [1]. You cannot ask the violinists to play twice as fast. Yet they must still be paid enough not to quit and retrain as software engineers. And engineers' wages keep rising because their productivity does. So performing the piece costs more every decade, while the performance itself never changes. 

Baumol's insight was never an argument against paying the violinist. It was a warning about where the money comes from. Rising wages in less productive sectors are affordable only because a productive sector somewhere is generating the surplus to fund them. Pull out the productive sector and the whole arrangement stops being generosity and starts being arithmetic. 

Which brings us to the Wellington twist. We have the disease. We do not have the cure. 

The number that is not moving 

On 1 April, the adult minimum wage rose again, to $23.95 an hour, up 45 cents, a 'moderate' two percent lift the government was quick to call balanced [2]. On the same day, main benefits rose 3.11 percent, indexed to the CPI. New Zealand Superannuation lifted 2.9 percent, indexed to wages. The default KiwiSaver contribution ticked up to 3.5 percent. The living wage moved to $29.90 an hour. The government indexed its obligations, sent out the press releases, and moved on. 

Businesses do not get to index theirs. They just get the obligation, and the bill that comes with it. 

Here is the part nobody in Wellington wants to say out loud. Stats NZ's own figures show multifactor productivity fell 0.9 percent in the year to March 2025 [3]. Labour productivity nudged up 0.8 percent, but only because firms shed workers faster than output dropped [3]. We did not get more productive. We got smaller, slightly less inefficiently. 

Our labour productivity gap with the top half of the OECD has widened from 34 percent in 1996 to roughly 40 percent today [4]. We sit alongside Mexico, Greece and Portugal [5]. Construction is the starkest case of all: the sector is producing at roughly the same rate it managed in 1985 [6]. Four decades of technology, and the shed goes up at the same speed. 

Baumol's violinist was paid out of a surplus the rest of the economy threw off. Ours is paid out of an economy that has stopped producing one. Every April the floor climbs. The output that is meant to fund it goes sideways at best. The gap does not close. It compounds.

Source: NZCBIA Report No 2024-01

California told us how this ends 

In April 2024, California lifted the minimum wage for large fast-food chains from USD 16 to USD 20 an hour: a 25 percent jump and one of the biggest single-sector hikes in American history [7]. The most rigorous peer-reviewed study to date found the sector shed around 18,000 jobs in the first year, roughly a 3.2 percent fall relative to the rest of the country [7]. 

But the more telling story is what came next. Two years on, researchers tracking the same restaurants found the damage had changed shape. Workers kept their jobs but lost hours, lost overtime, and increasingly lost out to a kiosk [8]. One franchise group saw shift work fall by more than 20 percent. Another chain cut labour hours across its outlets by nearly 12 percent [8]. 

The wage floor did not lift those workers so much as quietly saw off the bottom rung of the ladder they were standing on. 

This is not an argument that people should be paid less. It is an observation about what happens when the price of labour is set by decree rather than by what that labour can produce, and about who gets hurt when the two drift apart. It is never the people who set the number. 

What Baumol never saw coming 

For sixty years, cost disease was incurable precisely because you could not automate the quartet. The violinist was safe. So was the waiter, the till operator, the aged-care worker. Their inefficiency was their job security. 

AI is the first technology that credibly threatens that assumption, and it arrives at the exact moment the wage floor is climbing [9]. The jobs most exposed to a rising minimum (entry-level, routine, repeatable) are precisely the jobs AI is coming for first [9]. In California, the same franchises facing the higher wage bill were the ones rolling out ordering kiosks, app ordering and AI drive-throughs fastest.8 Raise the cost of the role and hand the employer a cheaper substitute in the same quarter, and you do not need an economics degree to see which way that goes. 

The 17-year-old looking for a first job is now competing not just with a higher wage bill, but with a piece of software that never calls in sick, never takes a smoko break, and never asks for a raise. 

Slicing versus baking 

Which brings us to November. 

Here is what the election will be about, and what it should be about, and they are not the same thing. 

Every party will campaign on how to slice the pie. Who pays more tax and who pays less. Who gets the transfer, the credit, the exemption. Where the floor should sit and how fast it should rise. It is a rich, noisy, deeply satisfying argument, and it will absorb the entire campaign. 

Almost nobody will campaign on baking a bigger pie. 

Yet the pie is the whole argument. A minimum wage is affordable when output is rising, because there is more to go round and the violinist gets paid out of the surplus. When output is flat, the same policy is not generosity. It is a redistribution of a pie that is not growing, and someone at the margin - usually the least skilled, the youngest, the last hired - pays for it without ever being told they are paying [10]. 

We even had a Productivity Commission. Set up in 2010 at ACT's insistence to ask precisely this question, it drifted - by the end it was inquiring into immigration settings and just transitions, and ACT itself abolished it in 2024, and nobody much mourned [11 The one body built to ask how we bake a bigger pie had spent its final years arguing about slices. That is the country in miniature. 

So here is the question worth putting to whoever knocks on your door between now and 7 November: not what will you lift, but what will you grow? What, specifically, will be more productive in three years than it is today, and how will you know? 

If the reply is a slogan, you have your answer. 

What this means for you 

If you own a business: stress-test your margins against a wage line that rises every April whether or not your revenue does. Automation is no longer an efficiency play. It is defensive. 

If you invest: sectors leaning hardest on minimum-wage labour - hospitality, retail, aged care - carry a structural cost risk that never shows up in a glossy prospectus. Price it in. 

If you are a parent: the entry-level job your kids would once have used to get a foot in the door is the one most at risk. Have a Plan B for how they build experience when the first rung keeps getting sawn off. 

The government can index its obligations every April and move on. Businesses cannot. 

They will tell you a rising tide lifts all boats. They never mention the ones still tied to the wharf. And every April, the tide comes in a little higher. The trouble is, the businesses are anchored, and the school-leavers cannot swim yet.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References 

  1. Baumol, W. J., and Bowen, W. G., Performing Arts: The Economic Dilemma: A Study of Problems Common to Theater, Opera, Music, and Dance, Twentieth Century Fund, 1966. 

  2. Beehive.govt.nz, Minimum Wage Increase Balances Business and Worker Needs, 12 December 2025; Employment New Zealand, Minimum Wage Is Increasing on 1 April 2026, 9 March 2026. 

  3. Stats NZ, Productivity Statistics: 1978–2025, 23 April 2026. 

  4. BERL, Relooking at Our Productivity Gap, 2024. 

  5. MBIE and MFAT, New Zealand's Productivity in a Changing World: Long-Term Insights Briefing, 17 December 2025. 

  6. Newsroom, Construction Sector Productivity Stuck in '80s, 9 August 2024; Beehive.govt.nz, Construction Sector Productivity the Same as 1985, 9 August 2024. 

  7. Clemens, J., Edwards, O., and Meer, J., “Did California's Fast Food Minimum Wage Reduce Employment?”, NBER Working Paper No. 34033, July 2025. 

  8. Owen, S., Ripley-Rodriguez, E., Jenkins, M., Walsh, S., and Tang, K., Let Them Eat Big Macs, Crunch Wraps, and Whoppers: A Working Paper Describing the Statewide Impact of California's $20 Fast Food Minimum Wage, University of California, Santa Cruz Institute for Social Transformation, November 2025. 

  9. IDC / Deel, AI at Work: The Role of AI in the Global Workforce, November 2025. 

  10. Stats NZ, Unemployment Rate at 5.3 Percent in the September 2025 Quarter, 5 November 2025. 

  11. New Zealand Government, New Zealand Productivity Commission Act Repeal Act 2024, New Zealand Legislation, 2024. 


We've Seen This SpaceX Movie Before

Article #469

Last month I warned readers: when the noise gets loud, ignore it; seek advice and wise counsel instead. 

The noise around SpaceX's IPO has been deafening. It priced at USD 135, ripped above USD 225 within days, and briefly made Elon Musk the world's first trillionaire on paper [1]. Then reality hit. 

I said the evidence favours patience. Let the froth settle before committing, like a freshly poured beer; you don't drink it while it's all head. 

Here's how it settled. SpaceX has crashed straight back to Earth through its own listing price. More than USD 1 trillion, around NZD 1.7 trillion, has been wiped from its value. From a June peak of USD 225 it closed at USD 114.92 on 6th August, below even its USD 135 listing price. Musk's paper fortune has fallen by more than USD 500 billion [1] [2] [3]. The company posted a consolidated net loss of USD 4.9 billion last year, swollen by its xAI acquisition, yet trades at more than 100 times sales [2].  

The analysts can’t even agree with one another. Bullish desks pinned targets north of USD 250; HSBC has just opened coverage at USD 115, roughly where it trades; Morningstar reckons fair value sits lower still [2] [3]. When the experts disagree by that margin, you’re not looking at analysis. You’re looking at a story, and stories are priced by mood. 

Around 23,000 Kiwis bought in to SpaceX through Sharesies, mostly in the after-market, well after the smart money had taken its seat [1]. By then, the offer-price allocation had happened offshore and the wild ride from USD 135 to USD 225 (and back) was well underway. Those who felt they were getting in early were, in truth, the exit liquidity for those who actually had. 

To those investors, I would gently say: none of this is new. 

USD 114.92 - SpaceX Closing Share Price on 6th August 2026

Buying for Blue Skies 

Our own market taught this very lesson just over a decade ago. You don’t need a crystal ball; only a memory.  

In 2014, listings came thick and fast. Travel-software firm Serko and measurement-device maker ikeGPS both floated at $1.10. Both quickly traded below their issue price, with ikeGPS down more than 18 percent on debut [4]. As one fund manager astutely put it: the market had been paying for blue sky three months earlier, and simply wasn't paying anymore [4]. The hype had outrun the businesses. Serko, to its credit, later found real success. Yet even now it trades below the heights the froth once implied, proving that even a ‘good’ company bought at a hyped price can still disappoint for years.  

It brings to mind something an old horse trainer once told me: “When they start, they've got the money and I've got the experience; when they leave, I've got their money and they've had the experience.” 

News articles on Serko and ikeGPS in 2014

The Quiet Opposite 

In the same 2014 rush, an old Hawke's Bay apple and logistics business called Scales came to market at $1.60, the very bottom of its indicative range, and had such a subdued debut it too slipped below its offer price in the first few days [5] [6]. No blue sky, no celebrity founders; just apples, coolstores, cargo, with about two-thirds of the business rooted right here in the Bay. Tellingly, the private equity seller kept a 20 percent cornerstone stake rather than bolting for the exit; skin left in the game, not cashed out at the top [6].  

IPOs floated by private equity usually attract scepticism, and the inevitable doubters lined up. They were wrong. Net profit came in some 87 percent above the float forecast, and shares today sit near record highs around $6, several times the issue price [7] The overlooked apple grower quietly outran the blue-sky darlings that had stolen the headlines on listing day. 

What separates the winners from the wreckage is simple: what you are buying, and who is selling and why. When insiders cash out at the peak, you are not the early investor. You are the exit. 

Scales YTD Share Price (December 2025 - August 2026)

The Devil in the Details 

There's a sting in the tail many day-one chasers never see coming. It’s buried in fine print, which as I always say, matters more than the selling price.  

New Zealand has no general capital gains tax, so most assume share profits are tax-free. Alas, not always. A “stag” buys a float purely to flip on the pop. Buy shares mainly to sell them, and Inland Revenue treats the gain as income, taxed at your rate, up to 39 percent. Buy to hold, and the same shares may not be taxed at all. Intention is everything [8]. Many who chased SpaceX bought the after-market and are now underwater. They’re carrying the flipper's tax intention without the flipper's profit, and are unable to offset the loss. 

There's a further wrinkle for anyone with a decent offshore holding. Once your overseas shares pass a cost threshold, proposed to double from NZD 50,000 to NZD 100,000 from the 2026–27 tax year, the foreign investment fund rules can tax a deemed slice of the value each year, whether or not you sold anything [9]. A newer method taxing only realised gains exists, but it is narrow and does not apply to ordinary listed shares like a US-listed SpaceX [9]. These settings are still working through Parliament and turn entirely on your circumstances. None of this is tax advice, but it is exactly the sort of thing you ought to check before you act. 

Choosing Patience over Hype 

Betting on a day-one pop with no real idea what you own is not investing; it is a coin toss with a tax bill. The alternative is not timidity, and the lesson is not anti-technology. High-growth tech can reward the patient, diversified investor handsomely. It is anti-hype. 

A disciplined, evidence-led approach can still be flexible and tactical, positioning around genuine opportunity when the evidence supports it, without chasing froth or mistaking a hyped listing for a considered decision. Scales was the quiet reward for buying a business; the blue-sky floats of Serko and ikeGPS were an expensive lesson in buying a story. SpaceX is that same lesson in a shiny new package. 

There is even a footnote of hope for the burned. Facebook fell more than 50 percent below its 2012 float price within four months, then clawed it all back within about fifteen as earnings caught up. A badly priced float can find a floor and recover in time… but that’s cold comfort to whoever paid top dollar on day one, and certainly no substitute for buying well in the first place [3] 

When the noise gets loud, the best investors don't chase the rocket. They read the audited accounts, understand who is selling and why, and let time and compounding do the work.  

In short: they seek advice and wise counsel. It may behoove others to consider doing the same.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


REFERENCES

1. NZ Herald / Newstalk ZB, "Share crash wipes $1.7 trillion from the value of Elon Musk’s SpaceX, crimps thousands of Kiwi investors" (July 2026) 

2. Yahoo Finance, "SpaceX Stock Just Violently Crashed Below Its Opening-Day Price" (July 2026) 

3. BeInCrypto, "SpaceX Stock Crash Wipes $500 Billion From Musk’s Fortune" (July 2026) 

4. NZ Herald, "ikeGPS plunge may show tech IPO party over" (July 2014) 

5. Scoop / BusinessDesk, "Scales shares edge lower on NZX debut" (25 July 2014) 

6. NZ Herald, "Scales shares set at bottom of range for IPO" (July 2014) 

7. NZ Herald / Direct Capital, "Scales’ Golden Apples"; Stockopedia SCL share data (2026) 

8. Inland Revenue, "Share investments": ird.govt.nz 

9. Inland Revenue Tax Policy, "Foreign investment fund changes" information sheet (May 2026); Budget 2026 FIF threshold proposal 


Wholesale Investor Rules: Calling a Cat a Fish

Article #468

Abraham Lincoln liked to ask how many legs a dog has if you count the tail as one. Four, he said: calling the tail a leg doesn’t make it a leg. New Zealand’s wholesale investor rules have spent a decade calling tails legs. Last week a Christchurch courtroom finally counted.

On Friday 24 July the High Court placed six companies in Bernard Whimp’s Chance Voight group into liquidation. Associate Judge Dale Lester found a pattern of obfuscation, incompetence and evasion, an entirely unsustainable model, and a scheme that could only pay existing investors by finding new ones. Founded in 2021, the group had raised more than $54 million from perhaps 230 people to pour into property-based wholesale debt promising returns of 10 to 13 per cent a year. By September 2025 it sat on a negative net asset position of $11.8 million. The evidence, the judge said, was overwhelming.

One detail is almost too good. Whimp asked the court to delay the hearing until he could unlock money from his late father’s estate, which, he said, would in turn fund a $110 million land development. The judge was unmoved, calling the request a microcosm of how the whole group had been run. Quite. You cannot conjure a solvent business from a deceased estate any more than you can pull a rabbit from an empty hat, though plenty have tried. Meanwhile a related Whimp entity had drawn some $9.2 million in “management fees”, around 24 per cent of all money invested, even as the group booked a $5.5 million trading loss in a single half-year. Fees, in other words, for failure.

Here is what should trouble every reader. Chance Voight’s investors were, in the main, aged 65 and over, and the first liquidators’ report found many had only a limited grasp of the risks. Yet each had been certified a “wholesale” investor: sophisticated enough, in law, to need no protection at all.

You can call a cat a fish, but you can’t teach it to swim.

The mechanism is simple. The Financial Markets Conduct Act lets companies raise money without disclosure, licensing or supervision, provided the investors are wholesale. Under the “eligible investor” rule, anyone can claim that badge so long as a financial adviser, chartered accountant or lawyer signs to agree. Tick the box, and every retail protection evaporates. And this was no discreet, professional affair: the court noted Chance Voight was marketed in regional and local newspapers, on Facebook and at in-person promotional events, the mass channels of the retail world, not the closed room of the true professional.

A long process for a too-low bar 

The regulator has been uneasy for years. When the FMA took a test case to force issuers to verify the investors sent their way, it lost: Justice Fitzgerald found the permissive regime was a feature of the law, not a bug. But she put her finger on the fault. The problem, she observed, was not so much the content of the certificates as that certificates with patently defective grounds, or none at all, were being confirmed regardless. It is the confirmation process that is falling down; and if it cannot protect investors, the balance struck in the legislation may need resetting, a matter, she said, for Parliament and not the court.

That was the judiciary handing the problem to the politicians. This month, at last, they picked it up. Commerce Minister Cameron Brewer has released an MBIE consultation, part two of the plan to lift our capital markets, that concedes what advisers have muttered for years: our settings are an international outlier, “unique” and “relatively permissive,” with “some evidence” that inexperienced investors are getting into wholesale offers. Its options read like a reply to Fitzgerald: a more objective eligibility test, a cap on how much an eligible investor can put at risk, a requirement that applicants take independent financial advice, restrictions on wholesale advertising, and, squarely, real onus on the professional confirmer, with an infringement offence for inadequate certifications.

Click above to read more on Wholesale Investors from the Financial Markets Authority

What still needs attention 

Those are the right levers, and they should be pulled. None of this is an argument for tearing the regime down. Genuine sophisticated investors exist, and raising capital from them without the full disclosure burden is a legitimate and valuable part of a working market. MBIE rightly notes that certificates lasting only two years already make life needlessly costly for real professionals. The point is narrower. The bar has been set too low, left to rot, and waved through by people with every incentive not to look too closely. Consider that none of the thresholds, $5 million in net assets, a million-dollar investment history, a $750,000 minimum subscription, has been adjusted for inflation since the Act took effect in 2013. Thirteen years of asset-price growth, house prices above all, has done the widening for Parliament: the same numbers now capture people they were never meant to reach. The bar did not get more generous; the country simply ran up more nominal dollars against a line that never moved. Last year the FMA referred 22 accountants and eight lawyers to their professional bodies over the misuse of these very certificates.

Two gaps deserve more than the paper gives them.

The first is the advice layer. A retail adviser must put the client’s interests first and prove a recommendation is suitable: goals, cash flow and appetite for risk, all understood and documented, the file running to fifty pages. A wholesale-only adviser owes a bare statutory duty to give priority to the client’s interests, but needs no FMA licence, follows no Code of Professional Conduct, and never has to establish that the advice was suitable. The relationship can be purely transactional: take the $5 million, place it in a syndicate, move on. If you think professional advice is expensive, try the amateur variety.

The second is the Crown’s own hand. Of the roughly 70 managed funds on Invest NZ’s “acceptable” list for Active Investor Plus migrants, against nearly $1.5 billion of committed capital, all but a handful are wholesale, and few are household names. Invest NZ’s own disclaimer states that inclusion is not an endorsement or recommendation by it or the Government. We invite wealthy newcomers to make this country home, steer them onto a state-curated list, then wash our hands of what follows. All care, no responsibility. A wealthy migrant, a surgeon, a farmer, someone who simply inherited well, may know nothing of geared, illiquid property debt, yet is stamped “wholesale” on a net-asset figure alone. Funds on a Crown list should answer to retail-grade disclosure, not hide behind the wholesale tag.

Underneath it all sits a regulator half in the dark. The IMF warned back in 2017 that there was insufficient data to assess the risks in our wholesale sector; nine years on, the FMA has admitted it still has very little sense of the size, structure or practices of that market. You cannot police what you have never measured.

Two centuries ago the little port of Kōrorareka, on the same Bay of Islands coast that cradled New Zealand’s first capital, was infamous as the Hell Hole of the Pacific, a settlement beyond the reach of any law. We renamed it Russell, gentrified it, and told ourselves the lawlessness was history. But a regime that lets an operator gather tens of millions from retirees on a one-page certificate nobody properly checks, through advisers who owe them little and a regulator the courts say owes them nothing, has not left the frontier behind. One judge has wound the companies up. Another has told Parliament what to fix. Submissions close on 25 August. Make sure the reform closes the loophole, rather than merely repaints the saloon.*

* Stewart Group does not provide advice to investors under the wholesale investor rules. We took that decision years ago, in the view that all investors deserve full disclosure and a fiduciary relationship. 


Further Reading: For those interested in the wholesale investor discussion, this guide provides a practical overview of the key differences between retail and wholesale investors, including eligibility criteria, investor protections and regulatory requirements.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


REFERENCES

1. “Court slams Whimp entities into liquidation; Kerr bankrupted in the UK.” David Chaplin, Investment News NZ, 26 July 2026.

2. “‘Unsustainable’ Chance Voight companies put into liquidation.” NBR, 24 July 2026 — judgment of Associate Judge Dale Lester; Teneo’s John Fisk, Lara Bennett and Malcolm Hollis appointed liquidators; comments of FMA enforcement head Margot Gatland.

3. David Chaplin, “Wholesale investment: there’s a hole in the market.” BusinessDesk, 21 July 2026.

4. “Government looking at wholesale investor loophole.” Good Returns, 17 July 2026; “Government seeks feedback on loophole exposing unsavvy investors to risky deals.” NZ Herald, July 2026.

5. Ministry of Business, Innovation and Employment, capital markets reform discussion paper (part two), July 2026. Submissions close 25 August 2026.

6. First interim liquidators’ report on the Chance Voight group (PwC), 2026 — investor age profile and limited risk understanding; “management fees” of $9.2m, some 24% of funds invested; $5.5m half-year trading loss; negative net assets of $11.8m at 30 September 2025.

7. Financial Markets Authority, [2025] NZHC 2723 — judgment of Fitzgerald J (18 September 2025) on the confirmation process and the balance struck in the legislation.

8. Financial Markets Authority — referral of 22 accountants and eight lawyers to their professional bodies over misuse of eligible investor certificates.

9. International Monetary Fund, Financial Sector Assessment Programme, New Zealand, 2017; FMA review of custody arrangements, 2026.

10. Invest New Zealand / Immigration New Zealand, Active Investor Plus visa: list of acceptable managed investment schemes and non-endorsement disclaimer.

11. Financial Markets Conduct Act 2013, Part 3 and Schedule 1.

12. “Kōrorareka — the Hell Hole of the Pacific.” Te Ara / NZ History, Ministry for Culture and Heritage.


Wise Counsel of a Palliative Care Nurse: Living an Authentic Life

Article #467

Australian palliative care nurse Bronnie Ware spent eight years at the bedside of the dying, sitting with people through the last weeks of their lives. She recorded what she heard; first in a 2009 blog post, later in a book read by millions in more than 30 languages. The most common regret? "I wish I'd had the courage to live a life true to myself, not the life others expected of me."

As someone who has spent decades stewarding Hawke's Bay families through business succession and long-term planning, it’s a familiar refrain. We build empires of assets, careers and obligations, and somewhere along the way we drift from the authentic life we once envisioned.

The dying don't speak of missed promotions, bigger houses or the perfect investment return. They speak of roads not taken because they followed someone else's script - years spent chasing approval from parents, peers and society, or the expectations that attach themselves to a "successful" professional life. In our community and line of work, that pressure is real. Family businesses carry generational weight. Clients arrive burdened with keeping up appearances, maintaining the farm, the firm, or the lifestyle their circle demands.

Ware had a patient called Grace. Grace felt pressured to remain in an unhappy marriage; when freedom finally arrived, terminal illness arrived with it. She regretted not finding the courage sooner. It’s not so different to tales of the local farmer who poured decades into the land his father expected him to inherit, and never pursued the enterprise he truly dreamed of. Authenticity isn't rebellion for its own sake. It is the quiet courage to choose what endures.

Ware’s patients often realised too late that even close family members had little idea of their innermost dreams. The same disconnect can appear in professional relationships. Many assume their advisers fully understand their plans and values – typically, that isn't the case. It’s one thing to know a client's balance sheet, and quite another to know what they are building it for.

“I wish I hadn’t worked so hard.”

According to Ware, this second came from every male patient she nursed. They missed their children's youth and their partner's companionship. We tell ourselves the long hours are for the family, the security, the future. Yet when time is running low, we realise time itself is the one asset we cannot replenish or reallocate.

Here in Hawke's Bay – after cyclones, economic pressures and rates burdens – many of us have doubled down on work as a form of control. But true stewardship requires balance. Succession planning isn't as simple as handing over the keys. It's ensuring the next generation inherits not just wealth, but the example of a life well-lived. My own son’s interest in commerce is encouraging, yet he needs space to find his own path, including time overseas, before stepping into any role. The same goes for our daughter as she gains independence.

"I wish I'd had the courage to express my feelings."

Many of Ware’s patients had suppressed their feelings simply to keep the peace, settling for an existence they didn’t love as a result. In family enterprises and marriages alike, unspoken truths fester. Those who found peace reconciled old hurts while there was still time. The same holds in teams, partnerships and advisory relationships: address misalignments early, not once the damage is done.

“Friends slip away.”

Ware recalled a patient called Doris, all alone in a nursing home with her daughter living far away. Ware tracked down an old friend and arranged a phone call - it lifted Doris's spirits in her final days. Busy lives and distance make friendship easy to neglect, yet old mates anchor us. In our Scottish-heritage household, with its Royal Stewart tartan, we see the value of connection. The same applies in business: relationships built on trust and shared values outlast any transactional deal.

“I wish that I had let myself be happier.”

Happiness wasn't something that happened to them; it was a choice they postponed, waiting for the perfect conditions - retirement, the next milestone, the kids leaving home - only to find joy lives in ordinary moments and the gratitude for health while it lasts. As one of the sayings I live by puts it: if you think wellness is expensive, try illness.

It's amazing how many people can tell you the market numbers and bond ratings, but can't tell you their cholesterol or their calcium heart score.

The lessons we can apply in financial planning

This aligns with what we observe in sound financial planning. The best portfolios aren't those chasing the highest returns at all costs, but those built on disciplined, values-aligned decisions that weather volatility. The same holds for a life. Authenticity compounds. When your daily actions reflect your core beliefs around integrity, family, community, stewardship - regret finds little room to grow. Decisions get easier.

We are, ultimately, in the goal-achievement business. What use is beating the market if you achieve none of your goals?

None of this means abandoning responsibility. It’s quite the opposite: living authentically demands discipline. It requires clear priorities, the courage to say no, and planning for money and time to serve your goals rather than dictating them. It means protecting family time as fiercely as you protect the balance sheet – and mentoring the next generation not just in business acumen, but in character.

If someone in your advisory circle doesn't gel with your plans and values, it's okay to stop the bus and let them off. There's always another person who shares your vision and will carry it forward. I could sit comfortably and avoid telling clients what they don't want to hear, but that isn't the job. Our fiduciary responsibility is to lead, and to speak the unspoken truth.

As we navigate an uncertain world - policy shifts, economic headwinds, rates and infrastructure - the palliative nurse's counsel offers a north star. Build wealth, yes. Grow the enterprise, absolutely. But never at the expense of the life you were meant to lead.

The good news is we don't need a terminal diagnosis to change course. Start today. Revisit what truly matters to you and your whānau. Have you ever had a genuinely authentic discussion with your advisers - one about your values, not just your numbers? Surround yourself with like-minded folk who will carry your ideals forward long after you've gone: trusted trustees, key team members and professional stewards who understand the bigger picture.

In the end, true success isn't measured in dollars or status. It's measured in a life lived true to yourself - with courage, presence and heart. Often, Ward’s patients understood this only when it was too late. The living can seek wise counsel while they still have the time to act on it.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


REFERENCES

  • Bronnie Ware, The Top Five Regrets of the Dying: A Life Transformed by the Dearly Departing (2011); originally the 2009 blog post "Regrets of the Dying," bronnieware.com

  • The Top Five Regrets of the Dying review, National Center for Biotechnology Information (PMC), pmc.ncbi.nlm.nih.gov

  • "No Regrets" interview with Bronnie Ware, Mindful, mindful.org

  • Shortform book guide, The Top Five Regrets of the Dying, shortform.com


When the Process Becomes the Cover

Article #466

Two stories crossed my desk last month, half a world apart, joined by the same affliction: institutions so wedded to their own process that they lose sight of the people it should serve, and then reach for that process as a shield. The pattern is worth naming, because it is far more common than outright wrongdoing and far harder to spot. Nobody sets out to fail. They simply follow the steps, tick the boxes, and assume the machine will catch what they did not.

Our first story comes courtesy of former MP Rick Barker. Starbucks South Korea launched a promotion for “Tank Day” on 18 May, the anniversary of the 1980 Gwangju massacre, when the military rolled tanks over pro-democracy protesters and killed hundreds [1].

It did not land well.

The Korea CEO was sacked and weekly sales fell more than a quarter [2]. What makes the episode instructive is not that a mistake was made, but how it was made. Reports suggest the marketing team asked an AI tool for suggestions, the approving officials never opened the design file, and the legal review was skipped entirely [3]. Every gate that should have stopped it was either delegated or waved through. Not malice, but blindness – the particular blindness of people who trusted the process to do their looking for them.

In story two, we return to Hastings. Council consulted on an Annual Plan offering a 5.9 or 9.1 percent rates rise, and businesses across the district budgeted accordingly [4]. Then Quotable Value’s revaluation landed. Commercial and industrial land values had risen sharply while residential values fell close to 20 percent. Because rates are apportioned by property value, that swing shifted a far larger share of the burden onto commercial owners – not through any decision to target them, but as an automatic consequence of the arithmetic. One inner-city operator told the Herald his rates were jumping almost 30 percent, a rise he believed could end his business [4]. The certified figures arrived only two working days before submissions closed, creating an extremely limited window for the very people most affected to respond.

The official line was that Council did not have the numbers until early May. Under questioning, that account became more complicated. The mayor acknowledged she had received an indication that there could be a significant shift [5]. A councillor has since stated that officers held a pre-audit valuation report in February and March showing commercial values rising and residential values falling, yet ratepayers were given no warning [6]. The distinction matters. There is a difference between not having a certified, audited, signed-off figure and having no idea at all which way the wind was blowing.

That admission raises a fair question: whether earlier, plainer communication could have helped affected ratepayers prepare, even without the final numbers in hand. You do not need certified figures to the last decimal to tell a café owner a storm may be coming. Not knowing the final number is not the same as knowing nothing. A warning that a material shift was likely – caveated, provisional, honest about its uncertainty – would have cost the Council nothing and given businesses time to plan, to model their exposure, to organise a considered submission rather than a scramble.

Then, after a second round of consultation and 233 submissions seeking relief, Council retained the differentials in full and deferred the rating review to the 2027 Long Term Plan [7]. A pause on the Hastings CBD targeted rate was offered as the consolation; Havelock North businesses did not receive the same relief [7]. And the decision was posted immediately before a long weekend – a timing that, whatever the intention behind it, did little to foster the perception of an open and confident process. Institutions that are proud of a decision tend to announce it in daylight.

With amalgamation now looming [8], the deferral carries a further risk. A review pushed out to a future Long Term Plan may ultimately be inherited by an entity that never made the promise. A commitment made by one council to revisit its rating approach is only as durable as that council; restructure the furniture and the promise can quietly fall down the back of it.

There was, it turns out, an alternative on the table. A councillor had proposed a different differential before consultation opened, one that eased the commercial burden while nudging the rural villages toward parity. He and four colleagues voted against the status quo; ten voted to retain it. His alternative could not proceed, he says, because the modelling had not been completed [6]. Whatever the merits of his particular proposal, the sequence is telling: an option existed, and the process – not a debate on its substance – was the reason it went no further. When process appears to foreclose the consideration of alternatives rather than enable it, confidence in the process itself begins to suffer.

Let me be clear about what this is and is not. The rates were never the real issue. Revaluations happen; they are an independent statutory exercise the Council does not control, and this one at least spared many households the worst by loading the swing onto commercial property instead. The more significant issue is confidence in the process that surrounds the numbers: whether people were given timely information, whether options were genuinely explored, and whether the concerns of those affected received meaningful consideration before the die was cast.

Starbucks lost a quarter of its sales because nobody thought to examine the impact of what they were about to do. Hastings’ ratepayers risk losing something slower to rebuild: the confidence that important information will be shared with them while there is still time to act on it. Trust is the one asset a council cannot borrow against. It does not appear on any balance sheet, it cannot be levied, and once it is spent it cannot be refinanced.

As Hawke’s Bay considers significant structural change through possible amalgamation, the lesson extends well beyond one year’s rates. Public institutions do not earn trust because every decision they make is popular – that is an impossible standard and not a sensible one. They earn it when people feel informed, heard and treated fairly throughout the process, win or lose. Consultation, transparency and candour are not administrative box-ticking to be completed and filed; they are the foundation upon which public confidence actually rests. Once that confidence begins to erode, rebuilding it is far harder, and far more expensive, than preserving it in the first place. That is a lesson worth learning before the machinery of local government is rebuilt, not after.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


REFERENCES

  1. “Starbucks Apologizes After Ad Campaign Evokes Massacre,” Associated Press, May 2026; Branding in Asia, “Shinsegae Chairman Issues Apology Over Starbucks Korea ‘Tank Day’ Campaign,” May 2026.

  2. “Starbucks’ Korea sales plunge after Tank Day marketing backlash,” Reuters, May 2026; CEO Sohn Jeong-hyun dismissed per CNN.

  3. “Foreign Media Spotlight Starbucks Korea’s ‘Tank Day’ Backlash and Sales Plunge,” Seoul Economic Daily / Yonhap, 27 May 2026.

  4. “Hastings business says rate hike of almost 30% could end them, mayor ‘beyond livid’ with situation,” NZ Herald / Hawke’s Bay Today, June 2026.

  5. Public meeting convened by the Hastings and Havelock North Business Associations, 4 June 2026.

  6. Cr Steve Gibson, public statement on the 2026/27 Annual Plan decision, July 2026: pre-audit valuation report in February/March, 25–75 percent impact estimate, alternative rating differential proposal, and 10–5 vote to retain the existing differentials. Facebook.

  7. “Council adopts 2026/27 Annual Plan,” Hastings District Council, July 2026 (differentials retained; rating review deferred to the 2027 Long Term Plan; Hastings CBD targeted rate pause).

  8. “Majority of Hawke’s Bay submitters favour amalgamation into one council,” Hawke’s Bay Today, 14 July 2026.


The Walls That Fall: What Hadrian Teaches Us about a Financial Plan

Article #465

Hadrian's Wall has fascinated me since I was a kid. As you read this, I will have just finished cycling part of it with my family and a good friend who’s also a client.

It’s the kind of trip where you spend your evenings in a pub working out the next day's ride, and your days quietly humbled by what people built two thousand years ago. I've been reading up on the wall for months, as one does before such a trip. And - hazard of the job - the more I read, more I noticed a story that financial advisers, and the people who rely on them, should pay attention to.

The Wall, as it stood

Hadrian's Wall was begun in AD 122 under the emperor of the same name. It ran 73 miles coast to coast, from Wallsend on the River Tyne in the east to Bowness-on-Solway in the west. Around 15 feet high, originally 10 feet thick (later narrowed to 8 in places to speed construction), fronted by a wide ditch, with a fortlet known as a milecastle every Roman mile, and two observation turrets in between each one. It took the legions roughly six years to build, and it was manned in some form for nearly three centuries.

To put the scale of it in New Zealand terms: Picture a stone wall from Tauranga to Raglan. Every mile of it manned, every milecastle stocked, every turret garrisoned, around the clock. Then think about how hard it has proved in modern times to commit to a second Auckland Harbour crossing. Decades of debate, billions in costings, and we still haven't put a spade in the ground for what is essentially a few kilometres of road and tunnel.

The Romans put up that wall in six years and manned it for nearly three centuries. The quantum of capital, the legionary labour, the supply lines, the stone, the timber, the ongoing garrison: it boggles the mind. It was the state of the art. The frontier, literally and figuratively, of what was possible.

But, that’s not the part I found most instructive. This is.

The upgrade that didn't hold

When Hadrian died in AD 138, his successor Antoninus Pius made a different call.

He decided the wall wasn't enough, or wasn't far enough north, and he pushed the frontier deeper into what is now central Scotland. He ordered a new wall built between the Firth of Forth and the Clyde, on the orders of his governor Quintus Lollius Urbicus. The Antonine Wall, as we now call it, was 39 miles of turf on a stone base. It had 16 forts and a road called the Military Way running behind it. It was the next-generation solution. The bold reposition. The upgrade.

It was also abandoned within about a generation.

The legions pulled back to Hadrian's Wall. The Antonine Wall, the most ambitious frontier project of its day, became a curiosity in the Scottish landscape.

Two of the most expensive military engineering projects of the ancient world. Both built by the best engineers of their age. Both, in their way, overtaken by circumstance. We use neither Antionine nor Hadrian’s Wall in this modern age. We don’t need to.

The parallel

Reading about this, I couldn’t help but think of when I sit down with people who tell me their financial plan is bulletproof.

The plan is usually built around a single conviction. A favoured stock that has done well for the last decade. A fund the adviser recommended at a long lunch in 2019. A single asset class, often residential property, sometimes a concentrated equity portfolio. The numbers add up on a spreadsheet. The projections look tidy. The client signs off and feels secure.

It’s state of the art... for its day.

The trouble is that any day eventually ends. Markets shift, and they shift in ways that are obvious only in hindsight. Sectors that looked unassailable five years ago are nursing real wounds now.

The growing effectiveness of AI is reshaping how per-seat software businesses get valued, because if one person and an agent can do the work of nine, the per-seat model starts looking thin. GLP-1 drugs are reshaping assumptions about big pharma earnings. The post-Covid environment has changed everything from vaccination rates to office occupancy to commodity flows. Plenty of concentrated bets that looked clever in 2021 are no longer looking quite so clever in 2026.

The wall that was bold and bulletproof becomes a museum piece, and very often the people standing inside it are the last to notice.

What the Romans got right and what they got wrong

The Romans weren't stupid. They were the best engineers of their age, and Hadrian's Wall is, in its own right, an extraordinary achievement. It didn't fail because the design was poor. It became irrelevant because the world around it changed: the politics of Rome, threats to the Empire, economics. The circumstances that called for the Wall no longer existed.

Walls, by their nature, do not change.

Plans, by their nature, should.

This is the thing I keep coming back to: A good financial plan isn't a wall. It's a garrison. It must be broadly spread, regularly reviewed, regularly rotated, grounded in the evidence rather than in one manager's conviction about the next big thing. The factors that drove returns in the last cycle are not the factors that will drive them in the next. Tax settings, the regulatory landscape your family, your goals – the world changes with time. A plan that doesn't change with them isn't a plan; it's a monument, and a fairly expensive one at that.

For savvy investors, the discipline isn't picking the right wall once. It's seeking wise counsel often enough that you notice when the frontier has shifted, and you can adjust before you find yourself defending ground that no longer matters.

This is also why we are an evidence-based firm. We don't try to pick the next winning stock or guess which active manager will sit in the top quartile in five years' time, because the academic record on that is settled and it isn't kind. Most active managers don't beat their benchmark over long periods. The few who do can't reliably be picked in advance. The path that has actually compounded for clients over the decades is something far less glamorous: broad diversification, disciplined exposure to the factors that drive long-term returns, low costs, and the patience to stay the course. We use Dimensional funds for that reason. The foundation is fifty years of academic research, not someone's conviction about the next big thing.

In practice, the work is unglamorous. It's an annual review with hard questions of last year's plan. It's rebalancing when a position has run further than the strategy intended. It's saying no to the new shiny thing because it doesn't fit the wider picture. It's sitting down again when life changes, because the plan needs to change with it. None of it makes a great story at a barbecue. All of it compounds quietly, and it is the whole point.

Fifty years in

So I've been out there this week, marking my 50th; watching the moors roll past and thinking about the Roman soldiers who walked that wall for 300 years and the ones who walked away from the Antonine Wall after thirty. And thinking, with gratitude, about the clients we've walked alongside over the years. The conversations that have moved plans forward, the times we've changed direction together, and the times we've held firm.

The world keeps moving. The job is to move with it, thoughtfully, with discipline, and with help.

Here's to the next fifty.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz

  • We do not hold or advise on any private credit or private equity investments.


REFERENCES

  1. English Heritage, "History of Hadrian's Wall", english-heritage.org.uk

  2. Britannica, "Hadrian's Wall" and "Antonine Wall" entries, britannica.com

  3. Historic Environment Scotland, "Antonine Wall", historicenvironment.scot

  4. North East Museums (Segedunum Roman Fort), "The building and development of Hadrian's Wall", northeastmuseums.org.uk

  5. World History Encyclopedia, "Hadrian's Wall" and "Antonine Wall", worldhistory.org

  6. UNESCO World Heritage listings, Frontiers of the Roman Empire (Hadrian's Wall designated 1987; Antonine Wall designated 2008)

  7. Bede, Ecclesiastical History of the English People (8th century), early historical description of Hadrian's Wall as "eight feet in breadth, and twelve in height"


Scotland the Brave - The Darien Scheme That Worked

Feature Article


A Canny View reader asked an excellent question after last month's column: what was the alternative? What would have happened if the Darien project had been successful?

Whilst I don't hold myself out to be a historian, I do find alternative history enjoyable reading, with its endless what-ifs.

Last month's piece (If you missed it, read here) took up Scotland's catastrophic 1698 bet on a trading colony in Panama, the one that bankrupted the nation and led, within a decade, to its loss of sovereignty to England. The lesson, plainly, was about concentration risk: bet a fifth of your wealth on one thing, and you had better be ready for the day it doesn't work.

But what if it had worked? Indulge me a moment.

It is 1698. William Paterson's vision holds. Disease is mastered through better drainage and stricter quarantine. The Spanish, having sized up Caledonia's defences, choose negotiation over assault. The English, sensing they cannot beat the Scots to the Isthmus, partner instead of obstruct.

Within a decade, Caledonia is the trading hub of the Americas. Goods from Canton and Manila are landed on the Atlantic side, hauled across a few miles of jungle, and reloaded onto ships bound for Edinburgh and Amsterdam. The Company of Scotland pays a 40% dividend in 1710. It pays one again in 1715.

Scotland enters the 18th century rich. There is no bankruptcy. No loss of sovereignty. Edinburgh, not London, becomes northern Europe's financial centre. Adam Smith, born in 1723, writes The Wealth of Nations in a country that does not need to borrow England's economic theory; it has its own.

The story doesn't stop there. The Acts of Union, in our real history, were the price Scotland paid for the Darien bankruptcy. Take the bankruptcy away, and the union never happens. So when Queen Anne dies in 1714 and the English Parliament invites George of Hanover to take the throne, the Scottish Parliament is free to make its own choice, and reaffirms the Stuart line. James Francis Edward becomes James VIII of Scotland. His son Charles Edward never has to invade in 1745, because his father is already sitting in Edinburgh.

Which means no Battle of Culloden in 1746. No Disarming Act. No proscription of Highland dress, no systematic dismantling of clan structures. Which means no Highland Clearances. Which means the great Scottish diaspora of the 19th century, the one that founded Dunedin in 1848 and put Scottish names on half the farms in Hawke's Bay, never happens, or happens at a fraction of the scale.

A successful Darien does not just save Scotland's sovereignty. It rewrites the demographic map of New Zealand.

And by the late 19th century, when the world's powers turn their attention to cutting a canal through the Isthmus, the Scots have been there for two hundred years. They have the local knowledge, the capital, and the political will. The canal opens, somewhere between 1890 and 1905, under Scottish ownership. One of the world's great chokepoints, the gate between the Atlantic and the Pacific, is not American. It is Scottish.

Speaking for myself, I highly doubt either my maternal or paternal ancestors would have made the journey from Perthshire, Scotland.

Paterson gets a statue on Princes Street. And every Scot who didn't subscribe is haunted, for the rest of their life, by what they missed.

This is the harder lesson.

The bet that pays off gets remembered as vision. The same bet that fails gets remembered as folly. The two bets were identical.

Imagine two funds in 2020. Both concentrate. Both bet on a small basket of high-conviction names. Five years later, one is celebrated as a genius and the other is torn apart in print. The portfolios looked identical at the start. The strategies were the same. What differed was which way the dice landed.

This is survivorship bias, and it is the great mischief-maker of finance. We study Buffett, not the thousand value managers who concentrated and lost. We celebrate the founder who bet the company and won, not the ten who bet and quietly disappeared. The lesson taught is that conviction beats prudence. The lesson untaught is that survival beats both.

When concentration works, you don't learn the right thing. You learn that the rules don't apply to you, and you bet bigger next time. The next Darien is always larger than the last.

What does this mean for a Canny investor at the kitchen table?

It means diversification is not, as the fund manager class sometimes implies, a strategy for the meek. It is the structure that lets you stay in the game on the day the dice land wrong. And sooner or later, they will.

The business owner whose company is 80% of their wealth is not bold; they are exposed. The retiree leveraged into a single Hawke's Bay property is not bold; they are exposed. The investor who has refused to trim a winner that now dominates the portfolio is not bold; they have simply been right so far. That is all.

The Scots who didn't subscribe in 1698 missed a fortune in the world I just imagined. In the world we actually got, they kept theirs.

Across enough rolls of the dice, the second outcome is the one that matters. The first is the one you read about.

We always enjoy the dialogue with our Canny View followers, so please keep up the great feedback, and we'll do our best to accommodate.

Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


Turning Fifty: The Inflection Point

Article #464

I turned 50 on the second of July. That includes nearly 30 in the workforce, 26 years as a financial adviser, 20 as a husband and 18 as a father. Do the maths and I'm roughly two-thirds through my optimal earning window, if we call 65 the end of the innings. It’s made me stop and do the thing I always ask of clients: take an honest look at where I am now, and where the next 15 years are heading.

Most of us never think about the shape of our earning life, but it follows a pattern. The 20s are for learning a trade, finding your feet in a profession, perhaps marrying, often still paying off the student loan. The 30s bring children, a mortgage and the long grind of deepening a career. By the 40s the income finally lifts and a little pressure comes off. Then the 50s and 60s arrive, and many people start thinking about the golden years to come. Here’s the rub: a fit and healthy 65-year-old has not just finished their best earning years; for many, the earning stream has stopped altogether. The way we’re living these days, those earnings now need to carry us all the way through to our 90s. That’s three decades of withdrawals from a jar you stopped filling, so you need to put a lot of cookies in that jar to sustain yourself for 30 years.

For most of human existence, 50 was the end of the road. In 1900, life expectancy for men in New Zealand sat in the late fifties [1]. A man of 50 in those days really was winding down, because he was nearly done. The Victorians built their whole idea of a life stage around it - you worked until your body gave out, and the gap between the two was mercifully short. Today, a healthy 50-year-old can reasonably expect another 35 years or more, and an increasing number of us will see ninety [1]. We’ve held on to the old instinct that 50 is the beginning of the end, while living an entirely different reality. The body tells us we have arrived. The maths tells us we are barely halfway.

Source data: New Zealand cohort life tables: March 2025 update | Stats NZ

This is where I see good people stumble, though rarely through recklessness. The kids are nearly gone, the mortgage is finally in retreat, and “finally” becomes the word of the moment. Finally, we can do a few things for ourselves! The bucket list, the holidays, the trips deferred for 20 years while school fees and braces and first cars ate every spare dollar. It feels earned, and it feels good, because it is and it does. Behavioural research calls this ‘present bias’; a hard-wired habit of overweighting the reward we can have today against the one we must wait for [2]. But that freed-up cash flow is being enjoyed at the precise moment it should be doing its hardest work. The next 15 years from 50 are prime accumulation time, not the victory lap people imagine them to be.

Most balance sheets tend to be the same at 50: top-heavy with lifestyle assets. The house, the cars, the bach with its rates, maintenance and insurance quietly eroding spare cash or savings each year. It has been the Kiwi dream for as long as I can remember, and there is nothing wrong with wanting that dream. But while the numbers look perfectly reasonable on the surface, the cash flow underneath is poor. The assets that produce real income and liquidity - the ones that will still pay you when your salary stops - are too small to move the needle in this scenario. You’re carrying a great deal of weight that does not work for you, and worse – it's costing you to hold it.

This is where knowing values is crucial. At 50, you need to be clear on what matters and what you must build over the next fifteen years – because every goal is built on cash flow, and cash flow comes from the assets you have accumulated. Get the values right and the rest follows in a straight line. Leave them vague and you’ll inevitably keep spending on what feels good now, instead of what carries you through your 70s, 80s and 90s. The order in which your returns arrive in the early retirement years can make or break a 30-year drawdown, and a poor first few years while you are drawing down does damage that a good average return never quite repairs [3].

It can feel uncomfortable to take such a frank look at your present and future, but it’s fairly straightforward. Do your lifestyle assets fit what you are trying to build? Are you protecting your peak earning stream as the engine that funds everything else? Is your cash flow working backwards, servicing debt on things that do not compound, or forwards, building assets that do?

The gap between what New Zealanders expect to retire on and what they have set aside remains stubbornly wide. It widens fastest for those who assume there is still plenty of time [4]. At 50, most people can still materially change their later years by engaging and making a few incremental course adjustments. These changes don’t have to be dramatic, but they do need to be early. A small correction to a flight path early in the journey lands you in a completely different place.

Often, the best co-pilot on such a journey is a professional financial advisor. And if you think professional advice is expensive, try using an amateur – see what it costs you. Unfortunately, the most expensive amateur you can ever hire is usually yourself; timing the market with optimism and a spreadsheet doesn’t tend to get the same results as methodical, proven strategies and a steady pair of hands at the wheel. Time in the market is the one advantage you cannot buy back later at any price [5].

This is the fiduciary truth of it, and it is the part I care about most after 26 years. Seeking wise counsel at 50 is not an admission of weakness. It’s the best way to understand your own position; we’re all the worst judges of our own blind spots, but an unbiased third party can see the whole scene with clarity.

A good adviser is not there to take the holidays away. They are there to make sure the holidays at 70 are still possible.

50 is the inflection point where you can still move the dial in a way you simply cannot at 65. The runway is shorter than it was, but you’ve got a good bit of tarmac left before earnings come to a stop. The question is not whether the time for preparation has passed (it hasn’t), but whether you will use what remains of it. A burden shared is a burden halved.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz

  • We do not hold or advise on any private credit or private equity investments.


REFERENCES

  1. Stats NZ. (n.d.). Life expectancy. https://www.stats.govt.nz/information-releases/new-zealand-cohort-life-tables-march-2025-update/

  2. ScienceInsights. (n.d.). What is present bias? How it shapes your decisions. https://scienceinsights.org/what-is-present-bias-how-it-shapes-your-decisions/

  3. Sequence of returns risk: Why the order of returns matters in retirement. The Long Math. https://www.thelongmath.com/articles/investing-and-financial-literacy/sequence-of-returns-risk/

  4. Te Ara Ahunga Ora. (2022). Annual report 2022. https://assets.retirement.govt.nz/public/Uploads/Annual-Report/TAAO-RC-Annual-Report-2022.pdf

  5. Dai, W., & Dong, A. (2023, October 31). We found 30 timing strategies that “worked”—and 690 that didn't. Dimensional Fund Advisors. https://www.dimensional.com/sg-en/insights/we-found-30-timing-strategies-that-worked-and-690-that-didnt


Private Assets: You're Not Joining the Club, You're Funding It

Article # 463

Private. Special. Exclusive. Three words that do a lot of heavy lifting in finance. They frame private equity and private credit as access and privilege. Yet beneath the velvet-rope marketing sits a familiar set of trade-offs: high fees, illiquidity, and a lack of transparency. For decades that rope kept ordinary investors out. It was quietly removed, and nobody sent a memo.

Historically, these markets belonged to pension funds, endowments and family offices with eight figures to commit and twelve years to wait. Ordinary investors didn't get a seat at the table. They are now being offered one, through KiwiSaver growth funds, UK Long-Term Asset Funds dropped inside tax-advantaged ISAs, and the family trust portfolios they signed off on last year [1]. The FMA confirmed in April that most KiwiSaver providers expect to materially lift their private asset allocations over the next three years, aligning with global investment trends [2]. The industry calls it democratisation. Governments call it unlocking growth.

This week the trend turned local and concrete. Simplicity committed $30 million to a new Kiwi deep tech and health sciences venture fund, becoming a cornerstone investor [3]. The fund holds a small number of early-stage companies, including pre-revenue biotech automating cancer-cell therapy manufacturing. It is not fully funded on day one; it is a capital-call vehicle, drawn down over the life of the fund. The parent is US-headquartered, and the capital base includes migrant investors using it as a pathway to residency. None of that is hidden, and backing clever Kiwi innovation is a perfectly defensible thing to do. But it is a useful reminder of what this asset class is once you look inside the wrapper: a long-dated, illiquid, concentrated bet that you cannot easily value or exit.

About that 40-year outperformance

In January, Tony Robbins told millions of viewers on The Diary of a CEO that private equity has outperformed every stock market globally for 40 years, and that ordinary investors have been locked out [4]. He is right on the data. The data, however, deserves a closer look before you remortgage the bach.

First, it has been cherry-picked by survivorship. The funds that blew up quietly drop out of the long-run series, so what you are shown is the record of the survivors, a bit like judging parachutes by interviewing the people who landed. Second, much of the return is leverage, not skill; borrow heavily against a stable business and you amplify the good years, and the bad. Third, and least discussed, is the illiquidity premium. You are tying your money up for a decade or more in a speculative bet on a handful of companies you cannot sell when you want to. You would expect to be paid more for taking on more risk and less liquidity. That extra return is not evidence of genius; it is the rent on your patience. Strip out dead funds, borrowed money and locked-up capital, and the heroic outperformance narrows sharply, and that is before fees [5].

What Robbins is less keen to dwell on is that he co-owns CAZ Investments, which buys stakes in private equity management companies, and that he personally holds stakes in 95 PE firms; the firms themselves, not the funds [6]. He collects the "2 and 20" on each: two percent of assets every year, plus twenty percent of profits above a hurdle [4]. Draw your own conclusions about the shape of those incentives.

The cycle, and the cautionary tale

On the credit side, JPMorgan chief Jamie Dimon used his April shareholder letter to flag what the more enthusiastic salespeople tend to leave in the bag: the credit cycle still exists [7]. Lending standards loosened during the boom. Covenant-lite deals became common in private credit too [8]. When the cycle turns, losses will not stay gated.

In August 2024, the Government placed Du Val Group, an Auckland property developer, into statutory management. This is only the third time that lever has ever been pulled, following Equiticorp in 1989 and Allan Hubbard's vehicles in 2010 [9].

The Du Val Mortgage Fund had been marketed as wholesale-only at around 10% per annum, pitched as comparing favourably to bank term deposits. That label is not a marketing flourish but a regulatory category: an offer made only to wholesale investors is excluded from the disclosure regime built to protect ordinary investors, so there is no product disclosure statement and no entry on the public Disclose register [9]. Roughly 120 to 150 investors are now owed close to $306 million [9]. When investors tried to sue the FMA for failing to protect them, the High Court ruled in Lindeman Investments v FMA that the regulator owes no duty of care to individual wholesale investors [10]. The safety net does not stretch that far, and by design: the wholesale regime switches off most of the retail protections long before any loss is incurred.

Every newborn, a private asset owner

Fisher Funds has committed more than $1 billion of KiwiSaver money to private equity, the largest publicly announced commitment to date [11]. Most other major providers also carry exposure, and per the FMA report most plan to lift those allocations over the next three years [2]. On Sunday, Christopher Luxon announced that, if re-elected, KiwiSaver would become compulsory from 2028, every newborn would be auto-enrolled with a $1,500 Baby Boost defaulted into a high-growth fund, and the combined contribution rate would reach 12% by 2032 [12]. Every newborn New Zealander would begin their financial life with a private asset exposure they did not choose, in a vehicle they cannot exit until at least 2090.

Structure is not the same as transparency

None of this makes private assets an inherently bad asset class. The issue is the layering, the marketing, and the question of who benefits from the door opening now. Where the exposure is plainly structured, a named partnership backing identifiable businesses with disclosed allocations, the picture is more straightforward than where it runs through layered offshore fund-of-funds with opaque manager economics. But structure on paper is not the same as transparency in practice. Diligent managers have tried to look through some of the better-regarded local vehicles and come up short on what is actually held and how it is valued. If the people whose job is to see inside cannot, the ordinary member certainly cannot. We do not invest our own clients in this asset class, for precisely these reasons. It would be premature to suggest New Zealand has quietly cracked private assets when the same transparency, valuation and liquidity questions remain.

Here is what matters most, and what the marketing almost never spells out: understand whether your commitment is fully funded on day one or subject to future capital calls. Some private equity is paid up front, with no further obligation, clean and simple. Much of it is not. A commitment of thirty cents on the dollar today can trigger calls for the remaining seventy cents in the years ahead. Your disclosed allocation now will not reflect your actual exposure tomorrow; as the calls arrive, your percentage holding and your real risk are multiplied. A trustee who signs off on what looks like a modest five percent allocation can find the true commitment is several times that once the fund draws down. I have watched exactly this happen to a community trust, where a decision made by earlier trustees carried obligations that only became visible years later.

For trustees, this is not simply an investment preference; it is a governance question.

Under the Trusts Act 2019, trustees of family and charitable trusts inherit a look-through duty [13]. Few today can name the private asset exposures they are responsible for, let alone the unfunded commitments sitting behind them. Asking the question is the first part of discharging the duty.

Four questions for any provider, adviser, or co-trustee:

  1. What are the all-in fees across every layer?

  2. How are the underlying assets valued: how often, and by whom?

  3. Is the commitment fully funded, or subject to future capital calls?

  4. In whose interest is the allocation being recommended?

The answers should be plain and confident. If they aren't, that itself is a flag you shouldn't ignore.

Robbins is right that private equity has outperformed historically. Dimon is right that the credit cycle still exists. What is less often spoken about is who benefits from unlocking the door now, and why.

Private. Special. Exclusive. Useful words for the fee machine; less useful for the person handing over their money. You are not joining the club; you are funding it.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz

  • We do not hold or advise on any private credit or private equity investments.


REFERENCES

  1. Financial Conduct Authority (UK). Long-Term Asset Fund regime, FCA Handbook COLL 15. HM Treasury (2025). Inclusion of LTAFs in stocks and shares ISAs. gov.uk.

  2. Financial Markets Authority (2026, 15 April). Private assets in managed funds: Investment landscape and valuation practices. Accompanying media release: “FMA anticipates KiwiSaver providers will increase investment in private assets.” Source: FMA.

  3. Simplicity (2026, 24 June). “Simplicity backs ambitious Kiwi innovators with $30m investment.” Details: $30m cornerstone commitment to Bridgewest Venture Fund I (Deep Tech and Health Sciences Fund). Provider disclosure context: Booster, Milford, Generate, Pathfinder, ANZ Investments and others carry private asset allocations across growth and high-growth options.

  4. The Diary of a CEO with Steven Bartlett (2026, 15 January). “Tony Robbins: No One Is Ready For What’s Coming.” Details: transcript references Robbins’ stakes in 95 private equity firms, the firms, not the funds, receiving the “2 and 20” on each.

  5. Bain & Company (2025). Global Private Equity Report 2025. Details: fee conventions of 1–1.5% management plus 10–20% carry above a preferred return. Supporting context: MSCI, Chicago Booth Review and NBER research on buyout outperformance of roughly 3–5% per year over public market equivalents, with debate over the role of leverage, survivorship bias and the illiquidity premium.

  6. CAZ Investments. Firm overview and GP-stakes strategy. Robbins, T., Zook, C. and Mallouk, P. (2024). The Holy Grail of Investing. Simon & Schuster.

  7. JPMorgan Chase & Co. (2026). Annual Letter to Shareholders 2025. Author: Jamie Dimon. Released April 2026. Source: JPMorgan Chase & Co.

  8. Reserve Bank of New Zealand (2026, May). Financial Stability Report. Details: private credit market concerns. Source: Reserve Bank of New Zealand.

  9. Financial Markets Authority (2024, 21 August). “Du Val Group: statutory management ordered.” Source: FMA. Supporting coverage: BusinessDesk (2025, 4 August), “A year since raids, FMA yet to prosecute over Du Val collapse.”

  10. Lindeman Investments Limited v Financial Markets Authority [2025] NZHC. Judgment date: 11 July 2025. Summary source: Cooney Lees Morgan, “The FMA safety net has limits when it comes to wholesale investor groups.”

  11. NZ Herald, The Prosperity Project (2025, 4 August). “The rise of KiwiSaver investing in private equity and what it means for you.” Details: Fisher Funds committing more than $1 billion of KiwiSaver funds to private equity.

  12. New Zealand National Party (2026, 21 June). “National To Further Boost Kiwis’ Financial Security.” Details: press release, annual conference, Lower Hutt. Coverage: NZ Herald, RNZ, 1News, Newsroom and Scoop (21–22 June 2026). Estimated fiscal cost: $1.1 billion over four years.

  13. New Zealand Parliament (2019). Trusts Act 2019, ss 30–31.


We Need to Talk About Envy

When a newspaper tells you how to hate someone, it reveals more about itself than its target.


Article #462

“Envy was once considered to be one of the seven deadly sins before it became one of the most admired virtues under its new name, ‘social justice’.”

Thomas Sowell, The Quest for Cosmic Justice (1999) [1]

Last week the New Zealand Herald reported, plainly, that Elon Musk had become the world’s first trillionaire after shares in SpaceX leapt as much as 30% on debut, the largest initial public offering in history. [2,3] That is the news. What happened next is the story.

Canada’s Globe and Mail ran an opinion piece under the headline: ‘SpaceX IPO makes Elon Musk the first trillionaire. Here’s how to properly hate him.’ After a day of ridicule, the paper swapped it for the more respectable ‘Is that a bad look for capitalism?’ and tacked on a note conceding the original ‘did not meet The Globe’s editorial standard.’ [4] The mask slipped, then was hastily refitted. But we all saw the face beneath.

Closer to home, the chorus is familiar. Oxfam Aotearoa tells us four New Zealand billionaires hold more wealth than 1.8 million of their countrymen, and calls it ‘obscene.’ [5] Academics line up on talkback to lament inequality. Polls are cited showing most New Zealanders want the ultra-rich taxed more, and we are reminded that Musk alone is worth almost as much as every New Zealander combined [6,7]. The sentiment is always the same: someone has too much, and that is a problem to be corrected rather than a phenomenon to be understood.

Musk is not, in fact, the first trillionaire. Under Robert Mugabe, Zimbabwe's central bank printed a hundred-trillion-dollar note that on its first day was worth about US$30, and within weeks nothing at all; at the peak, prices doubled every day [8]. In that sense, many Zimbabweans became trillionaires on paper yet still could not buy a loaf of bread. That is the distinction worth dwelling on.

A trillion earned by building what people want is the opposite of a trillion conjured by a collapsing state: one is value created, the other value destroyed.

I want to make the unfashionable case. Not for Musk the man, he hardly needs my help, but for what the exception represents: the rare individual who turns the stuff of science fiction into things we use every day without a second thought, the smartphone in your pocket, the satellite that carries your call, the online payment that clears in seconds, the electric car at the lights, the cloud software that runs the small business down the road.

Consider the funnel. Many people have ideas. Fewer act on them. Fewer still build something that turns a profit. And a vanishingly small number, statistical outliers, take an idea and deliver it at scale. New Zealand has produced our own precious few: the Mowbray siblings, whose toy and consumer-goods firm Zuru, started in a shed in 2003, now tops the Rich List at an estimated $20 billion; Trade Me, Xero, Rocket Lab, the family-owned Gallagher Group, which grew from a Waikato farm shed and the world's first electric fence into a security firm operating in some 160 countries, and Fisher & Paykel Healthcare, built and headquartered here and exporting respiratory care to around 120 countries [9,10,11].

And the same pattern holds inside the companies we reduce too easily to a single famous name. Gwynne Shotwell joined SpaceX as its eleventh employee in 2002 and helped build it, as president, into the company that just floated; she now sits, according to Forbes, among the richest self-made women in the world, with a stake estimated at around US$2.5 billion [12]. The builders are plural, and the rewards often follow competence more than celebrity.

Here is the part the zero-sum brigade often misses: the same SpaceX listing that minted the world's first trillionaire also turned more than 4,400 current and former staff into millionaires, by the New York Times' reckoning – some 400 of them past the $100 million mark. The reach went a long way down the org chart. One was a welder who joined in 2015 on about US$28 an hour and took part of his pay in stock; his holding is now worth close to a million dollars [13]. The trillionaire headline and the newly wealthy welder came from the very same event. The pie did not get carved up. It got bigger.

The question for New Zealand is whether we are willing to learn from that. The NBR Rich List has swelled 23-fold in forty years to a record $129 billion, with Rocket Lab's Sir Peter Beck alone leaping from about $650 million to $11 billion in a single year as his company's shares soared [14]. And yet our productivity has barely moved in thirty years. We are very good at debating how to carve the pie, and strangely uninterested in baking a larger one.

None of this is new. Andrew Carnegie and John D. Rockefeller were the titans of their age, reviled in their time as robber barons, cartoonish villains of the popular press. The cartoonists drew them as bloated octopuses with the nation in their tentacles. Carnegie ground out his fortune in steel and, in his later years, gave most of it away, seeding free public libraries across the world, more than 2,500 of them, eighteen in New Zealand alone [15]. Rockefeller's money built the University of Chicago and funded the medical research that helped tame yellow fever and hookworm [16]. The resentment faded. The libraries, the universities, the cures remain. That is the part the wreckers never see: the wealth was temporary, but the institutions it built endured, and we are still drawing on them a century later.

Great fortunes gather, they crest, and in time they disperse through families, philanthropy, taxation and the simple passage of generations. Marriages fail and children inherit and quarrel; fortunes fracture along fault lines no one planned for. Jeff Bezos parted with roughly a quarter of his Amazon stake in a single divorce [17]. Wealth scatters faster than any succession plan can contain it. No one takes it with them. They are only ever the custodian of their wealth for the span of their life, and perhaps a generation or two beyond, if they are fortunate.

I make the same point to those who fret about foreigners buying New Zealand farms and businesses. A buyer cannot pack up a farm, or a company, and carry it home in a box to their country of origin. The land stays. The business stays. The jobs, the buildings and the economic activity all remain here, in New Zealand. The buyer is a custodian, nothing more. So too with the great fortunes: the enterprises outlast the individual, and we are the beneficiaries.

And here is what the envious rarely pause to weigh: the cost of building any of it. The outlier does not arrive at scale by working office hours. Musk's own biographers record the toll: Walter Isaacson, who shadowed him for years, documents a leader hands-on in redesigning rocket components and welding design to production, while Ashlee Vance describes the hundred-hour weeks and nights spent sleeping on factory floors [18,19]. He risked ruin, repeatedly; Tesla and SpaceX both came within weeks of collapse in 2008, and he poured in his own money to keep them breathing. For every founder who makes it, a great many do not: they mortgage the house, burn the savings, lose the marriage, and end up with nothing but the lesson. Most of us, honestly, would not want that life if it were handed to us, and that is no shame. But it ought to buy a little humility before we throw stones over the fence at grass we have decided, from a distance, must be greener.

Some will say the fortune was really built on government largesse: the contracts, the green credits [20]. But the credits were no handout. Every carmaker operated under the same zero-emission rules; the money came from rival manufacturers who lagged on electric cars, not from the taxpayer; and Tesla profited simply because it built cleaner cars faster than anyone else. The same scheme runs in Europe and China. That is not a subsidy. That is winning the game everyone was playing.

As for the calls to tax such people into their place, success is already taxed, and handsomely. That is how it works. But a culture that treats achievement as a crime to be punished rather than a feat to be studied will get less of it. The numbers bear it out: resentment is not a growth strategy.

There is a fiduciary truth in all of this, the same one I return to with clients. Tearing others down builds nothing. The job, mine, yours, the nation’s, is stewardship: to grow what we are given, to think in decades rather than headlines, and to leave more behind than we found. A country that celebrates its builders is a healthier place than one that polices its winners. Glass half full beats glass half empty, every time.

So before we are told, yet again, how to properly hate someone for the sin of succeeding, it is worth asking the more useful question. Not how do we cut them down to size, but what will we leave standing when we are gone?

Winter never lasts; the snows always melt.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


REFERENCES

  1. Thomas Sowell, The Quest for Cosmic Justice (1999), source of the epigraph.

  2. New Zealand Herald, ‘Elon Musk becomes world’s first trillionaire as SpaceX shares jump’ (June 2026).

  3. RNZ, ‘SpaceX launches US$2 trillion market debut, the largest IPO in history’ (June 2026).

  4. The Globe and Mail, Chris Gay, ‘SpaceX IPO makes Elon Musk the first trillionaire. Here’s how to properly hate him’ (headline since amended with editor’s note, June 2026).

  5. Oxfam Aotearoa, statement on billionaire wealth concentration in New Zealand (2026).

  6. RNZ / Talbot Mills poll, ‘New Zealanders support more taxes on ultra-rich, new poll shows’ (Wellbeing Economy Alliance Aotearoa; 68% backed higher taxes on the ultra-rich, 2026).

  7. RNZ, ‘Elon Musk only marginally less wealthy than all New Zealanders combined’ (June 2026).

  8. Reserve Bank of Zimbabwe / BBC, the Z$100 trillion note, issued 16 January 2009, worth about US$30 on its first day; one of history’s worst hyperinflations, with prices doubling daily at the November 2008 peak.

  9. Zuru / NBR Rich List 2026, founded by Nick, Mat and Anna Mowbray in 2003; estimated at $20b, the top spot on the 2026 NBR Rich List.

  10. Gallagher Group, Hamilton-based, family-owned; from the world’s first electric fence (1938) to integrated security solutions in around 160 countries.

  11. Fisher & Paykel Healthcare, New Zealand-headquartered respiratory-care manufacturer; sells in around 120 countries, with roughly 1% of revenue from domestic sales (publicly listed; majority institutional ownership).

  12. Forbes, ‘America’s Richest Self-Made Women’ (2026 list), featuring SpaceX president Gwynne Shotwell.

  13. The New York Times, reporting via Hill.com analysis that SpaceX’s IPO would turn more than 4,400 employees into millionaires, including a welder hired in 2015 (June 2026).

  14. NBR Rich List 2026, 40th edition; total listed wealth a record $129b (up from $102.1b), a 23-fold rise in 40 years; Rocket Lab’s Sir Peter Beck up from ~$650m to ~$11b (reported via RNZ / NZ Herald / Scoop, June 2026).

  15. Carnegie Corporation of New York, historical record of Carnegie free public library endowments.

  16. Rockefeller Foundation / University of Chicago, record of Rockefeller’s ~$36m founding gift to the University of Chicago and Foundation-led campaigns against hookworm and yellow fever (first yellow-fever vaccine, 1935).

  17. Bezos / Scott divorce (2019), widely reported transfer of roughly a quarter of Jeff Bezos’ Amazon stake to MacKenzie Scott.

  18. Walter Isaacson, Elon Musk (2023), on Musk’s hands-on engineering role across his companies.

  19. Ashlee Vance, Elon Musk: Tesla, SpaceX, and the Quest for a Fantastic Future (2015), on the 100-hour weeks and factory-floor work ethic.

  20. RNZ, ‘How much of Elon Musk’s wealth comes from government help? Virtually all of it’ (June 2026), cited here as the claim being answered; on ZEV regulatory credits, see the Union of Concerned Scientists and CNBC explainers (credits are traded between automakers, not paid by the taxpayer).


IMAGE CREDITS

  • John D. Rockefeller depicted in the political cartoon 'The Trust Giant's Point of View' by Horace Taylor in 'The Verdict, ' 1900

  • “Standard Oil Octopus” - Keppler, Udo J., 1872-1956, artist. Published September 1904

  • Carnegie Free Library, Thames - Coromandel Heritage Trust. Photograph by David Wilton.

  • Auckland City Libraries – Tāmaki Pātaka Kōrero, Sir George Grey Special Collections (AWNS-19080716-13-6)