Interest Rates

Cheap Money has a Maturity Date

Article #474

In January 1672, Charles II stopped paying his creditors. 

The Stop of the Exchequer was announced as a temporary suspension. A delay, not a default. The distinction mattered a great deal to the Crown and not at all to the people who were owed the money. A borrower who cannot pay on the day they promised has defaulted, whatever the announcement calls it. 

The goldsmith bankers of Lombard Street, who had lent the Crown the money, were ruined. English government credit took a generation to recover. What eventually replaced it was something better than a king's promise: a funded national debt, the Bank of England in 1694, and a Parliament standing behind the borrowing rather than a monarch who could walk away from it. 

Over the century that followed, Britain outlasted Louis XIV and then Napoleon, both of whom governed larger and wealthier countries. Britain did not win because it was richer. It won because it could borrow more cheaply, for longer, and go on borrowing when its rivals could not. Creditworthiness turned out to be a weapon. 

The price of borrowing is not set by announcement. It is set at auction, by whoever turns up with capital and a choice about where to put it. Central banks can turn up too, and for a decade they did. But the auction reasserts itself the moment the official bid is withdrawn.

The OCR is not the whole story 

On 2 September the Reserve Bank lifted the Official Cash Rate to 2.75%, with annual inflation at 4.1% in the June quarter, driven largely by fuel prices flowing from the Middle East conflict [1]. 

The OCR sets the short end. It does not set the rate on a five-year term deposit, a two-year fixed mortgage, or a ten-year bond. Those price off wholesale rates, and wholesale rates are set in a global auction New Zealand does not run and cannot influence. 

A great many borrowers are turning up to that auction at once. 

Germany is funding a substantial military expansion by borrowing, with no corresponding retreat from its welfare state. Britain plans to expand its own. The bill for both goes to the same auction. The pattern repeats across the West, while the technology companies raise enormous sums to build artificial intelligence data centres. 

Nor is this only a Western habit, and China is the clearest case of a number that is not what it is announced to be. Beijing's headline deficit for 2026 is 4% of GDP. Once the CNY 4.4 trillion of local government special purpose bonds and the CNY 1.3 trillion of ultra-long special treasury bonds sitting outside that headline are counted, the consolidated deficit reaches a record 9.1% of GDP [2]. National debt is set to rise by close to CNY 14 trillion this year alone. 

The rate matters more than the level. Mark Williams, chief Asia economist at Capital Economics, calculates that China's total debt outside the financial sector has doubled as a share of GDP since 2010 and now tops 300%, putting its indebtedness, in his words, in a league of its own. The comparison most readers expect runs the other way. Broad American debt, public and private, has fallen as a share of GDP since 2010, to around 265% [3]. Nearly 40% of China's is owed by the public sector, local government financing vehicles included [3]. 

The numbers are not small. OECD central governments issued USD 17 trillion of bonds in 2025 and are projected to issue USD 18 trillion this year. Corporates added USD 6.8 trillion. All of it lands in a market where central banks, having spent a decade as the buyer of last resort, have stopped buying [4]. Local government sits in the same queue, one step removed, borrowing through agencies that price off the sovereign. 

More bonds offered, not proportionately more buyers at the same price, so the yield must rise to attract the capital. German ten-year yields are at their highest since 2011, Japanese yields have crossed 3%, and British gilts are at their highest since the financial crisis [5]. 

The honest counter-argument 

It would be tidy to say that governments and technology companies are crowding everybody else out, and leave it there. It would also be a little too tidy. 

Corporate borrowing did reach a record in 2025, USD 13.7 trillion raised across bond and syndicated loan markets, passing the 2021 peak. Nine large technology companies accounted for USD 122 billion of it, around 45% of all bond issuance by technology firms worldwide and more than three times the annual average since 2000. Yet the OECD's own assessment is that this came to no more than 15% of investment grade issuance by non-financial firms in the United States, and was absorbed without market-wide friction [6]. Capital markets are deep, and the pool is not fixed in the way the word crowding suggests. 

There is also a competing explanation for the move in yields that has nothing to do with supply at all. The oil price shock has reignited inflation expectations, and investors demanding more compensation for inflation will lift yields whether or not another bond is ever issued. 

Both explanations are probably doing some of the work. That is usually how markets behave, and anyone offering a single clean cause is selling something. What is not in dispute is the direction of travel, or that a borrower refinancing in 2029 will pay whatever the market asks in 2029, regardless of which explanation was correct. 

There is a second detail in the OECD data worth sitting with. Issuers have been shortening their maturities. In 2025 the ratio of bonds issued at thirty years and beyond, compared with those issued at one to five years, was the lowest since at least 2008 [4]. Short borrowing is cheaper today. It also means the debt comes back around sooner, and more often. That is a decision to pay less now, in exchange for finding out later. 

Cheap money has a maturity date 

A higher yield is not felt today. It is felt at maturity. 

Nearly 80% of what OECD governments borrow this year is not new spending at all. It is refinancing debt that already exists [4]. Borrowers who locked in cheap fixed rates a few years ago keep them right up to the day the debt rolls off and must be refinanced at whatever the auction is charging then. It will bite hardest where the debt is largest and the maturities shortest. Heavily indebted institutions are not repriced gradually. They are repriced in instalments, on a timetable set years ago by people who are frequently no longer there. 

New Zealand is not exempt. In March, Fitch revised New Zealand's outlook to negative while affirming the AA+ rating, forecasting general government debt at 56% of GDP by June 2027 and citing delayed fiscal consolidation [7]. Six days later the Local Government Funding Agency received the same revision, automatically, because as a government-related entity its rating is equalised with the Crown's [8]. LGFA provides most council borrowing in this country, Hastings included. 

Everyone drinks from the same pond.

Sovereigns, councils, banks, businesses, then the household. Different straws at different depths, the same water. Nobody in Taihape voted on the German defence budget. It is in the swap rate all the same, and the swap rate is in the mortgage at renewal. 

Milton Friedman's advice was to keep your eye on one thing only, how much government is spending, because that is the true tax. Thatcher put it less gently, that we have been ruled by men who live by the illusion that you can spend money you have not earned without eventually falling into the hands of your creditors. Whatever one makes of the politics, the arithmetic has not been repealed. The auction is where the bill arrives, and it arrives with interest. 

What this means for the investor 

For anyone with savings, this cuts both ways. 

After a decade of being told the coupon was a rounding error, it is worth having again. Income that had effectively disappeared from conservative portfolios has come back, and for retirees drawing on capital that is a meaningful improvement rather than a technical one. 

But a yield is not a gift. It is compensation, and the whole question is compensation for what. Credit quality, term, currency, and who stands behind the issuer. A bond paying more than the one beside it is priced that way for a reason, and the reason is rarely generosity. When someone offers a return well above the market for what they describe as much the same risk, one of those two claims is wrong, and it is not usually the return. 

Nor is the answer to reach for duration simply because longer bonds pay more today. Term is a risk, not a free lunch, and the investor who buys a long maturity to capture an extra sliver of yield has taken a view on the next decade of inflation whether they meant to or not. 

Bonds belong in a well-engineered portfolio. Not every bond belongs in yours. All bonds are equal, as Orwell might have put it, but some are more equal than others. 

Charles II discovered that credit, once lost, is not bought back. It is earned back, slowly, and usually by someone else's generation. The investor who reaches for yield without asking what it is paying for learns a smaller version of the same lesson. That question is easier to answer when the person answering it is bound by duty to put your interests before their own.

Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References 

1. Reserve Bank of New Zealand (2 September 2026). OCR increased by 25 basis points to 2.75%. https://www.rbnz.govt.nz/news-and-events/news/2026/09/ocr-increased-by-25-basis-points-to-2-75 

2. China Power Project, Center for Strategic and International Studies (2026). Making Sense of China's Government Budget. https://chinapower.csis.org/making-sense-of-chinas-government-budget/ 

3. Fortune (11 May 2026). Forget US debt, China's total borrowing is in a league of its own. https://fortune.com/2026/05/11/us-debt-china-total-borrowing-public-private-gdp-ratio-lgfv/ 

4. OECD (2026). Global Debt Report 2026: The investor base for government and corporate bond markets. https://www.oecd.org/en/publications/global-debt-report-2026_e9d80efd-en/full-report/the-investor-base-for-government-and-corporate-bond-markets_e68b90b3.html 

5. CNBC (3 September 2026). Global bond yields rising: Treasuries, JGB, Bunds. https://www.cnbc.com/2026/09/03/global-bond-yields-rising-treasuries-jgb-bunds.html 

6. OECD (2026). Global Debt Report 2026: Corporate debt market outlook in a transforming world. https://www.oecd.org/en/publications/global-debt-report-2026_e9d80efd-en/full-report/corporate-debt-market-outlook-in-a-transforming-world_cf86a220.html 

7. Fitch Ratings (20 March 2026). Fitch revises outlook on New Zealand to negative; affirms at AA+. https://www.fitchratings.com/research/sovereigns/fitch-revises-outlook-on-new-zealand-to-negative-affirms-at-aa-20-03-2026 

8. New Zealand Local Government Funding Agency (26 March 2026). Credit Rating Outlook Revised to Negative by Fitch Ratings. NZX announcement. https://announcements.nzx.com/announcement/469979 

Don't Buy All You Can Borrow

Article #471

Your parents lied to you.

Not about Santa Claus, or carrots improving your eyesight, or the dog going to live on a farm. About something far more expensive, and something you probably did with a pen in your hand and a banker smiling across a desk.

“Buy the best house you can afford,” they said, somewhere between the roast lamb and the pavlova. “Property always goes up.” They smiled knowingly, the way parents do when they think they have just handed you the map to the treasure.

They handed you a map, alright. To a different kind of buried thing entirely.

There is a peculiarly New Zealand religion around property, and we are its most devoted congregation. We flip through TradeMe listings the way other cultures read scripture, and attend open homes on Saturdays like it is church. We have been raised to believe that the house is the thing. The bigger the better. Stretch for it. The bank will say yes.

And the bank will say yes. That is precisely the problem. Banks are not your parents and they are not your friends. They exist to extract a return from the spread between what they pay for money and what they charge you for it, and are content to lend you every last dollar you can theoretically service. The bank's interest is not your interest. Literally.

Property Always Goes Up

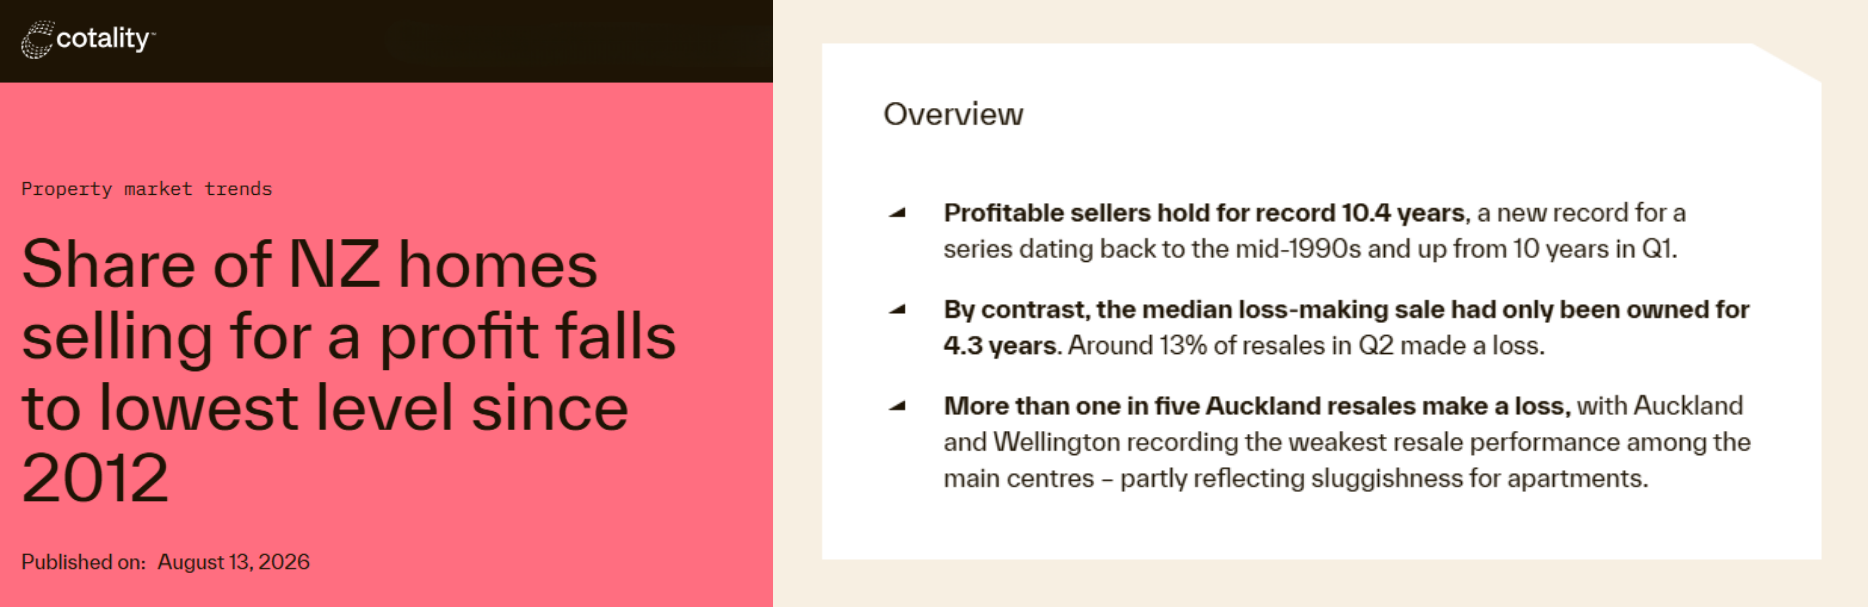
Except when it does not. Cotality data released this month shows that in the second quarter of 2026, 13.1% of New Zealand homes resold at a loss, the highest since 2012, at a median $60,000 below purchase price and $159 million across the quarter. Investors fared worst at 13.5%, against 12.2% for owner-occupiers.[1] In fairness, 86.9% still resold at a gross profit, so this is a slide rather than a rout, and it has come without the mortgagee sales of the global financial crisis.

Source: Cotality | Explore Insights and Report HERE

But the number that matters most for this argument is the hold period. Profitable resales had been owned for a median of 10.4 years, a record high. Loss-making resales, 4.3 years.[1]

That is the whole case in two figures. Time rescues a property purchase, and borrowing to the absolute ceiling is what takes time away from you, because when the rate cycle turns or the premium arrives or the job changes, you sell when you must rather than when you choose. The buffer is not a luxury. The buffer is the hold period.

The counter-case deserves an honest hearing. Property has, over long periods, rewarded those who bought as much as they could as early as they could, while inflation eroded their debt. That is true, and it is also survivorship talking. The three conditions that made maximum leverage work, being falling interest rates, cheap and available insurance, and council rates rising near inflation, have now reversed at once.

The Rate Rollercoaster

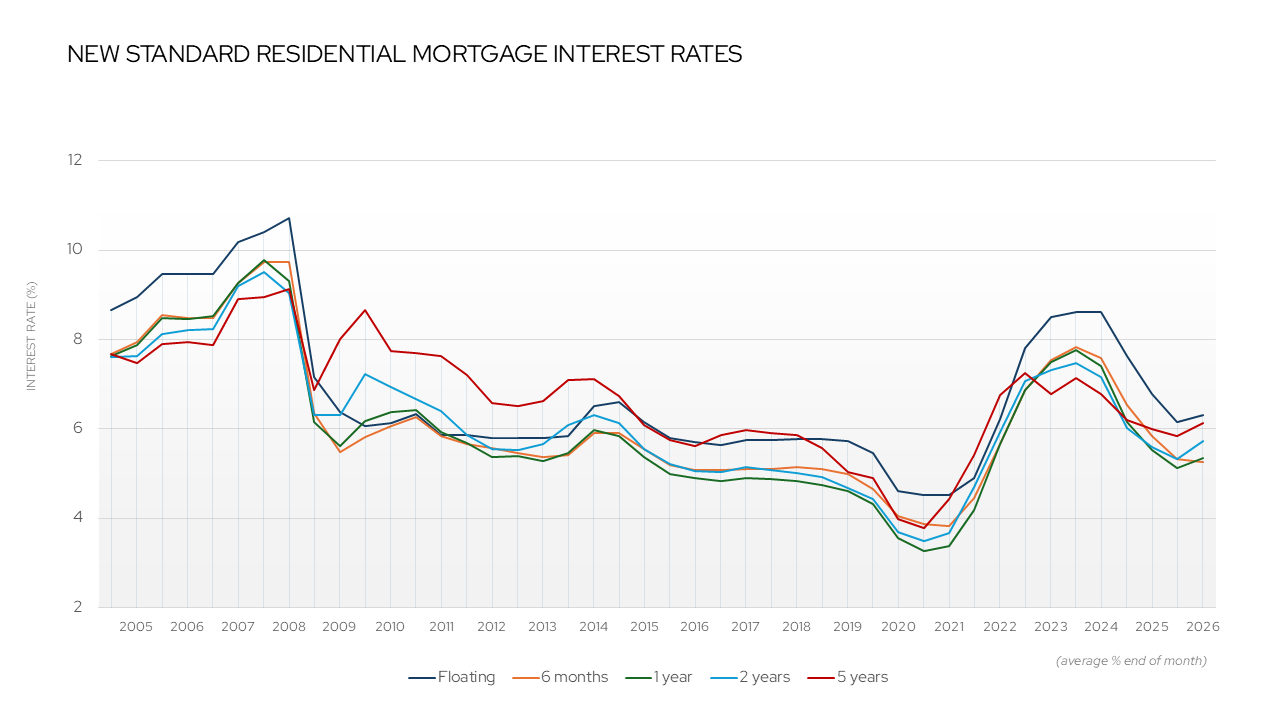
Between November 2021 and May 2023 the Reserve Bank lifted the OCR from a record low 0.25% to 5.50%, and by January 2024 the average one-year fixed rate had climbed to 7.5% from 2.58%.[2] Households borrowed to the maximum of their serviceability were suddenly underwater. Rates came down through 2025 as the Bank cut nine times to 2.25%.[3] On 8 July 2026 it raised the OCR for the first time in three years.[4] The cycle is shorter than anyone expected.

Source: www.rbnz.govt.nz/statistics - New residential mortgage standard interest rates

Then Comes the Insurance Bill

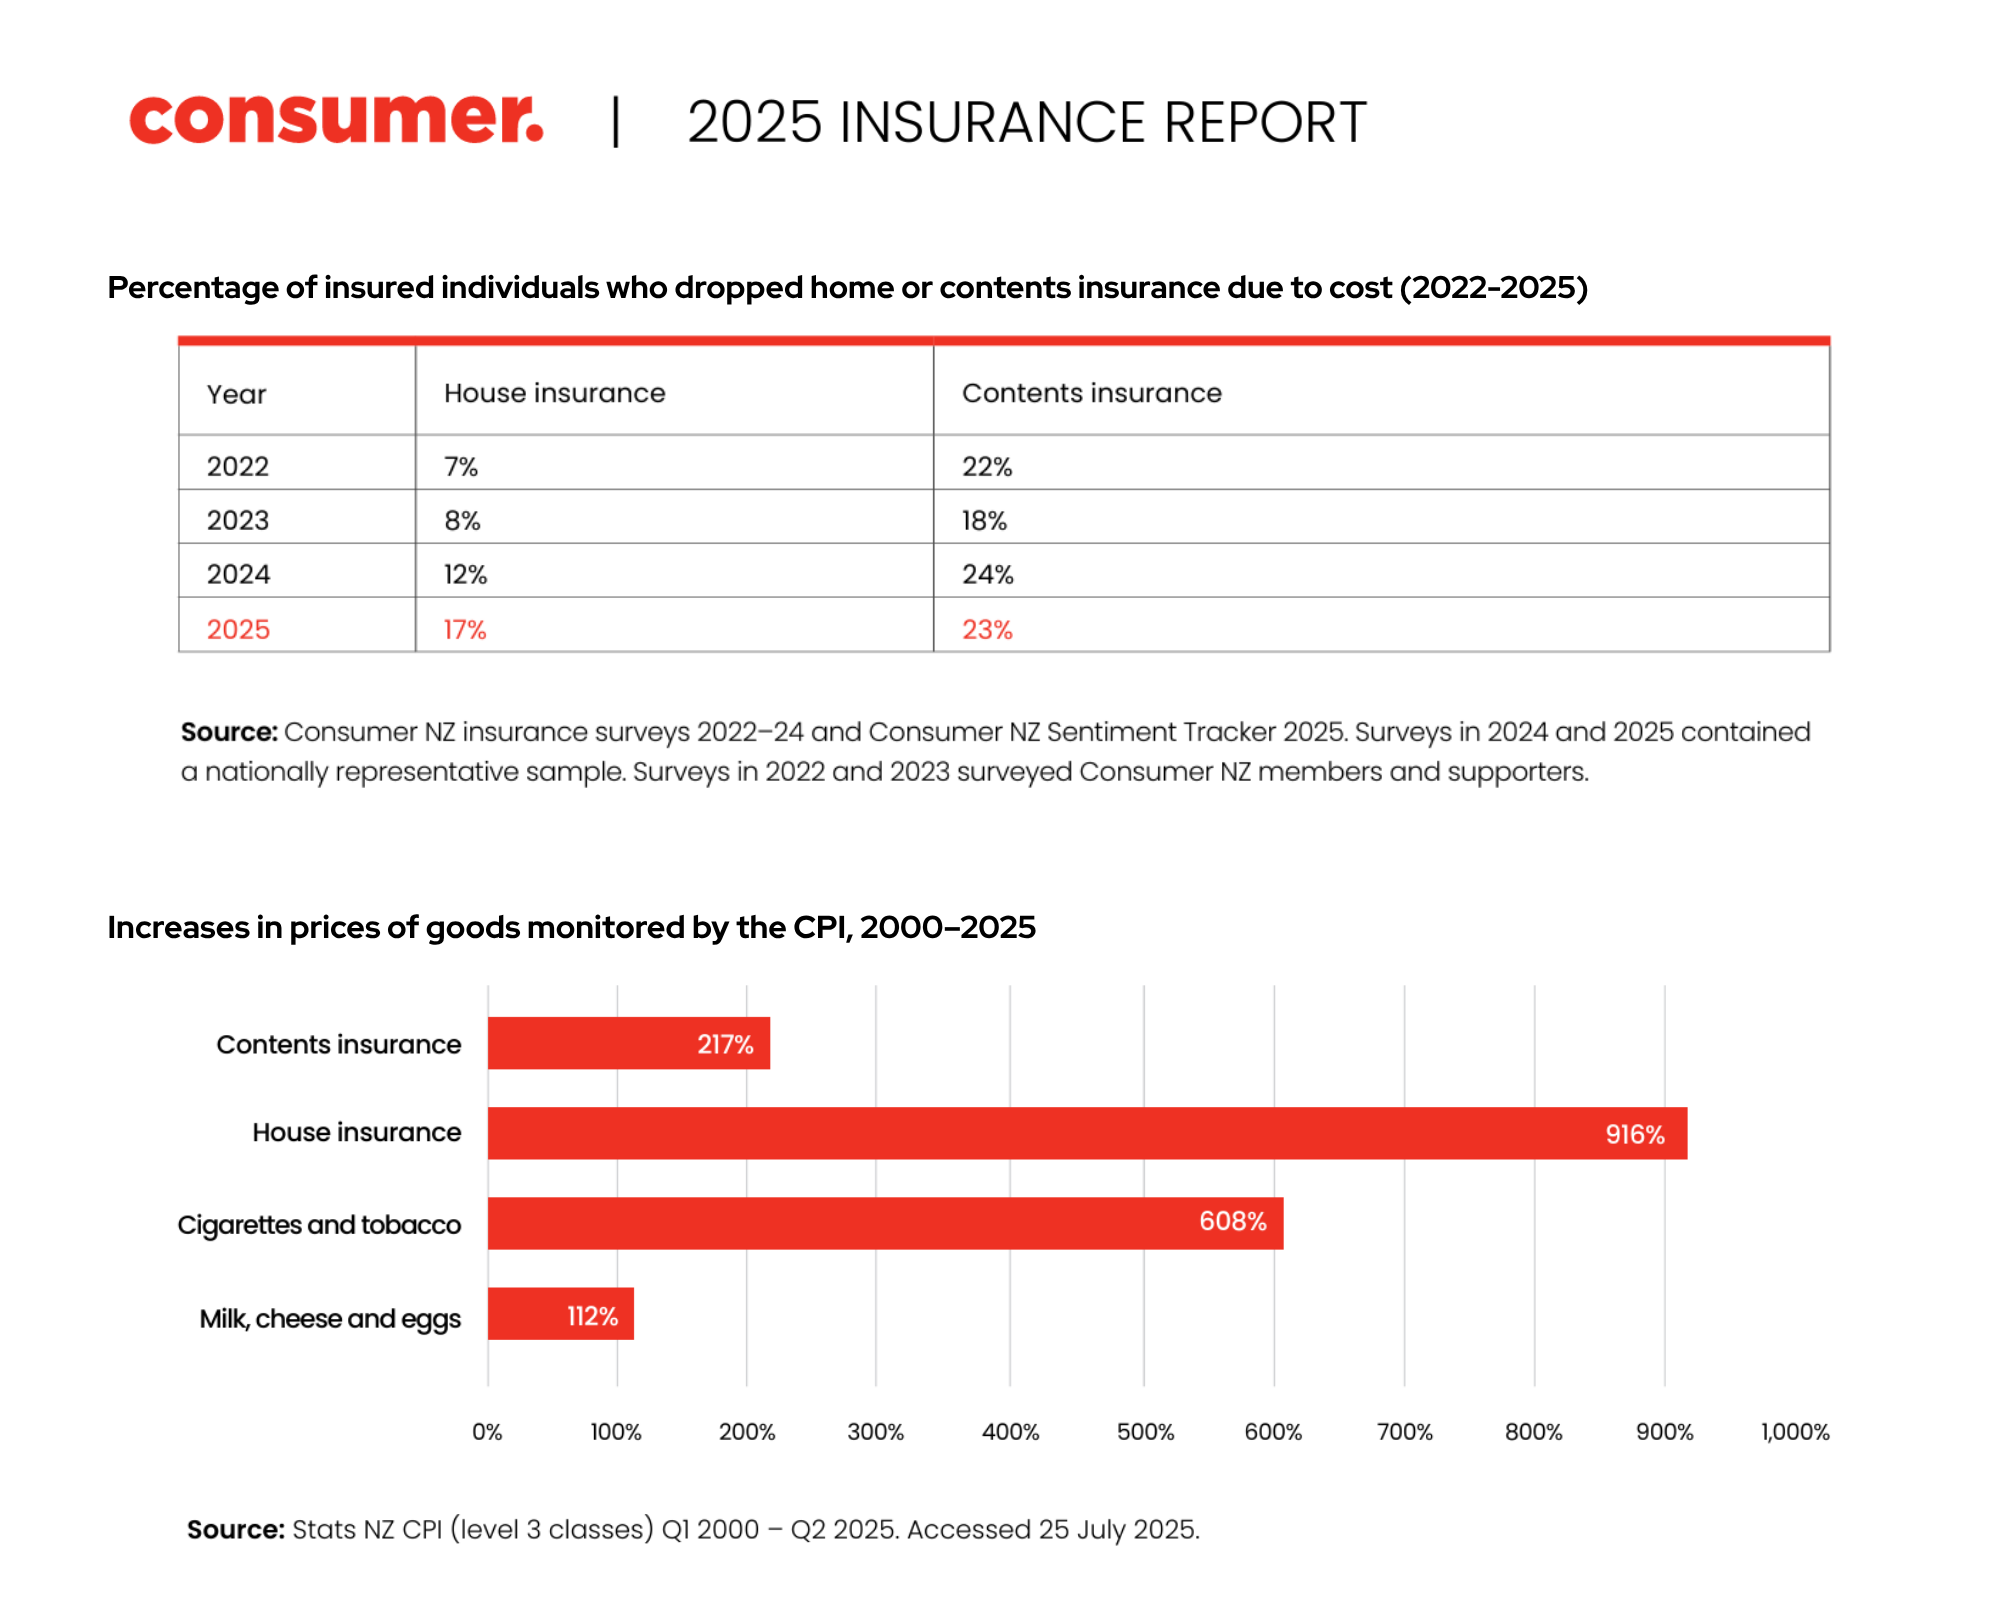
House insurance averaged $2,815 in the final quarter of 2025, a 37% jump in three years, and Consumer NZ puts the rise at three times general inflation since 2011.[5,6,7]

Explore the full Consumer Insurance Report HERE

But price is no longer the whole story. Availability is, and that is a different order of problem. A premium is a negotiation. A refusal is a wall. You cannot get a mortgage without insurance, so a house that cannot be insured cannot really be sold. The valuation does not fall because the building changed. It falls because the finance did.

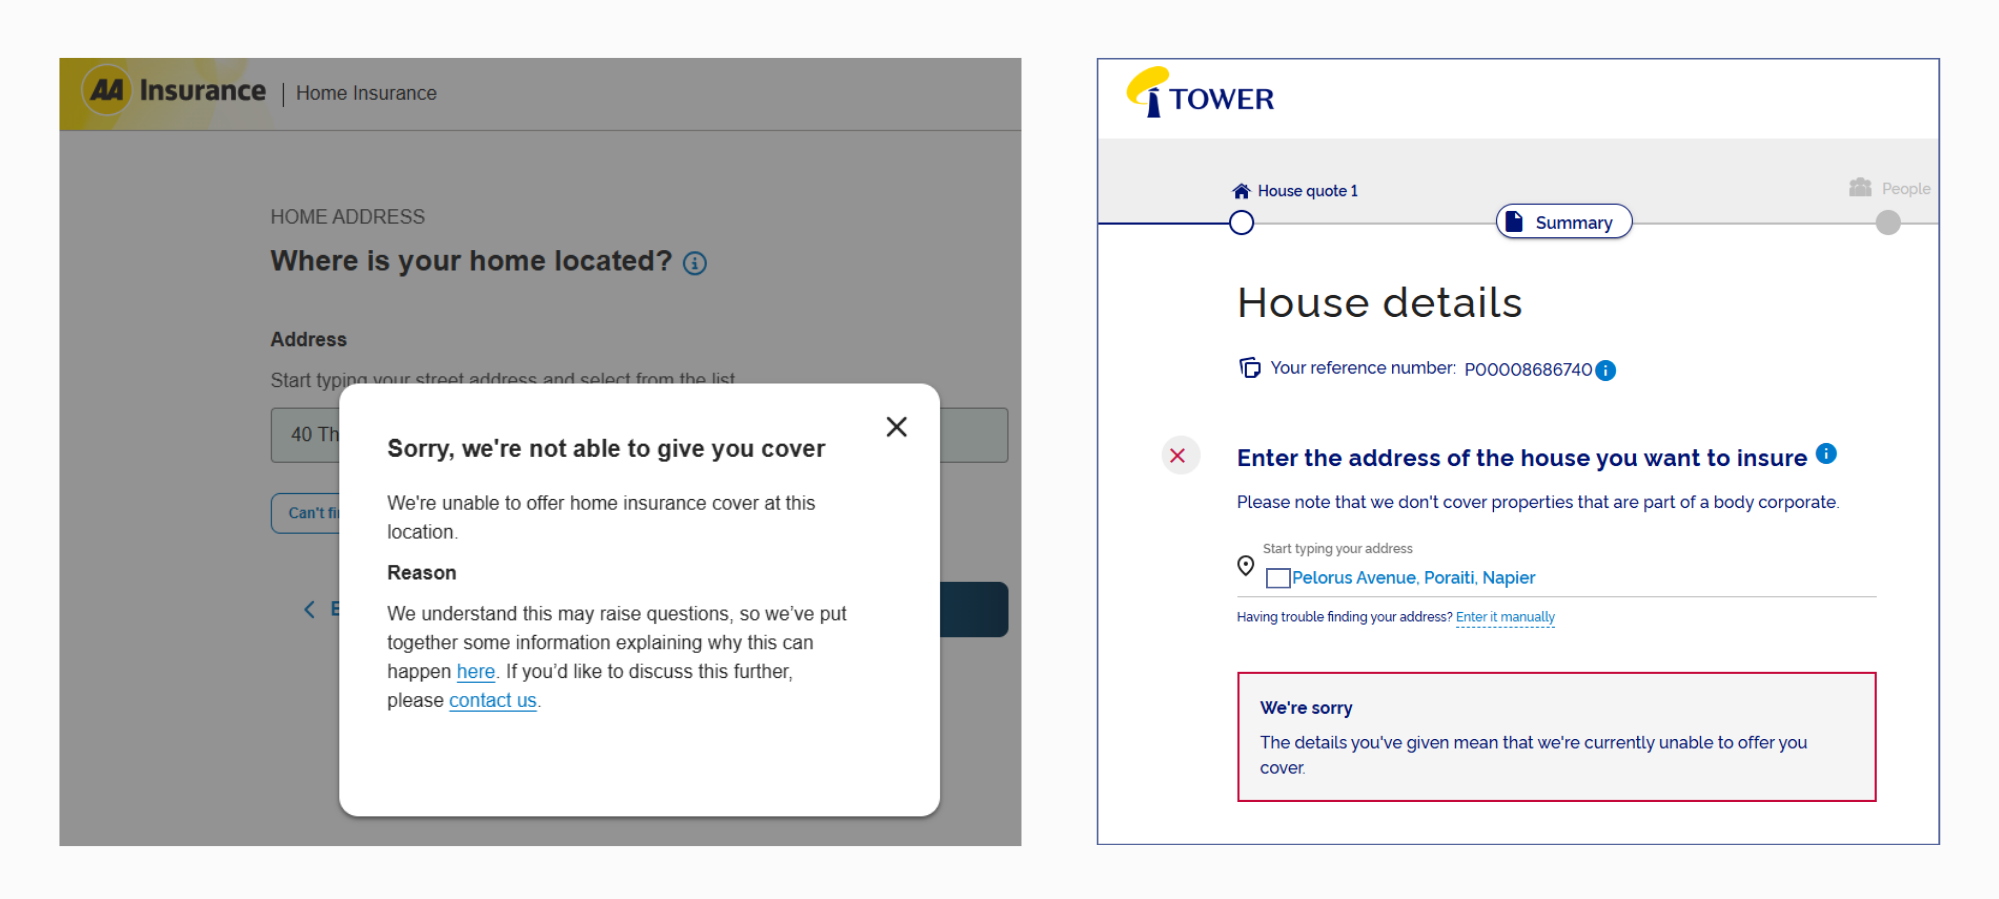
In January 2026 AA Insurance told the Buller District Mayor it would stop issuing new home, business and landlord policies across the postcode covering Westport, Carters Beach and Cape Foulwind.[8] Existing customers could renew. New buyers could not get cover at all. Within weeks it paused new policies in Woodend, citing seismic exposure rather than flood, then declined new business across Blenheim, Renwick and Seddon.[9] Legal commentators call this the beginning of a new kind of insurance retreat.[10] AA Insurance was simply the one that announced it. Others declined quietly.

Closer to Home

In April 2026 it emerged that Tower Insurance was refusing to cover some homes in Parklands Residential Estate, a modern council-owned development near Park Island in Napier. Buyers entering estate addresses into Tower's website were told cover could not be offered, the insurer citing a high risk of flooding from sea surge.[11]

These are new homes, with ground levels the council says were set above significant storm surge scenarios. And yet a major insurer would not touch them. Napier City Council is meanwhile spending $37.4 million on stormwater to protect Te Awa and Maraenui.[12] Public money, directed at a problem an insurer had already priced into its underwriting.

Cyclone Gabrielle caused $2.17 billion in insurance losses across this region, and the review that followed found new housing in areas of known flood risk suggested past lessons had not been learned.[13,14] Nobody mentioned any of this at the open home. Before you sign, enter the address into an insurer's website, read the LIM, and look at the flood hazard maps. That is the due diligence our open-home culture trains us to skip in favour of admiring the benchtops.

And Then There Are Rates

Not mortgage rates. Council rates, which are moving the same way. Stats NZ has local authority rates and payments up 8.8% in the year to March 2026, against headline inflation of 3.1%, and rates were the single largest contributor to that inflation figure.[15] Where water charges are shifting to a separate delivery entity under Local Water Done Well, the number on the rates notice is no longer the number leaving your account.

One More Thing: The Election

Every party to the left of centre now favours taxing property in some form. The differences are of instrument and degree, not direction.

Labour is campaigning on a 28% capital gains tax covering residential investment and commercial property, applying only to gains made after 1 July 2027, with the family home, farms, shares and KiwiSaver exempt. It would replace the bright-line test.[16,18]

The Greens go further, proposing a 2.5% annual super-rich tax on net assets above $10 million per individual, and a Capital Acquisitions Tax charging 33% on inheritances and gifts received above a lifetime threshold of $1 million, with family homes and family farms carved out and the tax paid by the recipient rather than the estate.[17] Opportunity, formerly TOP, proposes a land value tax of 1.75% urban and 0.5% rural.[19]

Te Pāti Māori has not published its 2026 tax policy, so its numbers for this election are not known. The direction is. The party campaigned in 2023 on a wealth tax rising to 8% on net wealth above $10 million, a 2% annual levy on property appreciation and taxes on undeveloped and vacant land, and KPMG counts it among those pressing for structural reform this time round.[16,20] Treat the 2023 figures as history rather than policy until the manifesto lands.

National, ACT and NZ First are not the mirror image of this. Neither proposes new property taxes, and their emphasis is on lower-tax settings and targeted reforms to boost investment.[16] That is closer to holding the current line than reversing it, and the current line is already favourable, with the bright-line test back to two years since July 2024 and full interest deductibility restored from April 2025. Their position is continuity, not a counter-offer.

KPMG notes that a capital gains tax is now the common denominator across the likely alternative government, although Chris Hipkins has ruled out Labour backing a wealth or inheritance tax.[16] None of it is law, and coalition negotiation will decide what any of it looks like. Voters decide on 7 November. But on one side of the House the direction of travel points squarely at property, and on the other it does not move at all.

What the Buffer Actually Buys

Take two buyers on the same street and the same income. One borrows $900,000 against a $1.05 million house. The other borrows $700,000 against an $850,000 house ten minutes further out. At 5.5% over thirty years, the gap in repayments is roughly $1,100 a month.

Nothing separates them while conditions hold. The difference appears when something moves. A one percentage point rise on $900,000 costs about $9,000 a year, against $7,000 on $700,000. A 37% jump in the premium lands on a household that has $1,100 a month of room, or on one that has none. A redundancy is a difficult year for one and a forced sale for the other.

That $200,000 was never really about the house. It was about buying the ability to wait, and the resale data says waiting is the whole game.

The Boring Alternative

Buy less than you can borrow. Keep a buffer. Sleep at night.

The house ten minutes further from the school zone that costs $200,000 less is not a failure. It is a margin of safety, and more to the point it is time. It is the difference between selling at 4.3 years because you have to and holding for 10.4 years because you can. It is the room to fix the roof without going back to the bank, and to stop doing anxious arithmetic at 2am. If you think professional advice is expensive, try using an amateur.

Property can be a wonderful long-term asset. But the best house you can afford is not the best house for you. It is just the biggest risk you were allowed to take.

The bank will tell you what you can borrow, not what you should. For that, seek impartial advice and wise counsel.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


References

1. Cotality - Share of NZ Homes Selling for a Profit Falls to Lowest Level Since 2012. cotality.com/nz, 17 August 2026. https://www.cotality.com/nz/insights/articles/share-of-nz-homes-selling-for-a-profit-falls-to-lowest-level-since-2012

2. Mortgage Express NZ - Is Now the Right Time to Lock in Your Home Loan Rate? mortgage-express.co.nz

3. Canstar NZ - In Which Direction Are Mortgage Interest Rates Headed? canstar.co.nz, June 2026

4. Reserve Bank of New Zealand - Official Cash Rate raised 25 basis points to 2.50%, 8 July 2026. rbnz.govt.nz

5. Quashed - Why Is My House Insurance So Expensive? 2026 NZ Premium Hike Guide. quashed.co.nz

6. Reserve Bank of New Zealand - Insurance Availability and Risk-Based Pricing, Financial Stability Report, May 2024. rbnz.govt.nz

7. Consumer NZ - What's Going On With Home Insurance? consumer.org.nz, February 2026

8. RNZ - Insurer Temporarily Halts New Policies in Westport Due to Flood Risk. rnz.co.nz, 28 January 2026

9. NZ Herald - Major Insurer Declines New Home Insurance Policies for Blenheim. nzherald.co.nz, 3 February 2026

10. Minter Ellison - Insurers Dial Back Flood Risk Exposure: Where Will This Lead? minterellison.co.nz, May 2026

11. 1News - Insurer Flags Sea Surge Risk for Some Napier Estate Properties. 1news.co.nz, April 2026

12. Napier City Council - $37.4M Stormwater Investment Unlocks 400 Homes and Flood Protection for Napier. napier.govt.nz, December 2025

13. Insurance Business NZ - Hawke's Bay Homeowners Face Insurance Woes, Rising Security Risks. insurancebusinessmag.com, November 2024

14. Insurance Business NZ - Hawke's Bay Flood Review Highlights Need for Improved Risk Management. insurancebusinessmag.com, July 2024

15. Stats NZ - Annual Inflation at 3.1 Percent in March 2026: Local Authority Rates and Payments Up 8.8 Percent. stats.govt.nz, April 2026

16. KPMG New Zealand - Summary of 2026 Election Tax Policies. kpmg.com/nz, August 2026

17. 1News - Greens Propose Wealth, Inheritance Taxes to Fund Income Tax Changes. 1news.co.nz, 21 June 2026

18. Buddle Findlay - Labour's Capital Gains Tax: Time to Think Ahead. buddlefindlay.com, 2026

19. The Post - Opportunity Party Reveals Policies on Land Tax, Universal Basic Income and KiwiSaver Reform. thepost.co.nz, May 2026

20. RNZ - Te Pāti Māori Proposes Suite of Changes in New Tax Policies. rnz.co.nz, 27 July 2023. No 2026 tax policy published as at 20 August 2026


When the Process Becomes the Cover

Article #466

Two stories crossed my desk last month, half a world apart, joined by the same affliction: institutions so wedded to their own process that they lose sight of the people it should serve, and then reach for that process as a shield. The pattern is worth naming, because it is far more common than outright wrongdoing and far harder to spot. Nobody sets out to fail. They simply follow the steps, tick the boxes, and assume the machine will catch what they did not.

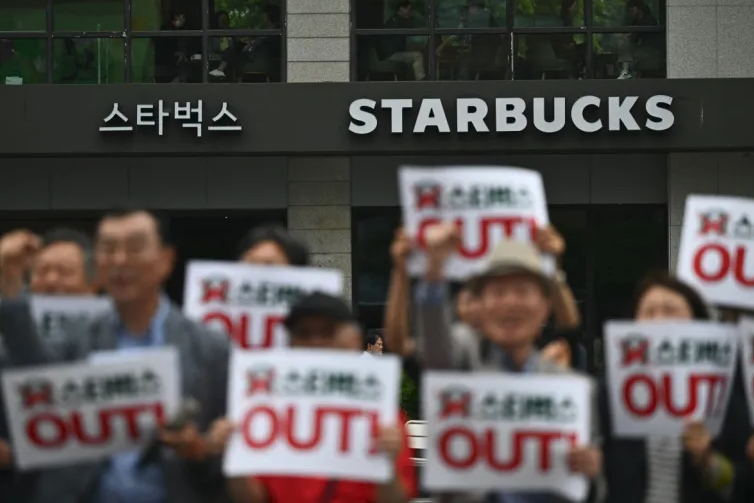
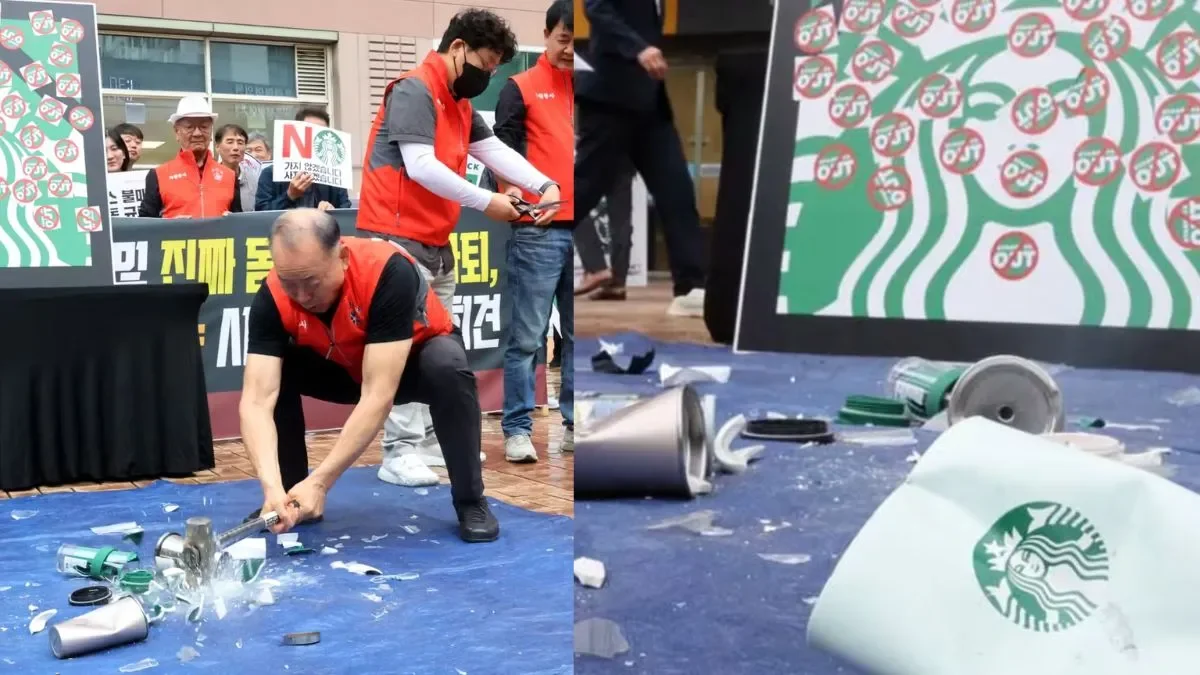
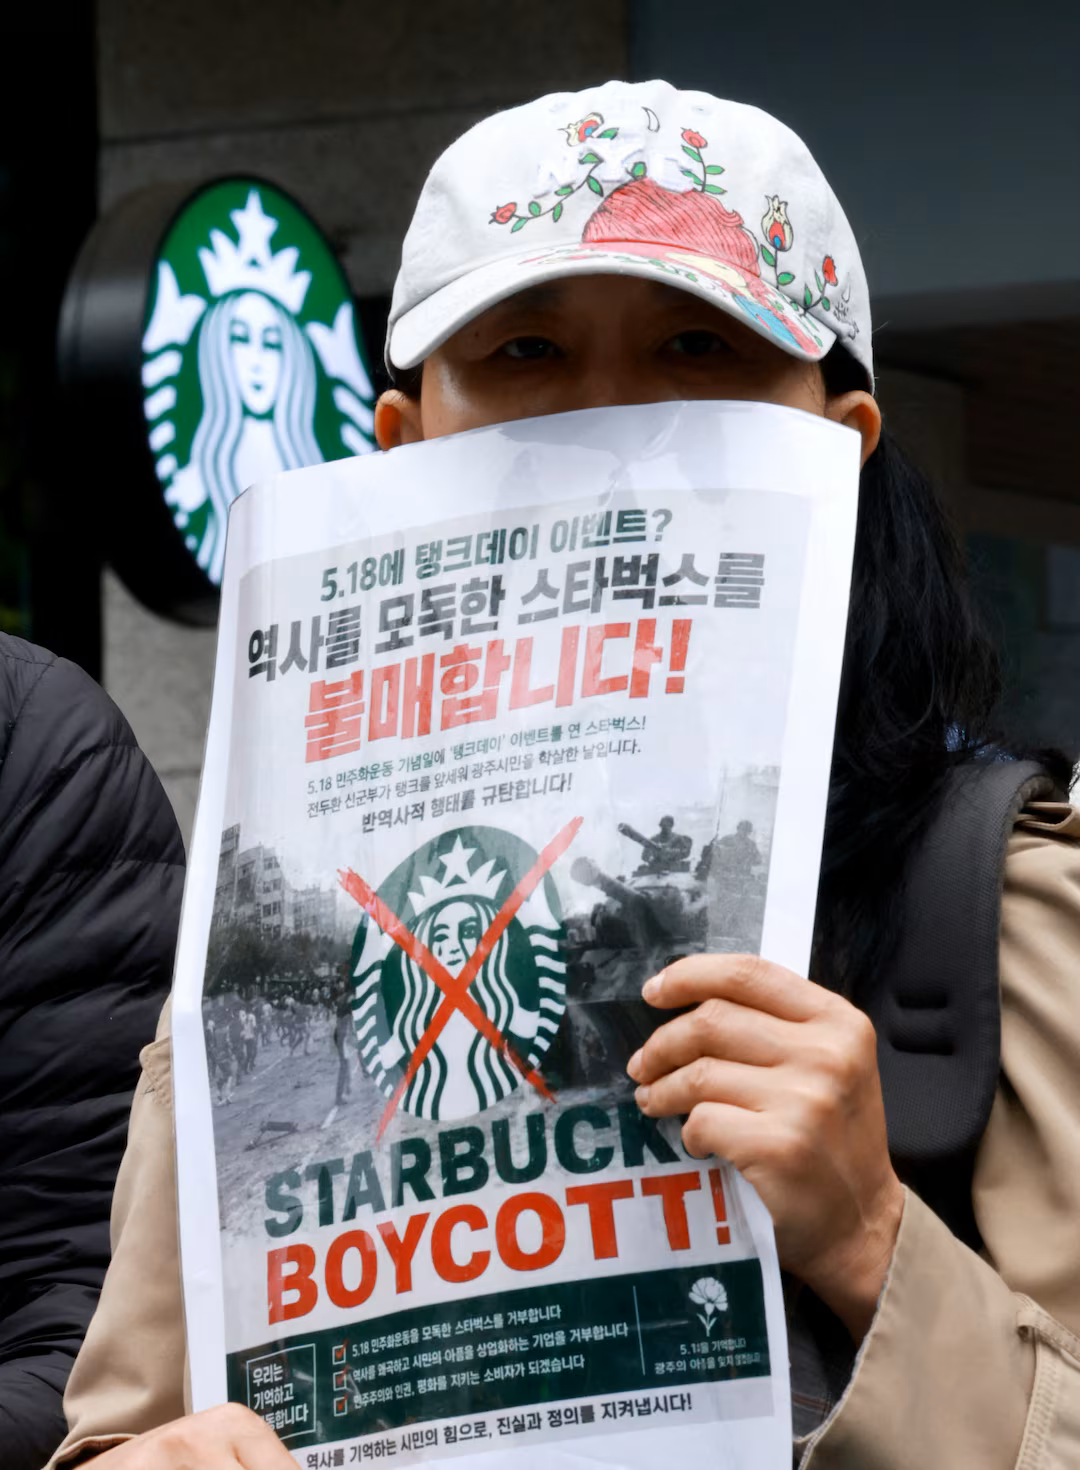
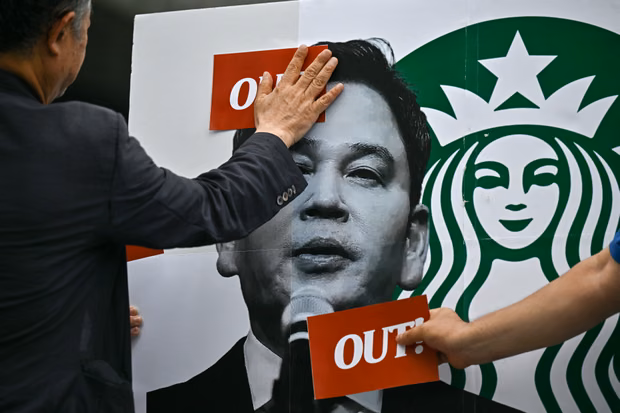
Our first story comes courtesy of former MP Rick Barker. Starbucks South Korea launched a promotion for “Tank Day” on 18 May, the anniversary of the 1980 Gwangju massacre, when the military rolled tanks over pro-democracy protesters and killed hundreds [1].

It did not land well.

The Korea CEO was sacked and weekly sales fell more than a quarter [2]. What makes the episode instructive is not that a mistake was made, but how it was made. Reports suggest the marketing team asked an AI tool for suggestions, the approving officials never opened the design file, and the legal review was skipped entirely [3]. Every gate that should have stopped it was either delegated or waved through. Not malice, but blindness – the particular blindness of people who trusted the process to do their looking for them.

In story two, we return to Hastings. Council consulted on an Annual Plan offering a 5.9 or 9.1 percent rates rise, and businesses across the district budgeted accordingly [4]. Then Quotable Value’s revaluation landed. Commercial and industrial land values had risen sharply while residential values fell close to 20 percent. Because rates are apportioned by property value, that swing shifted a far larger share of the burden onto commercial owners – not through any decision to target them, but as an automatic consequence of the arithmetic. One inner-city operator told the Herald his rates were jumping almost 30 percent, a rise he believed could end his business [4]. The certified figures arrived only two working days before submissions closed, creating an extremely limited window for the very people most affected to respond.

The official line was that Council did not have the numbers until early May. Under questioning, that account became more complicated. The mayor acknowledged she had received an indication that there could be a significant shift [5]. A councillor has since stated that officers held a pre-audit valuation report in February and March showing commercial values rising and residential values falling, yet ratepayers were given no warning [6]. The distinction matters. There is a difference between not having a certified, audited, signed-off figure and having no idea at all which way the wind was blowing.

That admission raises a fair question: whether earlier, plainer communication could have helped affected ratepayers prepare, even without the final numbers in hand. You do not need certified figures to the last decimal to tell a café owner a storm may be coming. Not knowing the final number is not the same as knowing nothing. A warning that a material shift was likely – caveated, provisional, honest about its uncertainty – would have cost the Council nothing and given businesses time to plan, to model their exposure, to organise a considered submission rather than a scramble.

Then, after a second round of consultation and 233 submissions seeking relief, Council retained the differentials in full and deferred the rating review to the 2027 Long Term Plan [7]. A pause on the Hastings CBD targeted rate was offered as the consolation; Havelock North businesses did not receive the same relief [7]. And the decision was posted immediately before a long weekend – a timing that, whatever the intention behind it, did little to foster the perception of an open and confident process. Institutions that are proud of a decision tend to announce it in daylight.

With amalgamation now looming [8], the deferral carries a further risk. A review pushed out to a future Long Term Plan may ultimately be inherited by an entity that never made the promise. A commitment made by one council to revisit its rating approach is only as durable as that council; restructure the furniture and the promise can quietly fall down the back of it.

There was, it turns out, an alternative on the table. A councillor had proposed a different differential before consultation opened, one that eased the commercial burden while nudging the rural villages toward parity. He and four colleagues voted against the status quo; ten voted to retain it. His alternative could not proceed, he says, because the modelling had not been completed [6]. Whatever the merits of his particular proposal, the sequence is telling: an option existed, and the process – not a debate on its substance – was the reason it went no further. When process appears to foreclose the consideration of alternatives rather than enable it, confidence in the process itself begins to suffer.

Let me be clear about what this is and is not. The rates were never the real issue. Revaluations happen; they are an independent statutory exercise the Council does not control, and this one at least spared many households the worst by loading the swing onto commercial property instead. The more significant issue is confidence in the process that surrounds the numbers: whether people were given timely information, whether options were genuinely explored, and whether the concerns of those affected received meaningful consideration before the die was cast.

Starbucks lost a quarter of its sales because nobody thought to examine the impact of what they were about to do. Hastings’ ratepayers risk losing something slower to rebuild: the confidence that important information will be shared with them while there is still time to act on it. Trust is the one asset a council cannot borrow against. It does not appear on any balance sheet, it cannot be levied, and once it is spent it cannot be refinanced.

As Hawke’s Bay considers significant structural change through possible amalgamation, the lesson extends well beyond one year’s rates. Public institutions do not earn trust because every decision they make is popular – that is an impossible standard and not a sensible one. They earn it when people feel informed, heard and treated fairly throughout the process, win or lose. Consultation, transparency and candour are not administrative box-ticking to be completed and filed; they are the foundation upon which public confidence actually rests. Once that confidence begins to erode, rebuilding it is far harder, and far more expensive, than preserving it in the first place. That is a lesson worth learning before the machinery of local government is rebuilt, not after.


Nick Stewart

(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe,
Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz


REFERENCES

  1. “Starbucks Apologizes After Ad Campaign Evokes Massacre,” Associated Press, May 2026; Branding in Asia, “Shinsegae Chairman Issues Apology Over Starbucks Korea ‘Tank Day’ Campaign,” May 2026.

  2. “Starbucks’ Korea sales plunge after Tank Day marketing backlash,” Reuters, May 2026; CEO Sohn Jeong-hyun dismissed per CNN.

  3. “Foreign Media Spotlight Starbucks Korea’s ‘Tank Day’ Backlash and Sales Plunge,” Seoul Economic Daily / Yonhap, 27 May 2026.

  4. “Hastings business says rate hike of almost 30% could end them, mayor ‘beyond livid’ with situation,” NZ Herald / Hawke’s Bay Today, June 2026.

  5. Public meeting convened by the Hastings and Havelock North Business Associations, 4 June 2026.

  6. Cr Steve Gibson, public statement on the 2026/27 Annual Plan decision, July 2026: pre-audit valuation report in February/March, 25–75 percent impact estimate, alternative rating differential proposal, and 10–5 vote to retain the existing differentials. Facebook.

  7. “Council adopts 2026/27 Annual Plan,” Hastings District Council, July 2026 (differentials retained; rating review deferred to the 2027 Long Term Plan; Hastings CBD targeted rate pause).

  8. “Majority of Hawke’s Bay submitters favour amalgamation into one council,” Hawke’s Bay Today, 14 July 2026.


Why Holding Cash Feels Safe - But Isn't Always Wise

The ‘security’ of cash today often comes at the expense of tomorrow's purchasing power.

New Zealanders tend to hold cash reserves despite changing interest rate conditions. The RBNZ has cut the Official Cash Rate to 3.0% in August 2025 from its peak of 5.5% in early 2024, with term deposits following suit. While declining in line with the OCR, term deposit rates remain attractive; the highest rates on Canstar's database sit at 4.50%.

Yet, NZ’s economy contracted in the second quarter of 2025. Inflation increased to 2.70% in the same period[1] – well within the RBNZ's 1-3% target band but adding pressure to real returns.

The Money Illusion Trap

Many investors fall victim to what economists call "the money illusion": thinking about money in nominal rather than real terms[2].

A $100,000 term deposit earning 4.5% generates $4,500 annually, which feels like growth. But for someone paying 33% tax, the after-tax return is just $3,015 (3.015%). With inflation at 2.7%, this creates a real return of just 0.315%. For those in the top tax bracket (39%), this return becomes 2.745% - providing a microscopic real return of $45. That’s barely enough to buy a decent bottle of wine to drown your wealth preservation strategy sorrows.

Major bank economists forecast the OCR will fall to 2.5% by the end of 2025 or early 2026[3]. If term deposits drop to around 3%, a 33% taxpayer will earn an even measlier 2.01%.

Hidden Costs of Cash Comfort

Opportunity Cost: While current term deposits offer reasonable returns, historical equity market returns in New Zealand averaged 7-10% annually over longer periods. That 2-5% difference compounds substantially over decades.[4]

Rate Dependency Risk: With the two-year swap rate expected to drop to 2.8% as the OCR reaches 2.5%, retail deposit rates will follow. Unlike growth assets that can benefit from economic recovery, cash offers no upside participation.

Inflation Protection: Cash provides no hedge against rising costs. With administered prices driving near-term inflation pressures, purchasing power erosion remains a persistent threat.

The Economic Reality Check

New Zealand's economic recovery stalled in the second quarter. Spending is constrained by global economic policy uncertainty, falling employment, higher goods prices, and declining house prices. RBNZ notes there is scope to lower the OCR further if medium-term inflation pressures continue to ease as expected[5].

This makes holding large cash positions riskier; cash-savers face declining returns and miss potential recovery gains in other asset classes.[6]

Cash has its place – as part of a strategic, sophisticated portfolio, where professional advisers can implement a bond laddering strategy (providing income stability with superior yields to deposits), liquidity management to provide regular cash flow and reduce the need for large cash reserves and can recommend PIE funds and other tax-efficient structures that minimise the tax drag.

The Value of Professional Advice

History has shown many investors start panic selling during downturns, chasing performance at market peaks, or hoarding cash.

When cash returns are low, investors venture into adventurous territory: junk bonds, private credit, mezzanine debt arrangements, and other high-yield instruments that carry higher risks.

Working with a fee-only, fiduciary adviser is invaluable. Look for advisers who:

  • Conduct thorough discovery of your financial situation

  • Explain their investment philosophy and process clearly

  • Provide transparent fee disclosure with no hidden commissions

  • Demonstrate relevant credentials (CFP, AIF, CEFEX)

  • Show measurable progress tracking methods

 The Bottom Line

With NZ’s economic headwinds, sitting in cash isn't the safe option - it's the wealth erosion option.

"She'll be right" doesn't cut the mustard when your money's losing value faster than a leaky boat. After tax and inflation, that "safe" term deposit is barely keeping you afloat. Your future wealth depends on making this distinction now, not when it's convenient.


Nick Stewart
(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe, Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz

  • Article no. 423


References

  1. Trading Economics. (2025). New Zealand Inflation Rate - Q2 2025. Available at: https://tradingeconomics.com/new-zealand/inflation-cpi

  2. Shafir, E., Diamond, P., & Tversky, A. (1997). Money Illusion. Quarterly Journal of Economics, 112(2), 341-374.

  3. ANZ Bank New Zealand. (2025). Weekly Data Wrap: Economic Forecasts and OCR Projections. Available at: https://www.anz.co.nz/about-us/economic-markets-research/data-wrap/

  4. NZX Limited. (2024). Historical Returns Analysis: New Zealand Equity Market Performance 1987-2024. Wellington: NZX.

  5. Reserve Bank of New Zealand. (2025). Monetary Policy Statement August 2025. Wellington: RBNZ. Available at: https://www.rbnz.govt.nz/hub/publications/monetary-policy-statement/2025/08/monetary-policy-statement-august-2025

  6. DALBAR Inc. (2024). Quantitative Analysis of Investor Behavior: New Zealand Market Study. Boston: DALBAR Research.

Navigating New Zealand’s Economic Crossroads - A Canny View

The Rate Cut Reality Check: Too Little, Too Late

Next Wednesday's anticipated 25 basis point cut to 3%[i] represents more than monetary policy adjustment—it's an admission of New Zealand's economic fragility, yet likely inadequate given our challenges. While markets celebrate cheaper money, this modest response highlights policy inertia.

The Reserve Bank's hand has been forced by unemployment climbing to 5.2%—the highest since 2016—and wage growth softening to its slowest pace in years. Private sector wages have decelerated to just 2.2% annually, whilst underutilisation has surged to 12.8%[ii]. Yet the expected quarter-point response appears tepid when economic data screams for decisive action.

As former Finance Minister Ruth Richardson commented, Treasury's warnings about New Zealand's fiscal sustainability aren't mere technical observations—they're alarm bells signalling "greater pressure on the fiscal position than we have in the last 20 years"[iii].

Higher starting debt, unfavourable interest rates, adverse growth trends, and long-term pressures from aging and climate change are converging into a perfect storm. Despite claims of $44 billion in savings, government has reallocated spending rather than shrinking it [iii].

It's hard for hope not to fade when our government appears to lack the mettle to take the bull by the horns. The "price of butter" facade may have fooled some, but not many. Butter is a product that hasn't changed in eons—full cream milk, add salt and churn. No smoke and mirrors or PR spin, just butter. Yet politicians obsess over its retail pricing whilst avoiding hard decisions on fiscal consolidation that might actually address underlying inflation pressures. 

The Great Capital Migration

Capital flows as freely as people in an interconnected world. Just as 230,000 Kiwis have voted with their feet over two years seeking better opportunities offshore[iv], smart money increasingly looks beyond our borders for superior returns.

The recent emigration shows a damning verdict on New Zealand's economic trajectory. These are productive citizens, who see limited prospects in a country determined to tax productivity whilst subsidising speculation. Human capital flight and financial capital mobility share parallels—both respond to incentives and seek the best risk-adjusted returns.

Housing Market Dysfunction Remains

Our housing market remains in purgatory, with prices stubbornly elevated while transaction volumes are sluggish. Latest data shows ‘days to sell’ extending and prices slipping nationally for six of the past seven months[v]. Wednesday's modest rate cut is unlikely to break this deadlock.

Young Kiwis are emigrating, recognising their homeownership prospects have been systematically destroyed by policies prioritising incumbent wealth over economic dynamism. The social contract promising hard work would lead to homeownership has been broken: 72% of Kiwis without a home believe buying a property is beyond their reach[vi]. Yet, many Kiwis remain dangerously over-exposed to residential real estate.

Rethinking Investment

The traditional Kiwi approach of leveraging into property and hoping for the best is dangerous where house prices may stagnate whilst debt service costs remain higher.

Global equity markets continue to climb, with the S&P 500 delivering 5-year annualised returns of 15.71%. Meanwhile, New Zealand's NZX50 has delivered a dismal 1.8% annualised return over the same period [vii].

The performance gap is devastating. A $100,000 investment in the S&P 500 over five years would have grown to $208,000, versus approximately $109,000 in the NZX50. This $99,000 difference[vii] is a documented reality for investors who remained domestically focused while global opportunities compounded wealth at dramatically higher rates.

Complexity extends beyond simple asset allocation. Tax implications vary dramatically between domestic and international investments. Currency hedging decisions can make or break returns. Liquidity needs must account for potential emigration scenarios—a consideration rational investors now embrace.

A skilled financial adviser becomes essential for protecting and growing wealth whilst navigating emotional challenges of investing against your home country's prospects.

Economic Crossroads Ahead

New Zealand stands at an economic crossroads between fiscal irresponsibility leading to Japanese-style stagnation, or making hard decisions to restore economic dynamism. Next Wednesday's timid rate cut suggests we're choosing the former.

For investors, the message is clear: adapt or suffer consequences. Capital, like talent, flows to where it's best treated. The 230,000 Kiwis who've recognised this reality are canaries in the coal mine. Smart investors should ensure their wealth enjoys the same mobility their fellow citizens have embraced.

The coming rate cut won't be cause for celebration—it will be a symptom of deeper malaise and policy impotence facing structural decline.


[i] https://www.interest.co.nz/economy/134636/kiwibank-economists-say-all-key-data-released-ahead-reserve-banks-official-cash-rate

[ii] Statistics New Zealand - Labour Force Report, June 2025 quarter https://www.stats.govt.nz/information-releases/labour-market-statistics-june-2025-quarter/

[iii] Newstalk ZB Radio Interview - Ruth Richardson (Former Finance Minister, Chair of Taxpayers Union) interviewed by Heather du Plessis-Allan, 8th August 2025 https://www.newstalkzb.co.nz/on-air/heather-du-plessis-allan-drive/audio/ruth-richardson-former-finance-minister-says-nicola-willis-needs-to-face-up-to-the-latest-treasury-report/

[iv] Statistics New Zealand - International Travel and Migration Statistics, Monthly releases 2023-2025: Net permanent and long-term migration data showing departures of New Zealand citizens seeking opportunities offshore.

[v] Craig's Investment Partners - "Onboard" podcast, Episode 291, August 10th, 2025: Mark Lister, Investment Director, discussing OCR expectations, labour market data, global equity performance, dairy prices, currency movements, and central bank policy decisions.

[vi] MPA Mag – “Most Kiwis Say Homeownership is Out of Reach” https://www.mpamag.com/nz/news/general/most-kiwis-say-homeownership-is-out-of-reach-report/545632
Good Returns – “Gloomy Home Ownership Results” https://www.goodreturns.co.nz/article/976524736/gloomy-home-ownership-results.html

[vii] S&P Dow Jones Indices - S&P/NZX 50 Index factsheet, July 31, 2025: 5-year annualized total return data. State Street S&P 500 Index fund performance data showing 5-year annualised returns for comparative analysis. Calculation: $100,000 invested at 15.71% annually over 5 years = $208,000 (S&P 500) vs $100,000 invested at 1.8% annually over 5 years = $109,000 (NZX50). Performance gap: $99,000.


Nick Stewart
(Ngāi Tahu, Ngāti Huirapa, Ngāti Māmoe, Ngāti Waitaha)

Financial Adviser and CEO at Stewart Group

  • Stewart Group is a Hawke's Bay and Wellington based CEFEX & BCorp certified financial planning and advisory firm providing personal fiduciary services, Wealth Management, Risk Insurance & KiwiSaver scheme solutions.

  • The information provided, or any opinions expressed in this article, are of a general nature only and should not be construed or relied on as a recommendation to invest in a financial product or class of financial products. You should seek financial advice specific to your circumstances from a Financial Adviser before making any financial decisions. A disclosure statement can be obtained free of charge by calling 0800 878 961 or visit our website, www.stewartgroup.co.nz

  • Article no. 420

Lazy Money

In its latest interest rate decision on 14 April, the Reserve Bank of New Zealand's Monetary Policy Committee maintained its official cash rate at a historic low of 0.25 per cent, introduced earlier in 2020, and its medium-term outlook remains highly uncertain, determined in large part by both health-related restrictions, and business and consumer confidence.